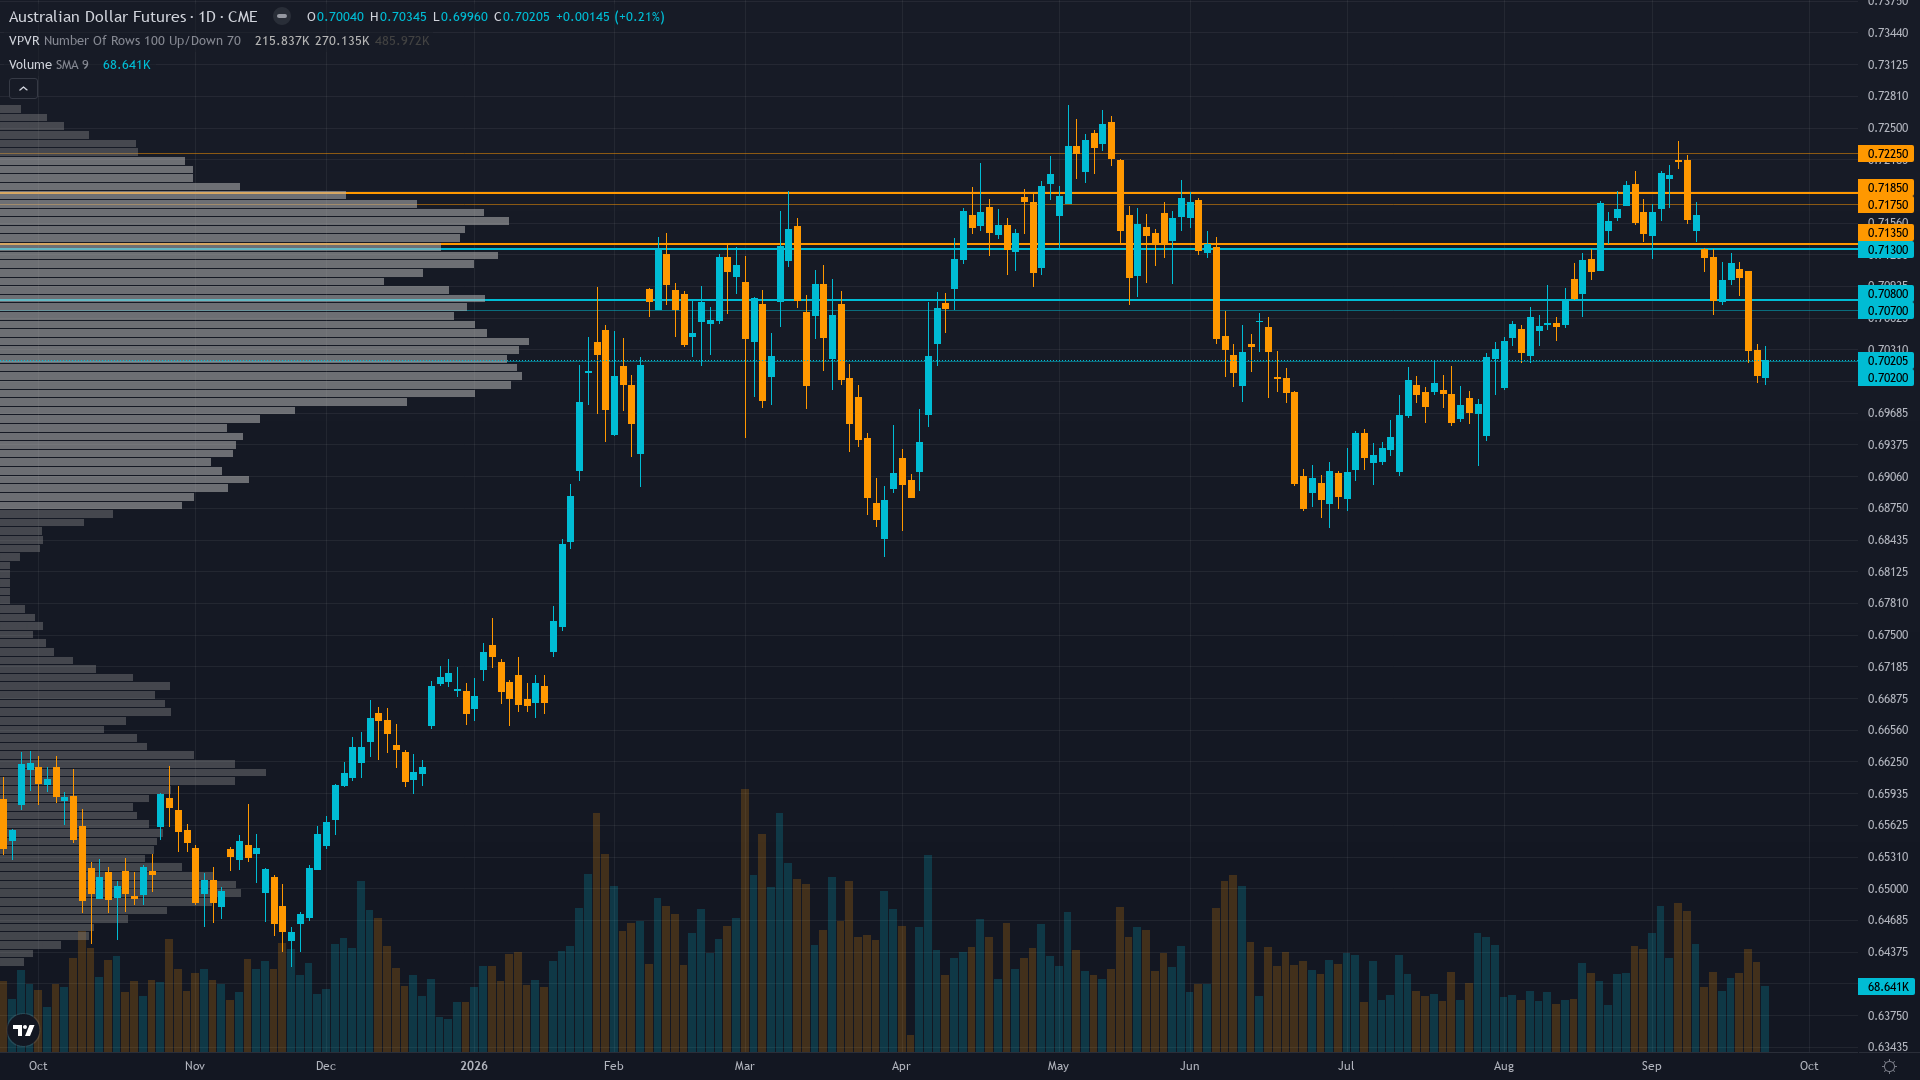
AUD/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's AUD/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
This week's AUD/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
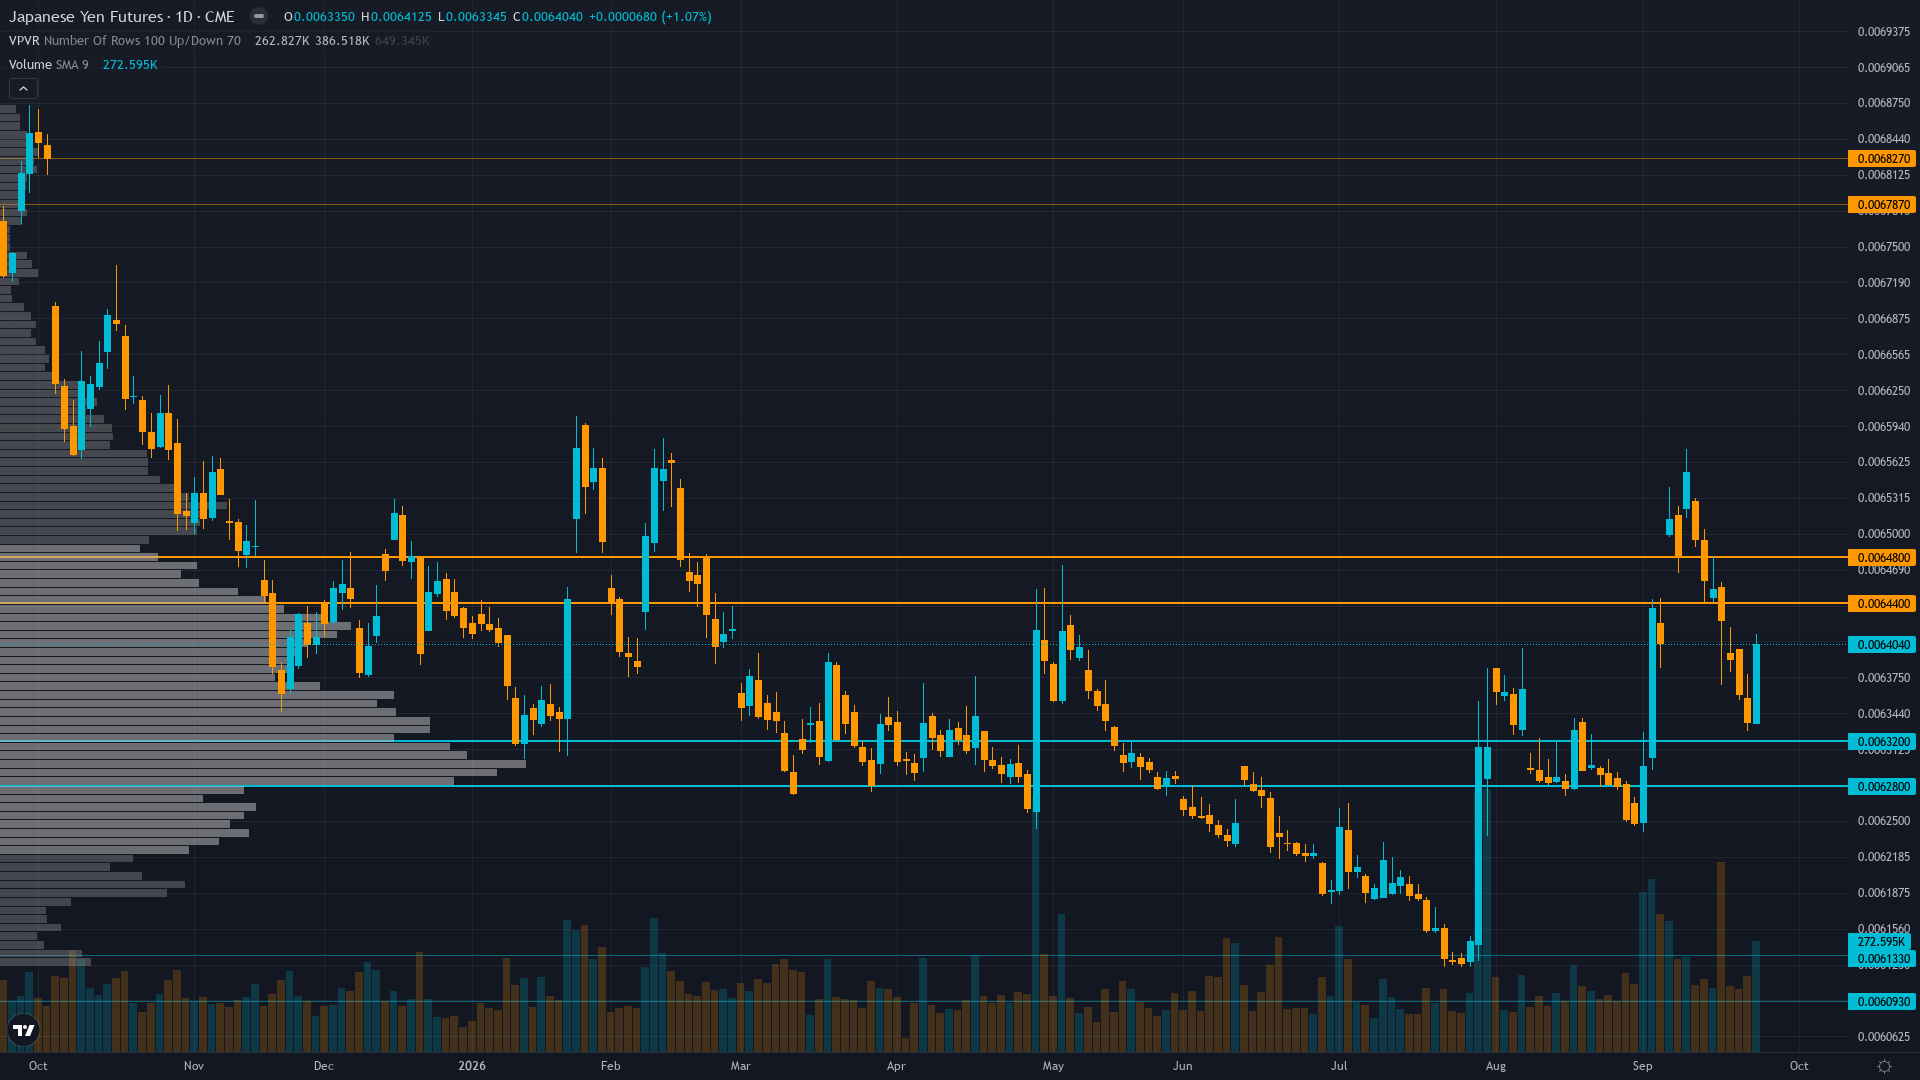
Japanese Yen key levels breakdown: support zones, resistance zones, confluence and price structure.
This week's Japanese Yen outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

This week's Gold outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
Japanese Yen institutional positioning: COT data, sentiment analysis and smart money flow assessment.
Gold key levels breakdown: support zones, resistance zones, confluence and price structure.
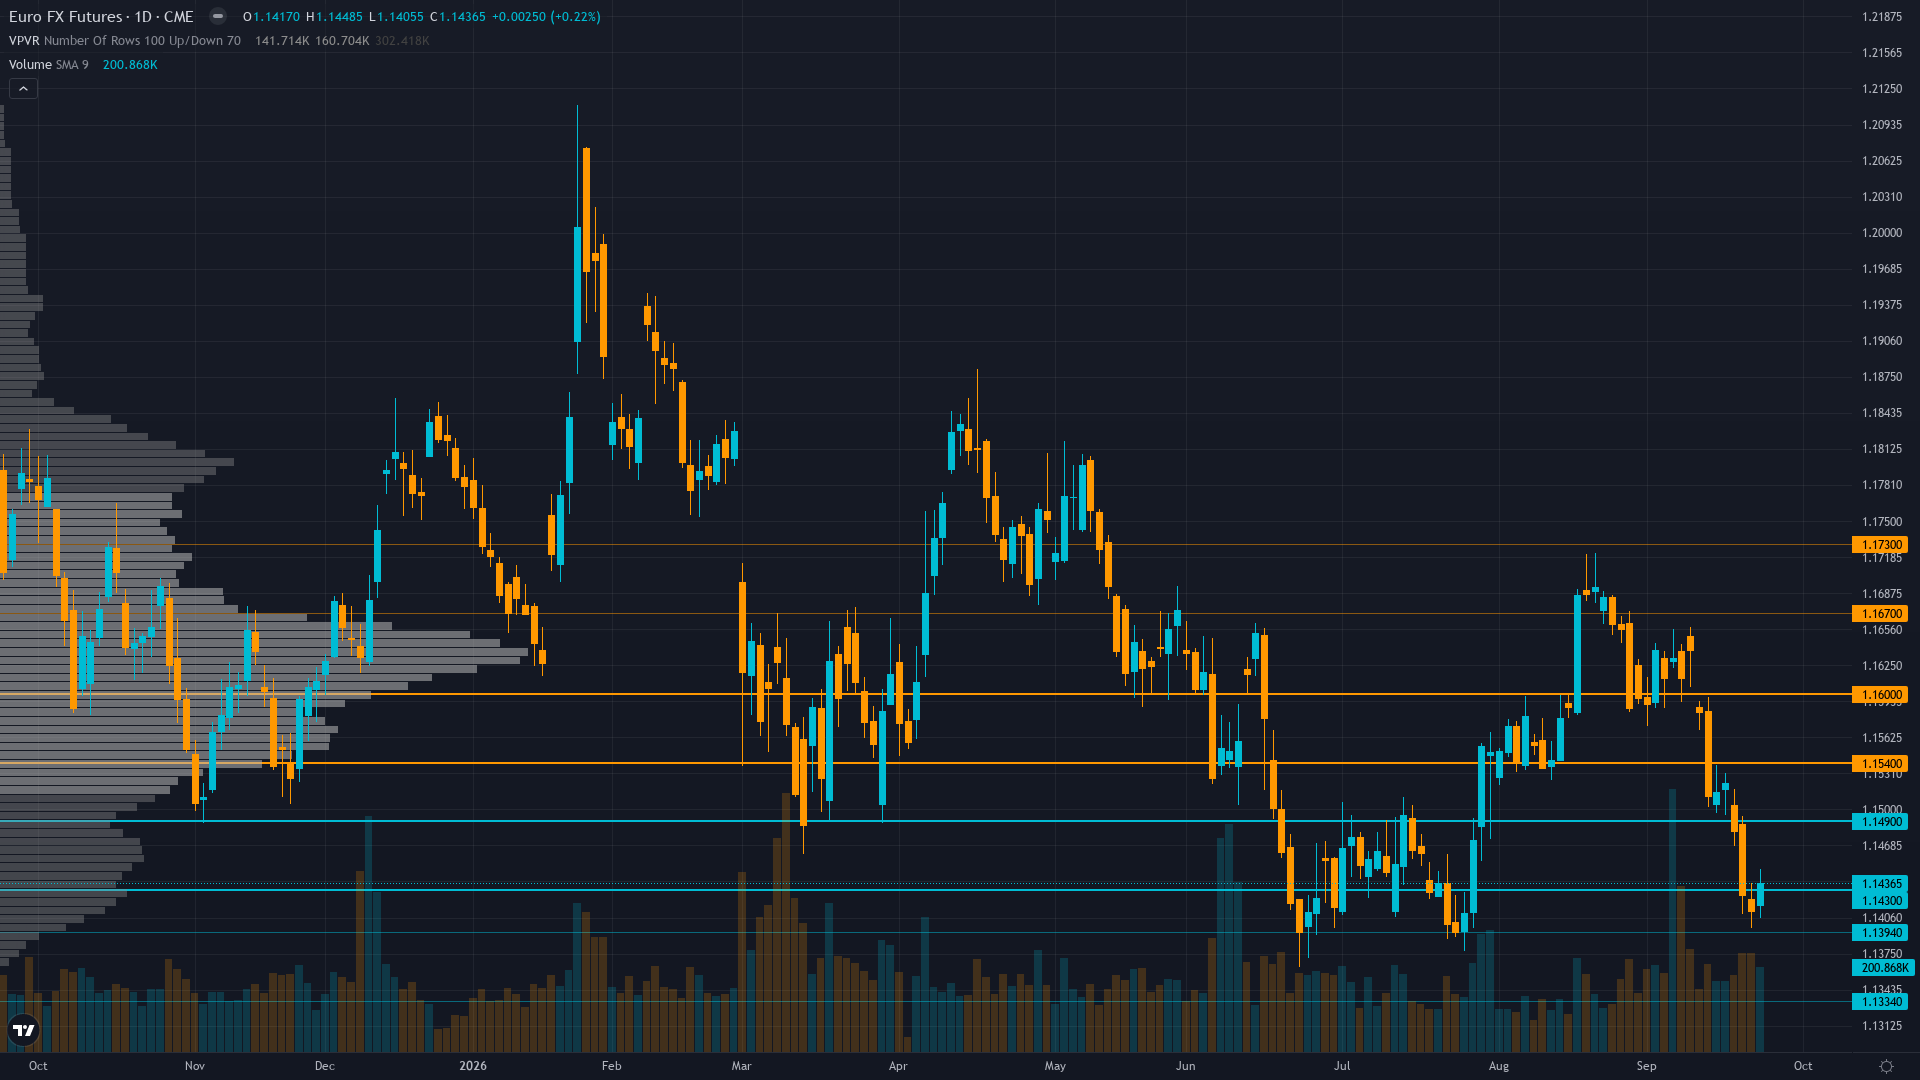
This week's EUR/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
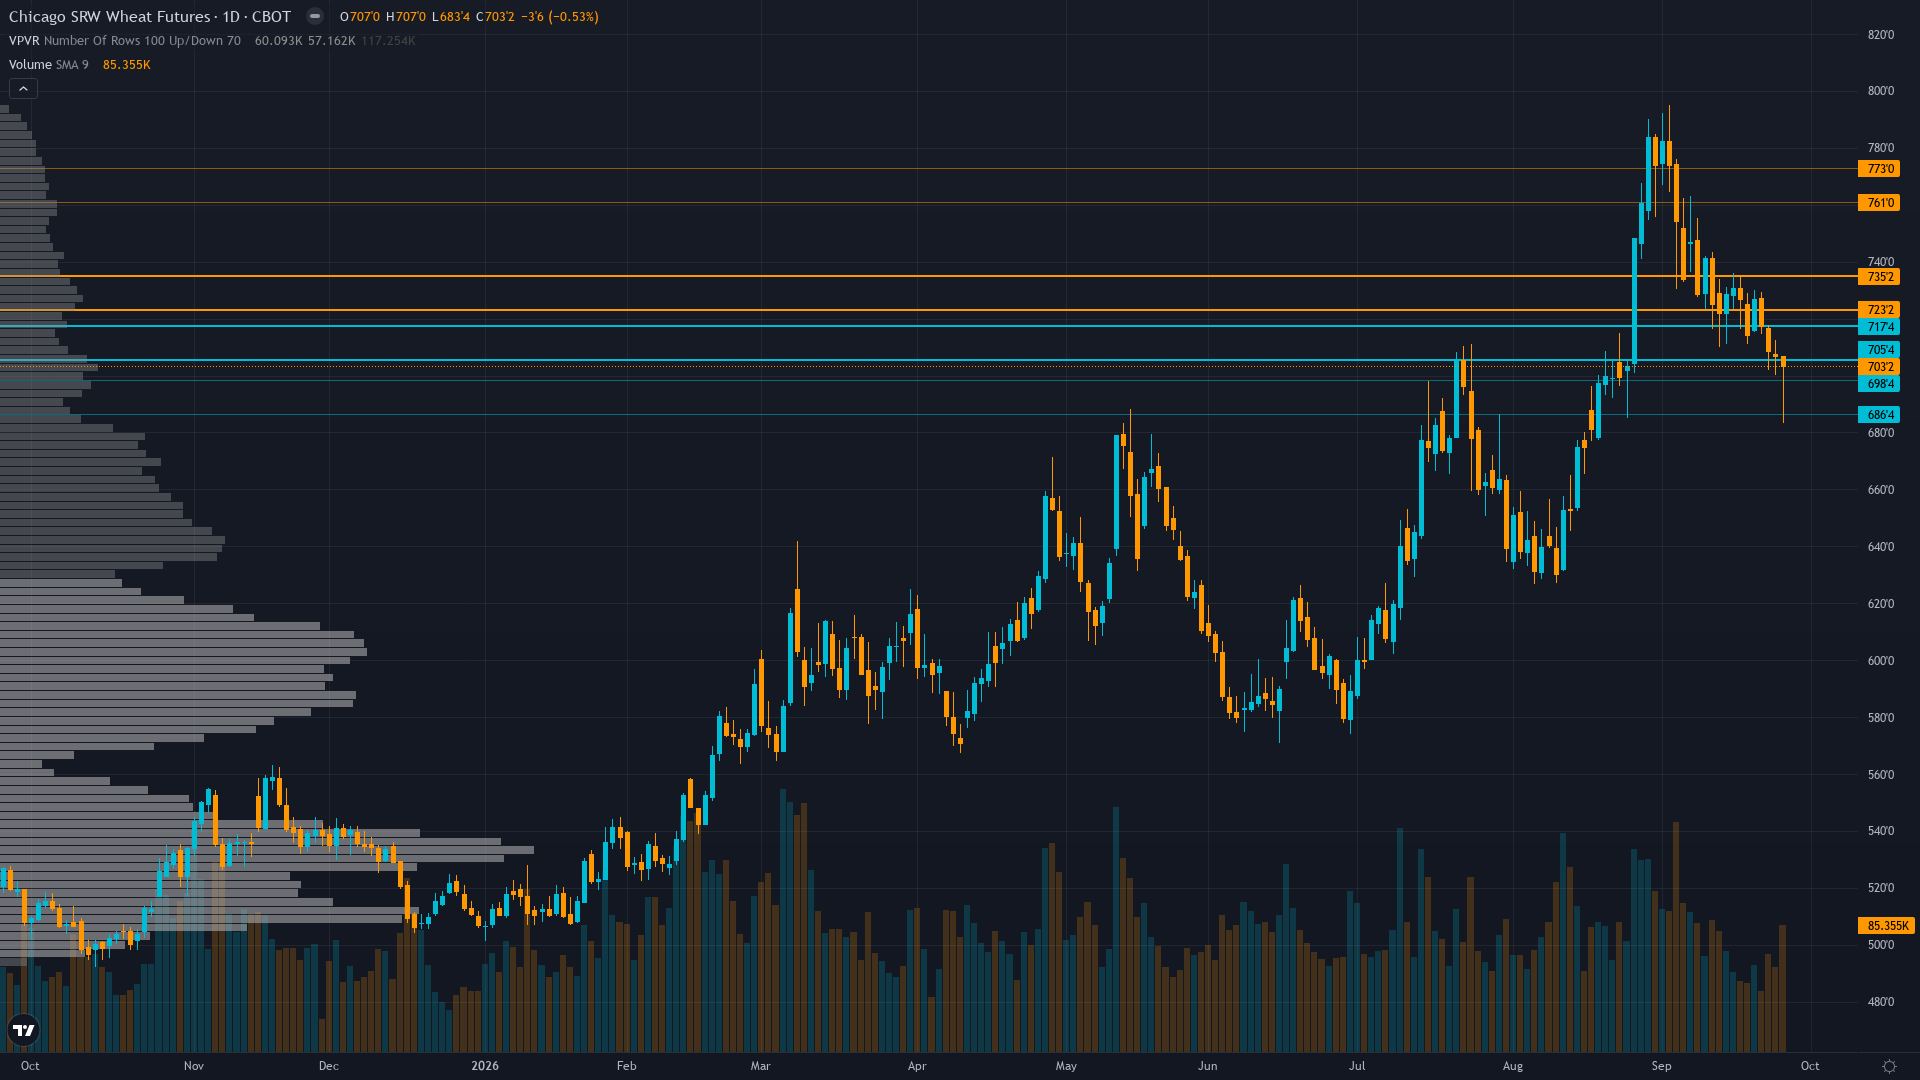
Wheat institutional positioning: COT data, sentiment analysis and smart money flow assessment.
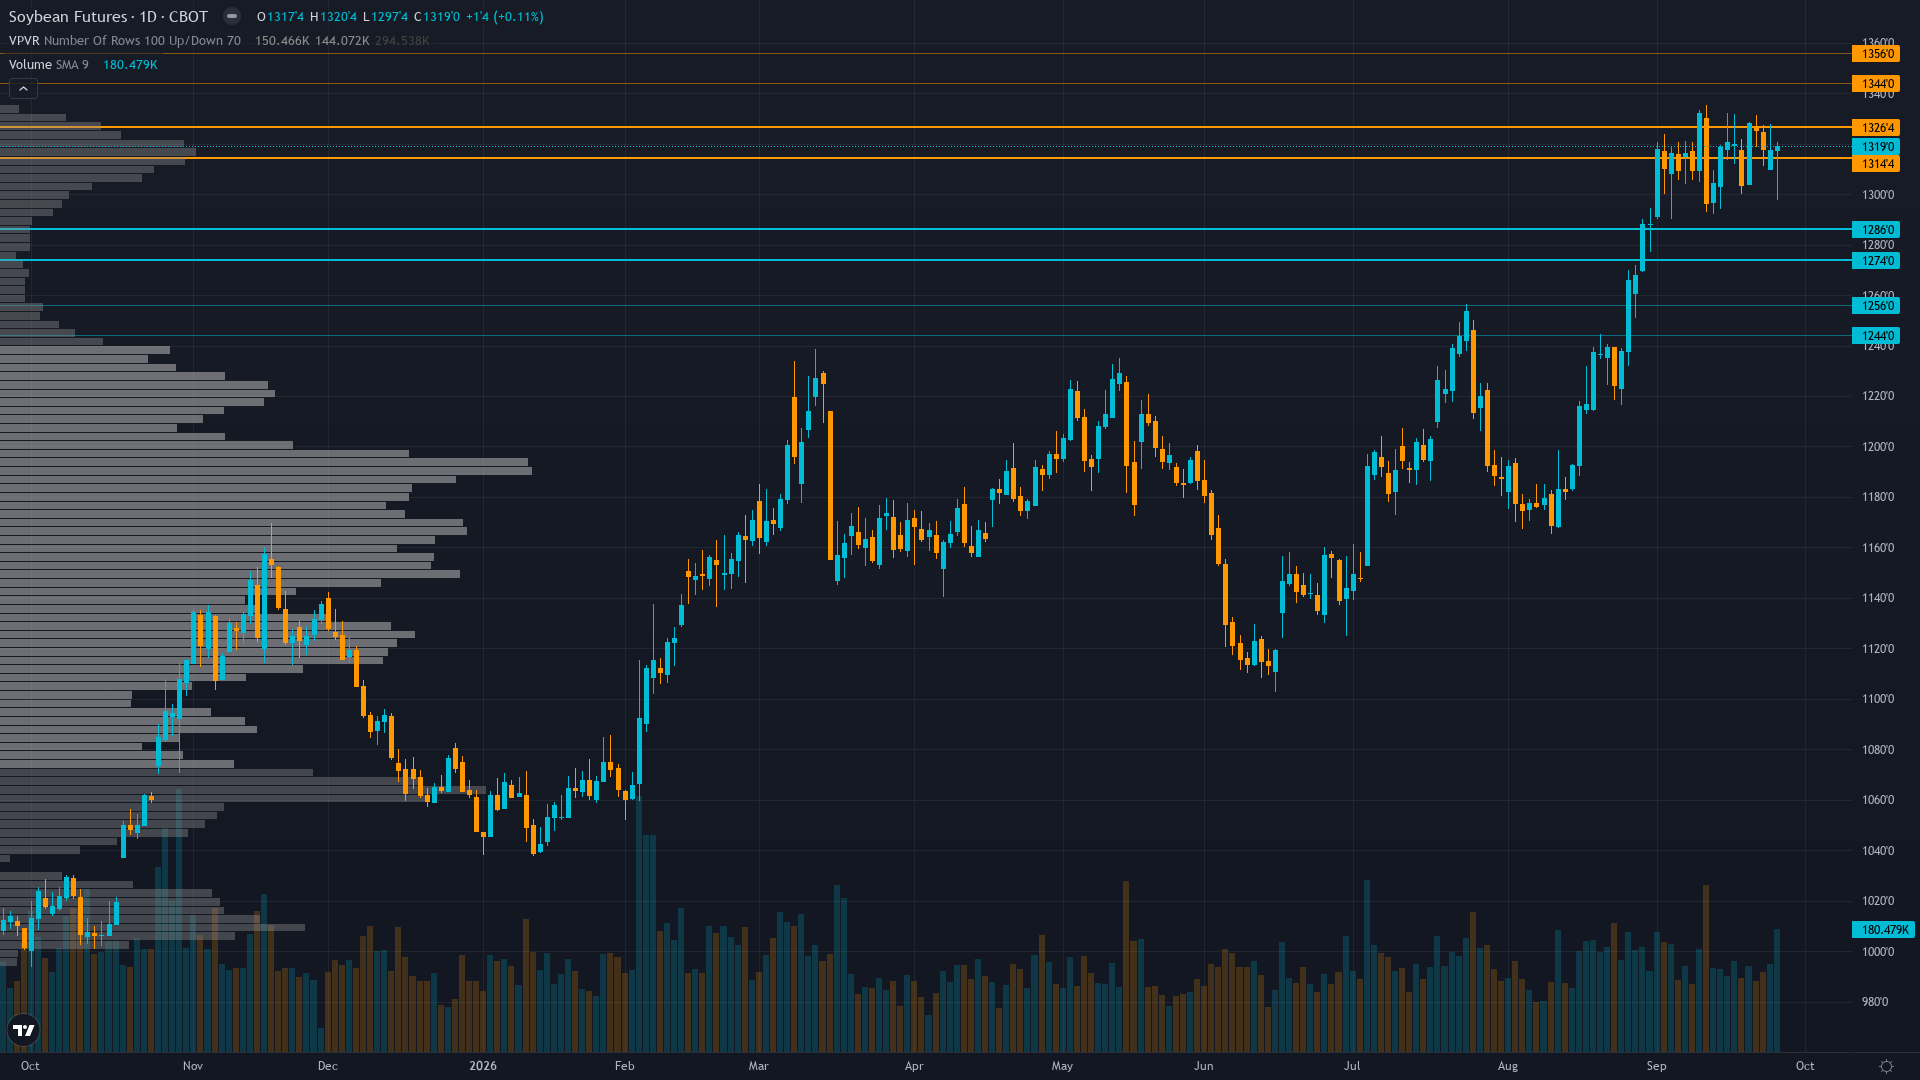
Soybeans key levels breakdown: support zones, resistance zones, confluence and price structure.
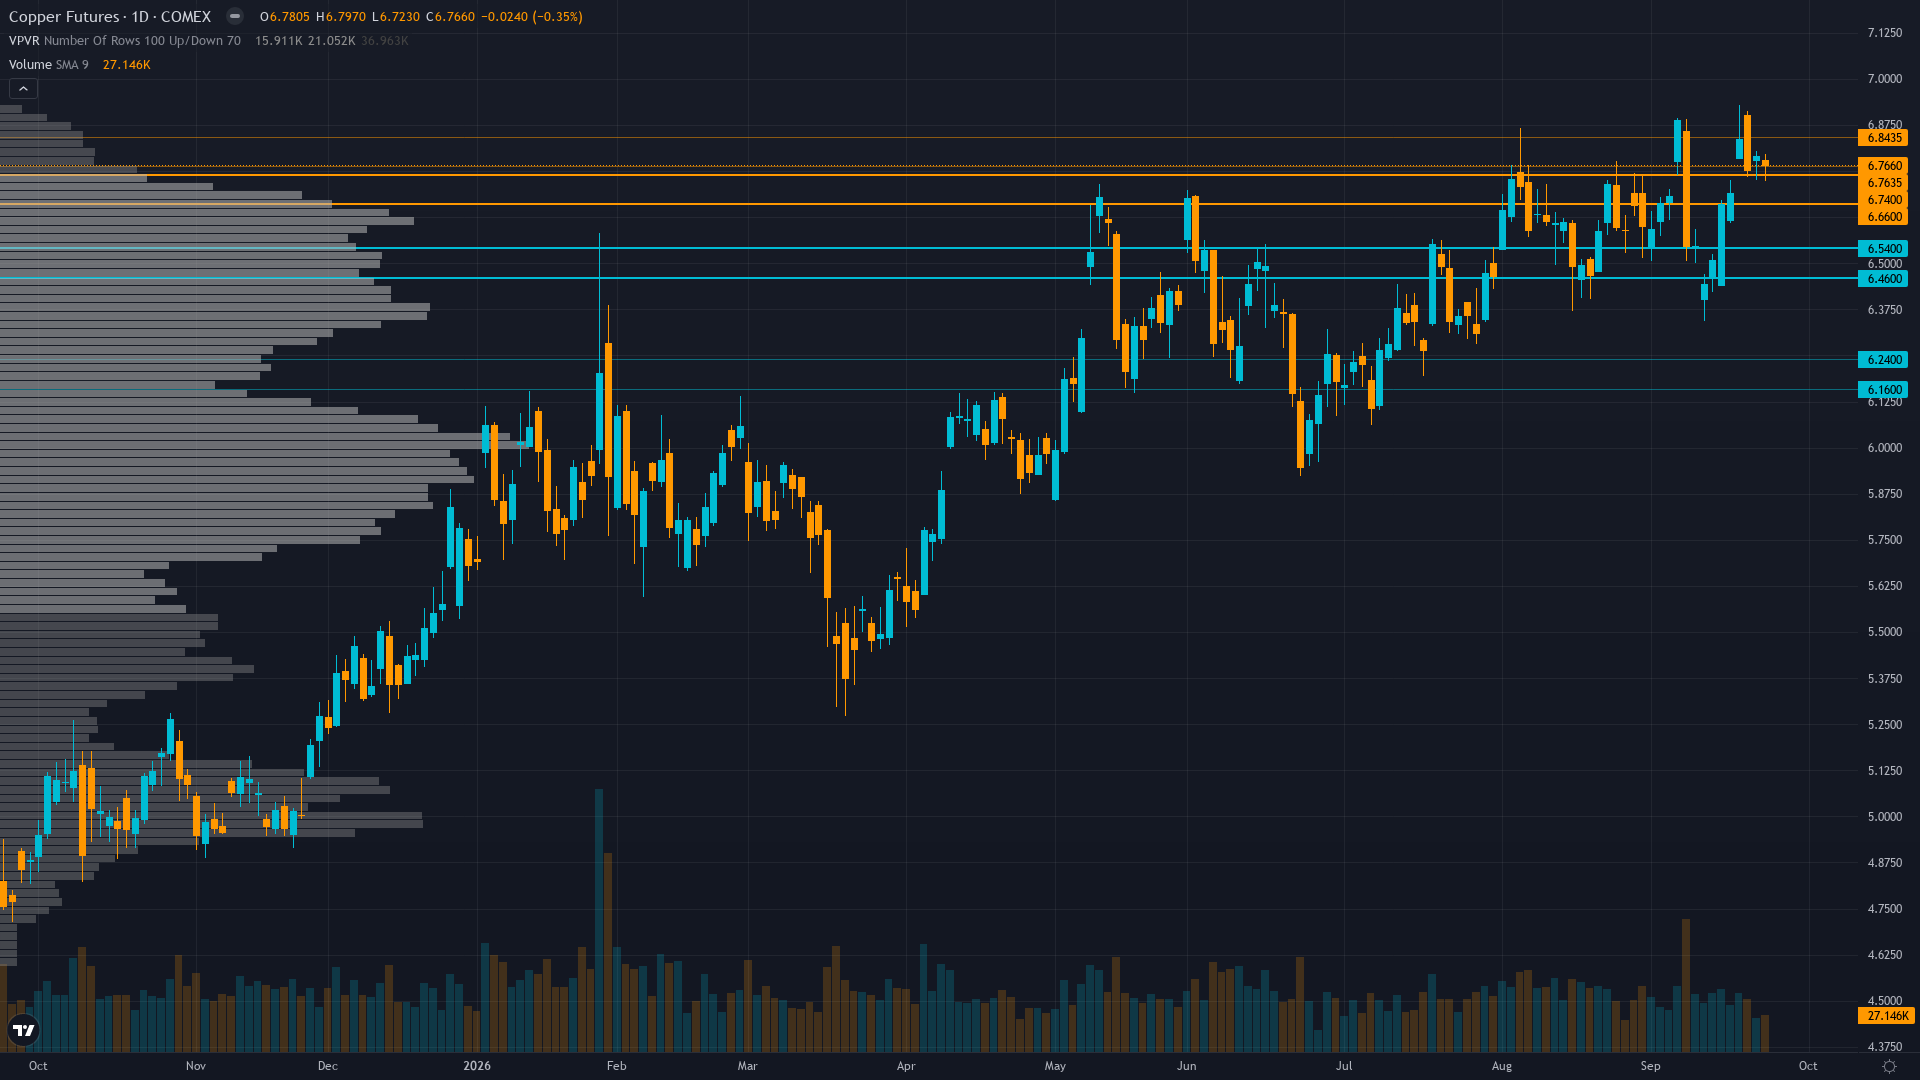
Copper institutional positioning: COT data, sentiment analysis and smart money flow assessment.
Wheat key levels breakdown: support zones, resistance zones, confluence and price structure.
AUD/USD institutional positioning: COT data, sentiment analysis and smart money flow assessment.

Full Desk
Market in prolonged low-volatility consolidation between $1,705 and $1,840 after absorbing the September 16 FOMC rate hike and WPIC surplus revision from 297koz deficit to 265koz surplus, with no clear directional catalyst ahead of the November 18 WPIC Quarterly report
Full Desk
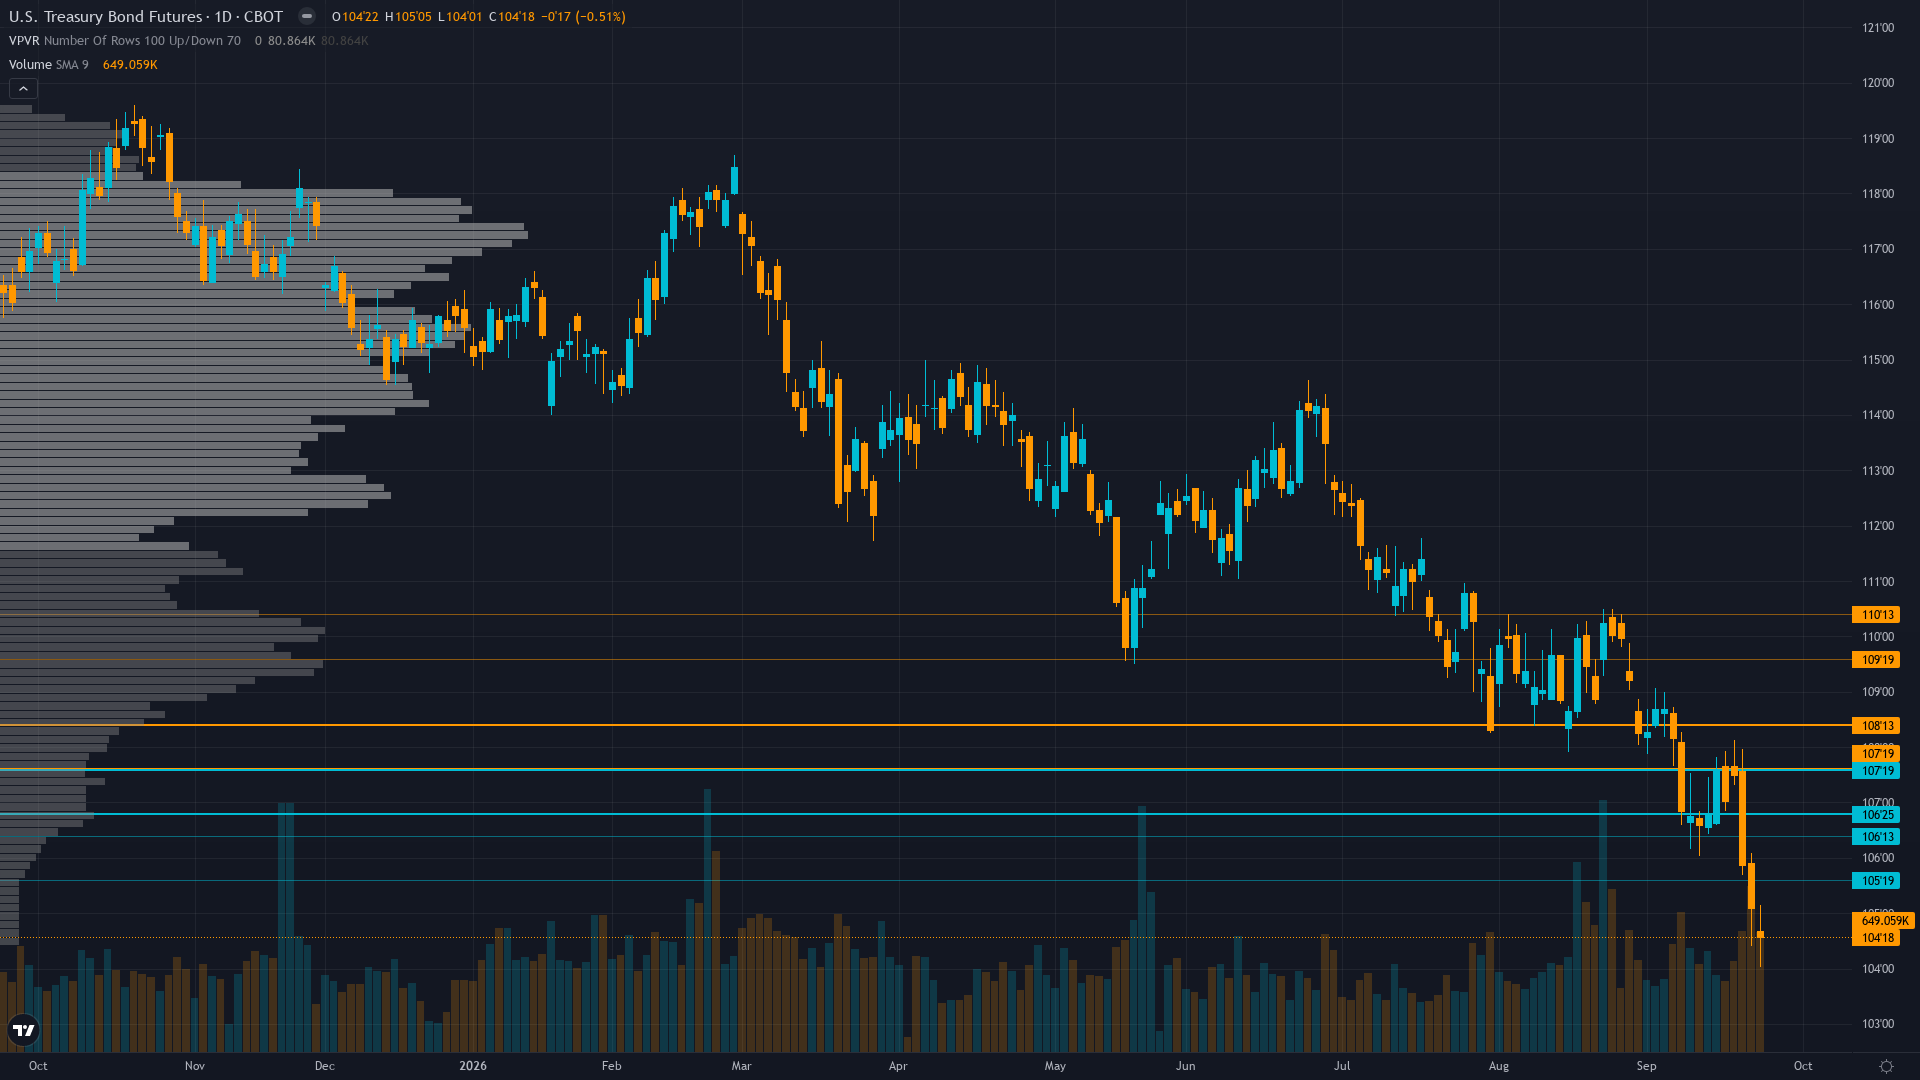
Market pricing structural bearish duration environment with 30Y at 5.49-5.50% (2004 highs); ZB crashing to 52-week low after -2.79% weekly collapse accelerated by hawkish Fed repricing pricing 65-71% probability of October 25bp hike; MOVE Index spiking 30% to 104 confirming bond market panic; Bessen
Weekly Review
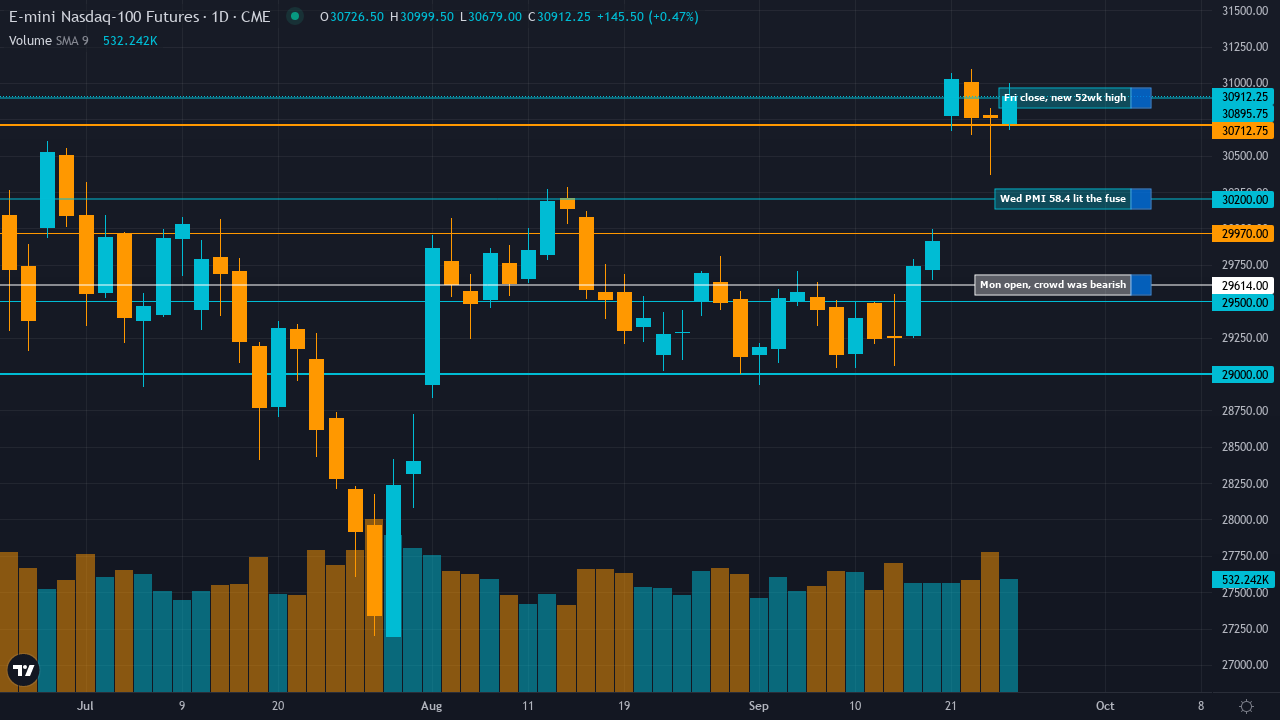
The Nasdaq rips 4.3% on PMI fireworks, the desk goes four from five, and ten NO CALLs watch bonds implode and gold bleed out.
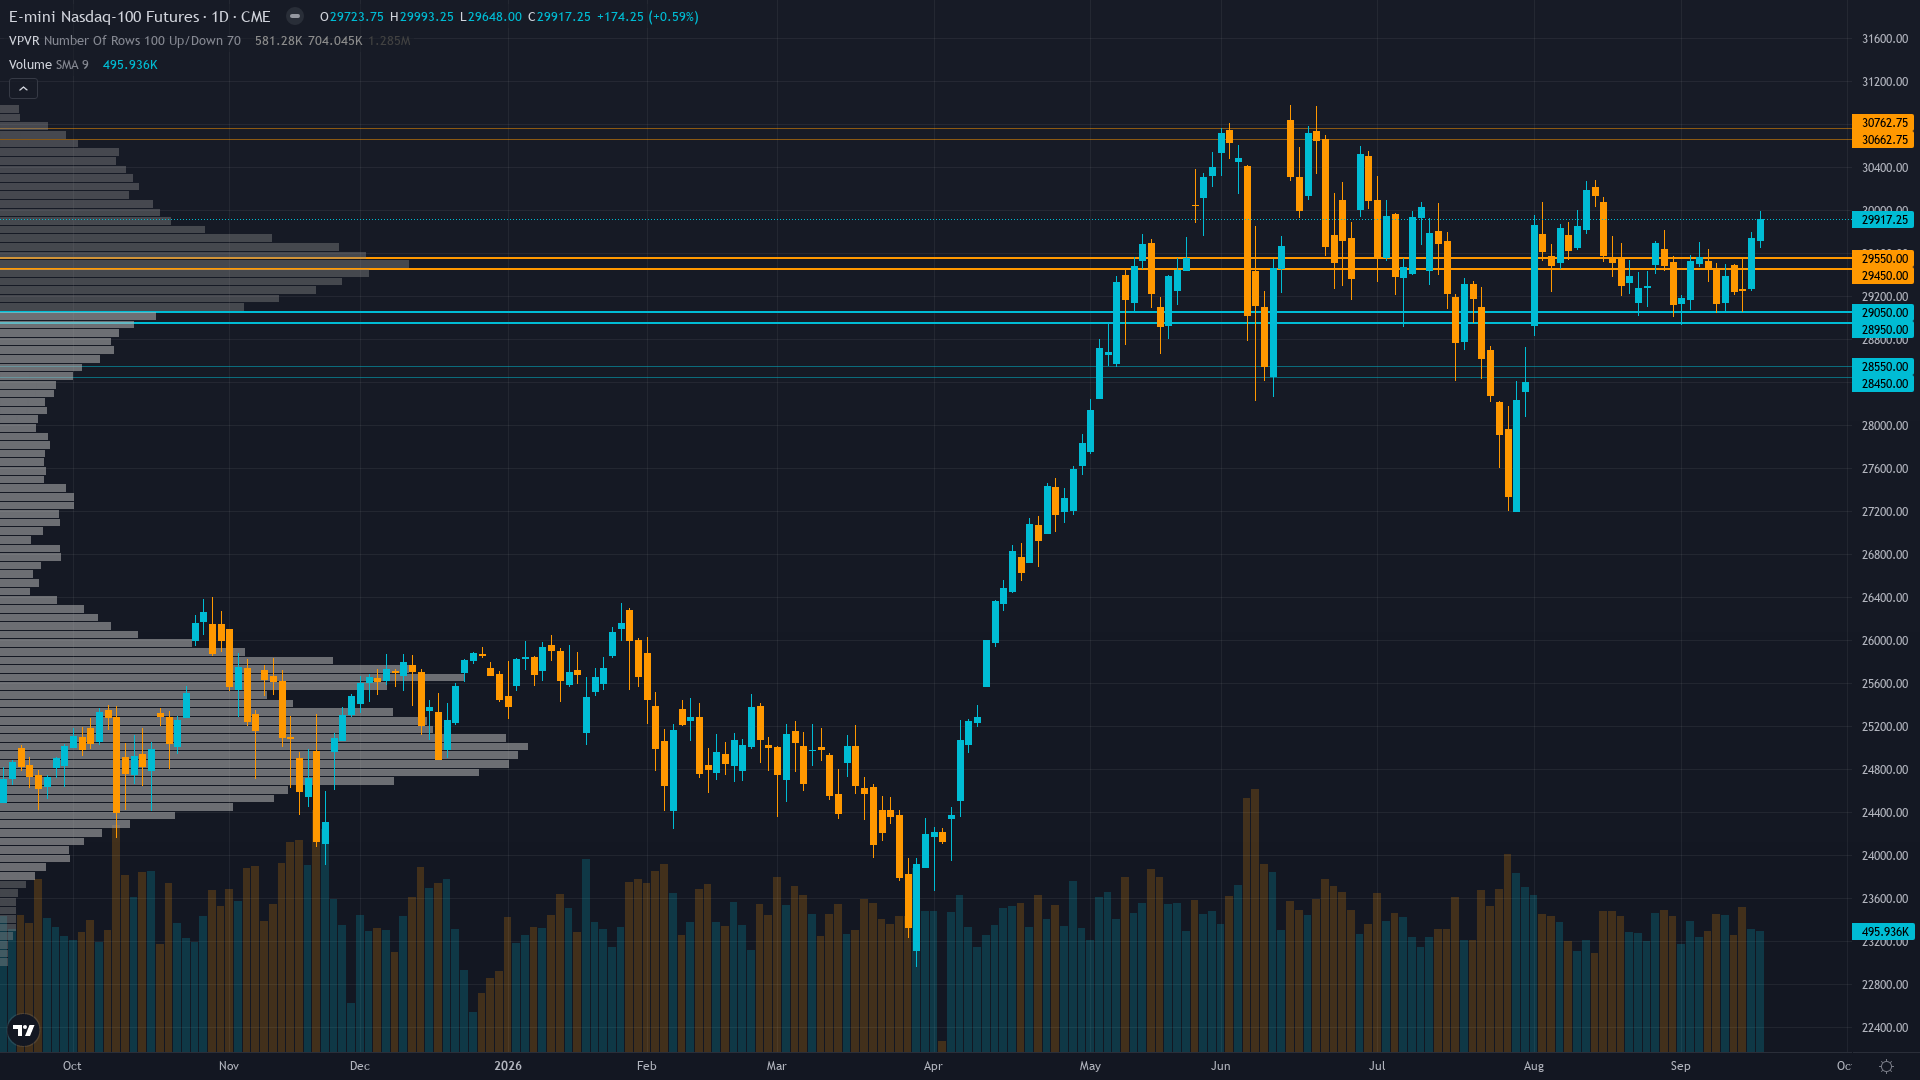
Nasdaq 100 (NQ): The market may be overweighting September seasonal anxiety and the 10Y yield above 5% as structural headwinds while underweighting the dramatic institutional positioning shift (COT net longs +61% weekly to 83.5th percentile) and the extreme retail bearishness (-24.5% AAII spread) th
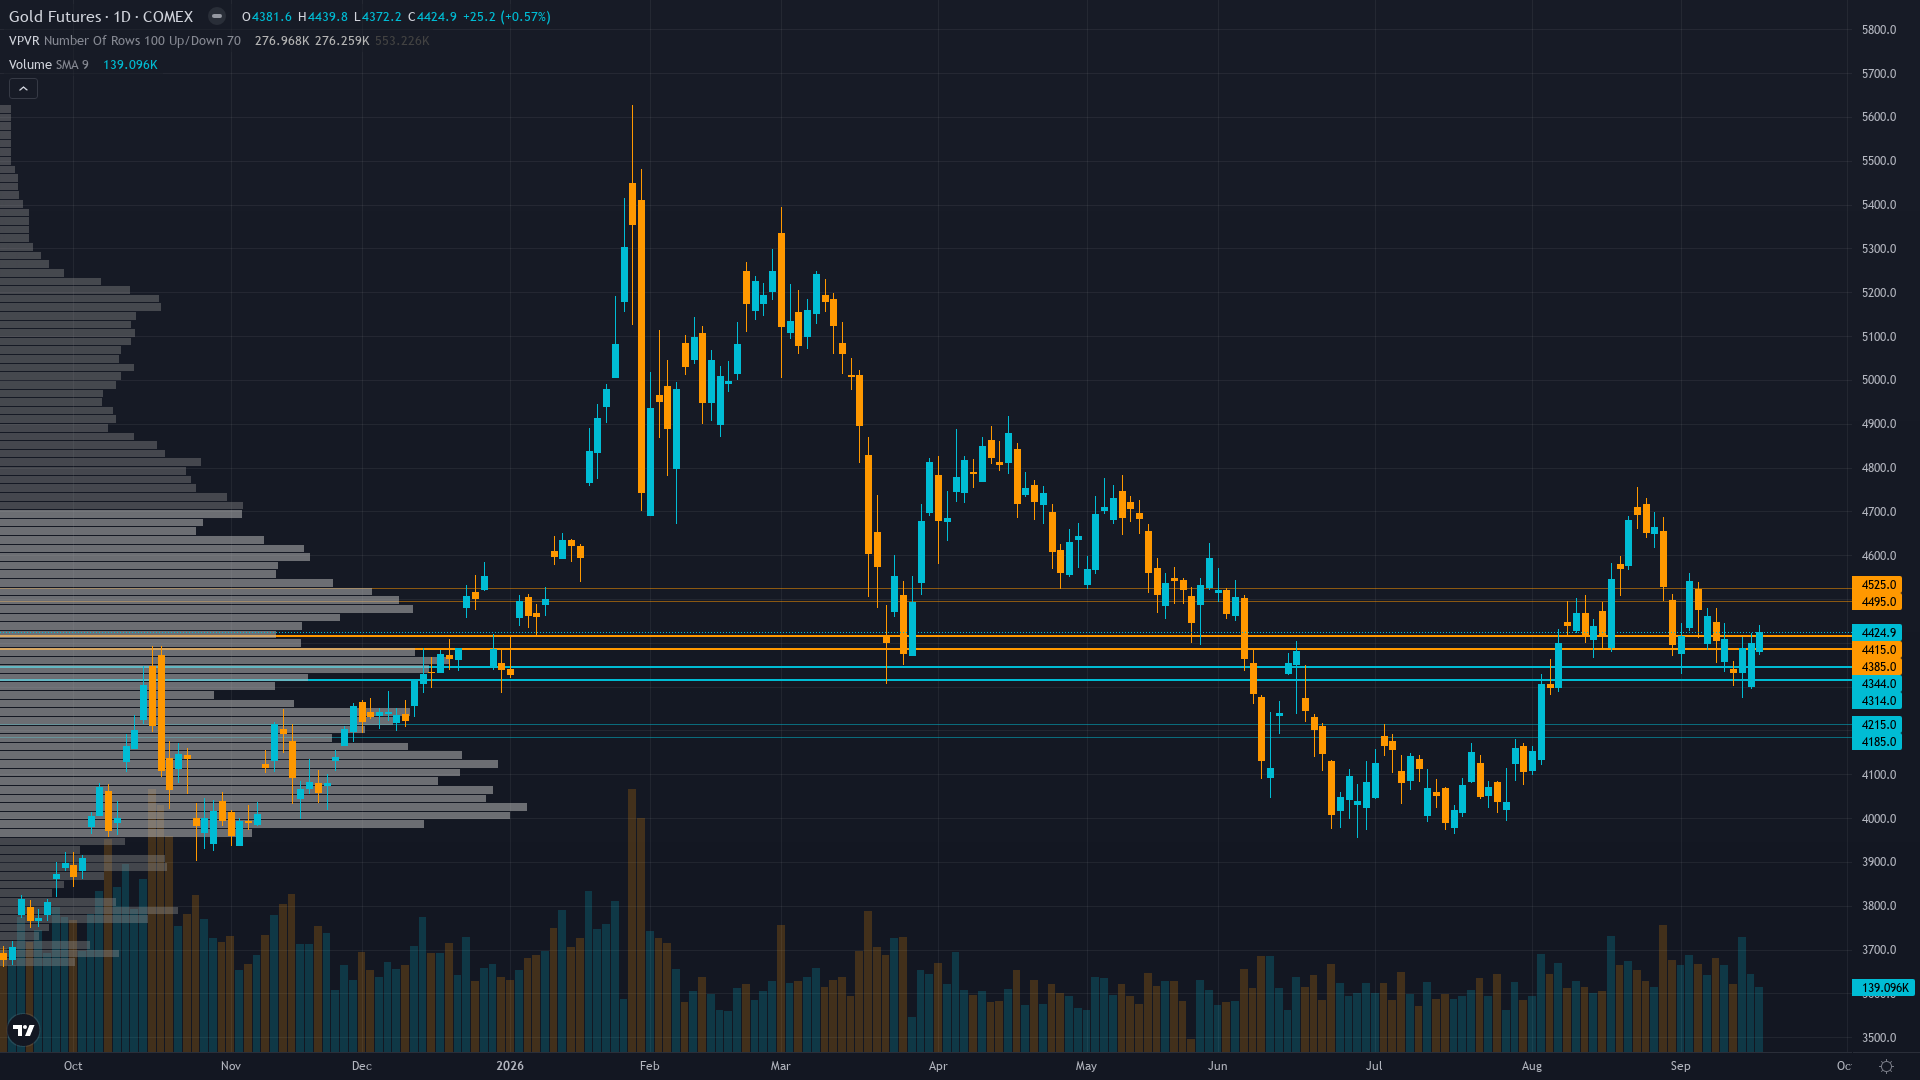
Core
Split between structural bulls (central bank buying, seasonality, institutional year-end targets $4,500-$6,000) and tactical bears (hawkish Fed, 5%+ yields, technical downtrend below 200-day MA) — with no clear prevailing direction after gold rallied through the Sep 16 rate hike
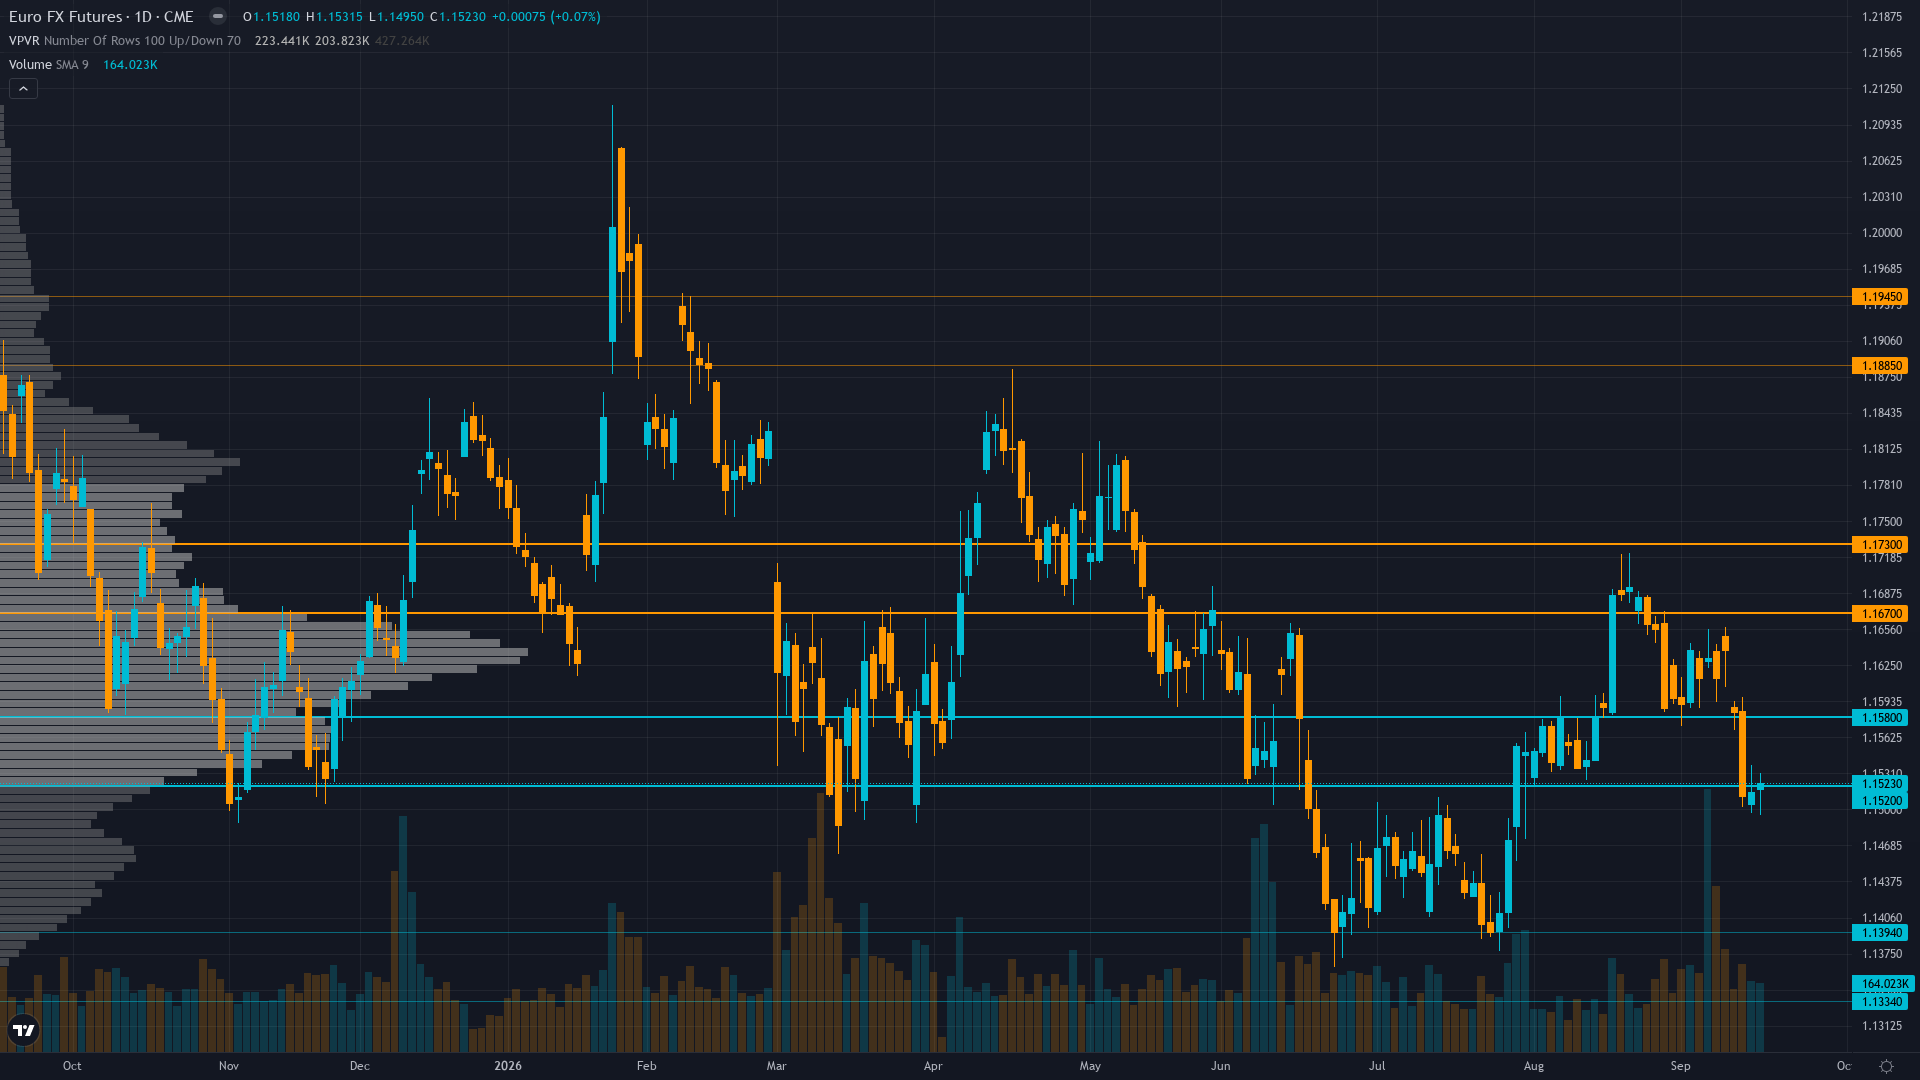
Core
EUR/USD grinding lower toward 1.1460-1.1364 support as Fed-ECB rate differential widens and Eurozone PMIs expected to show contraction — institutional bank year-end targets of 1.20-1.25 remain conditional on a Fed pivot that appears distant with US 10Y at 5.01%
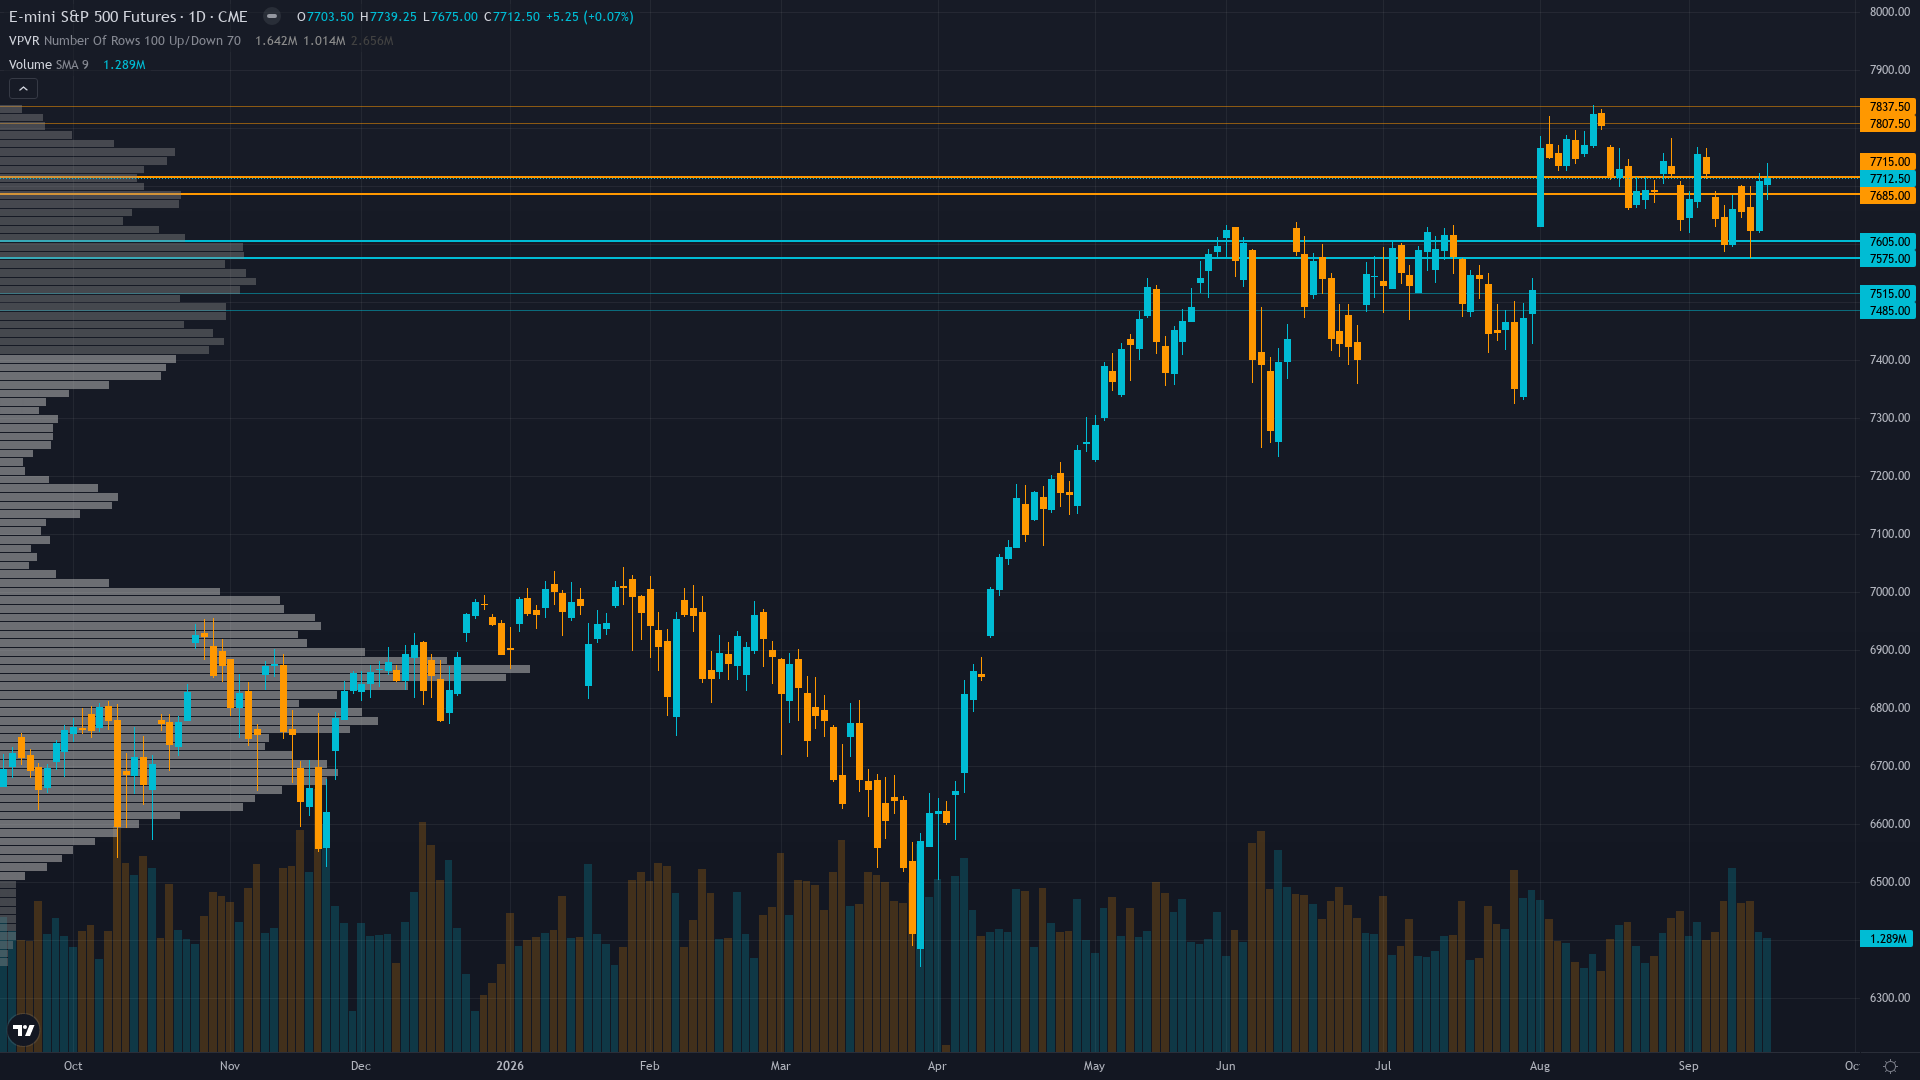
Core
Cautiously neutral as S&P 500 holds near 7,650 despite 5% 10-year yields and extreme breadth contraction, with market awaiting PMI data and Fed guidance this week for directional catalyst
Core
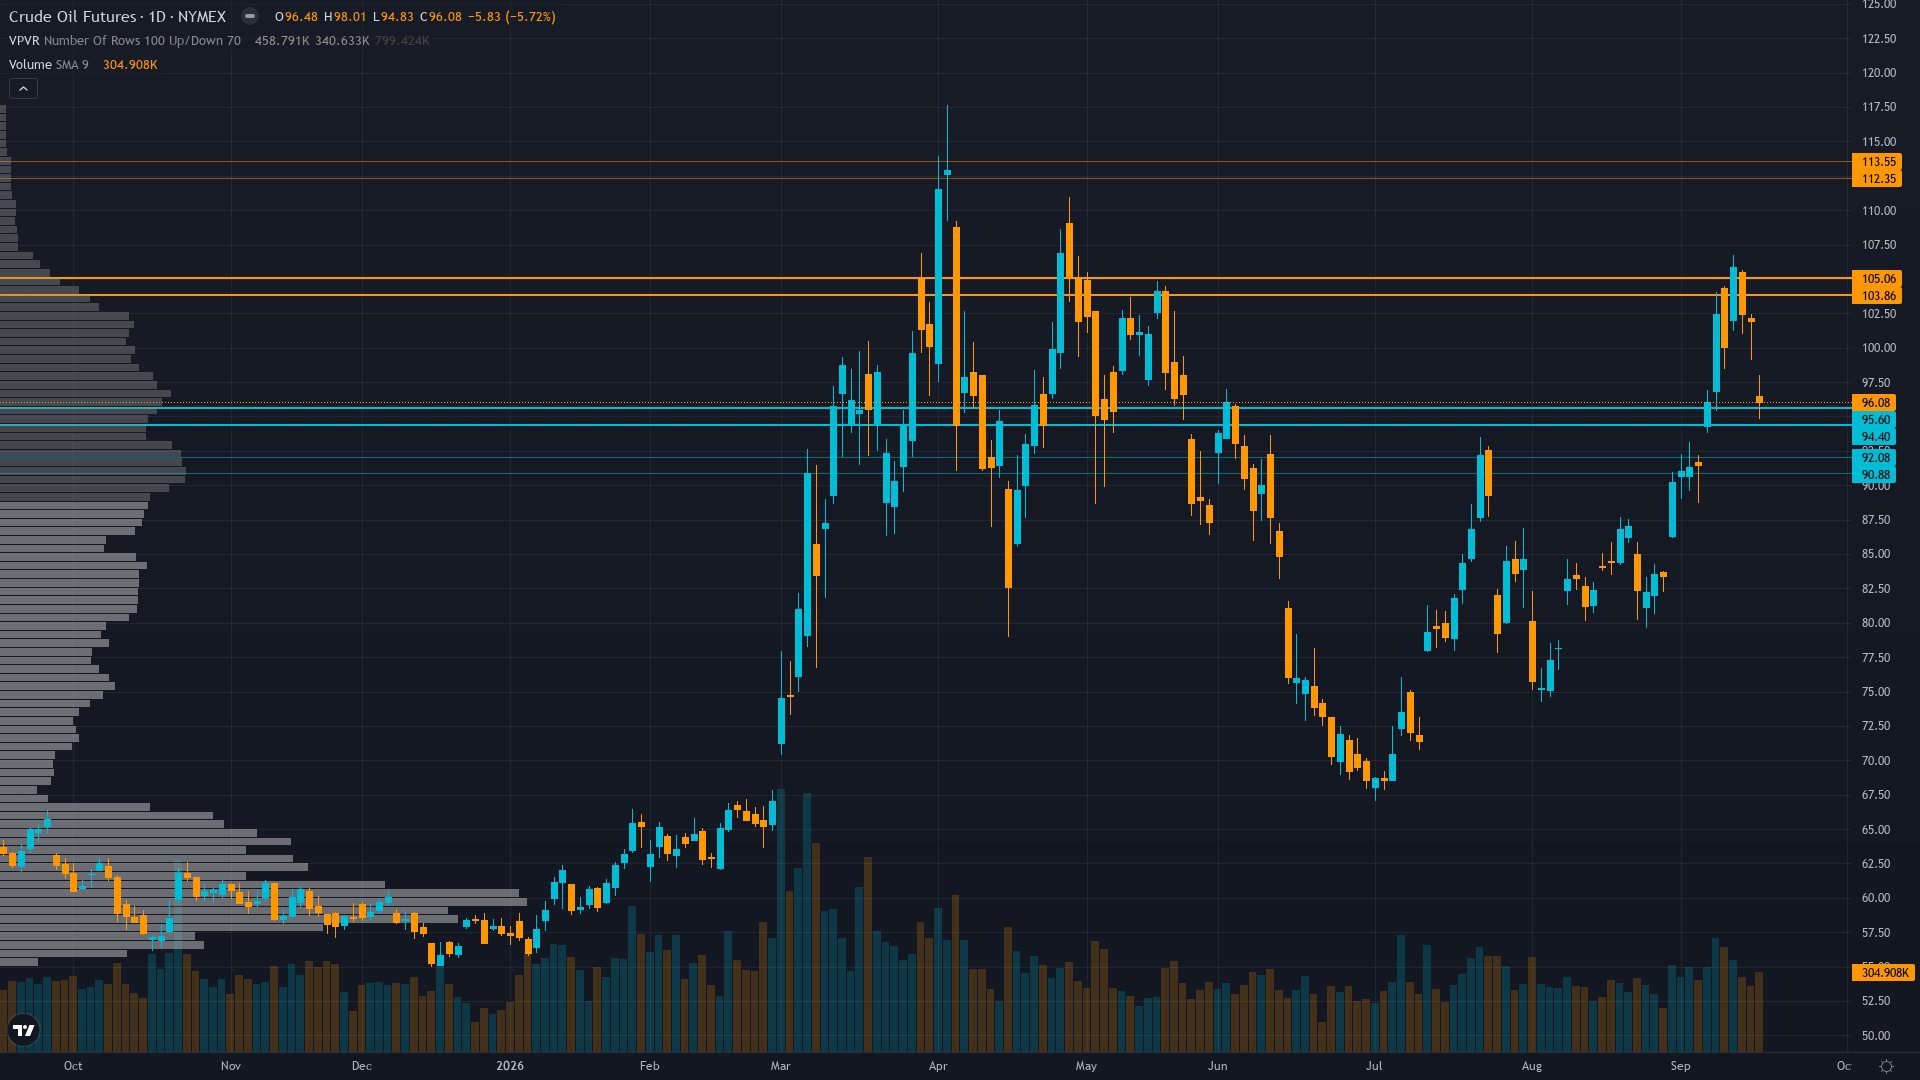
Market divided and uncertain — Polymarket shows 100% probability of WTI below $95 for September settlement, but the binary risk of Hormuz peace vs renewed escalation keeps conviction thin; the -4.64% weekly decline reflects market pricing in the first credible de-escalation signal since June
Extended
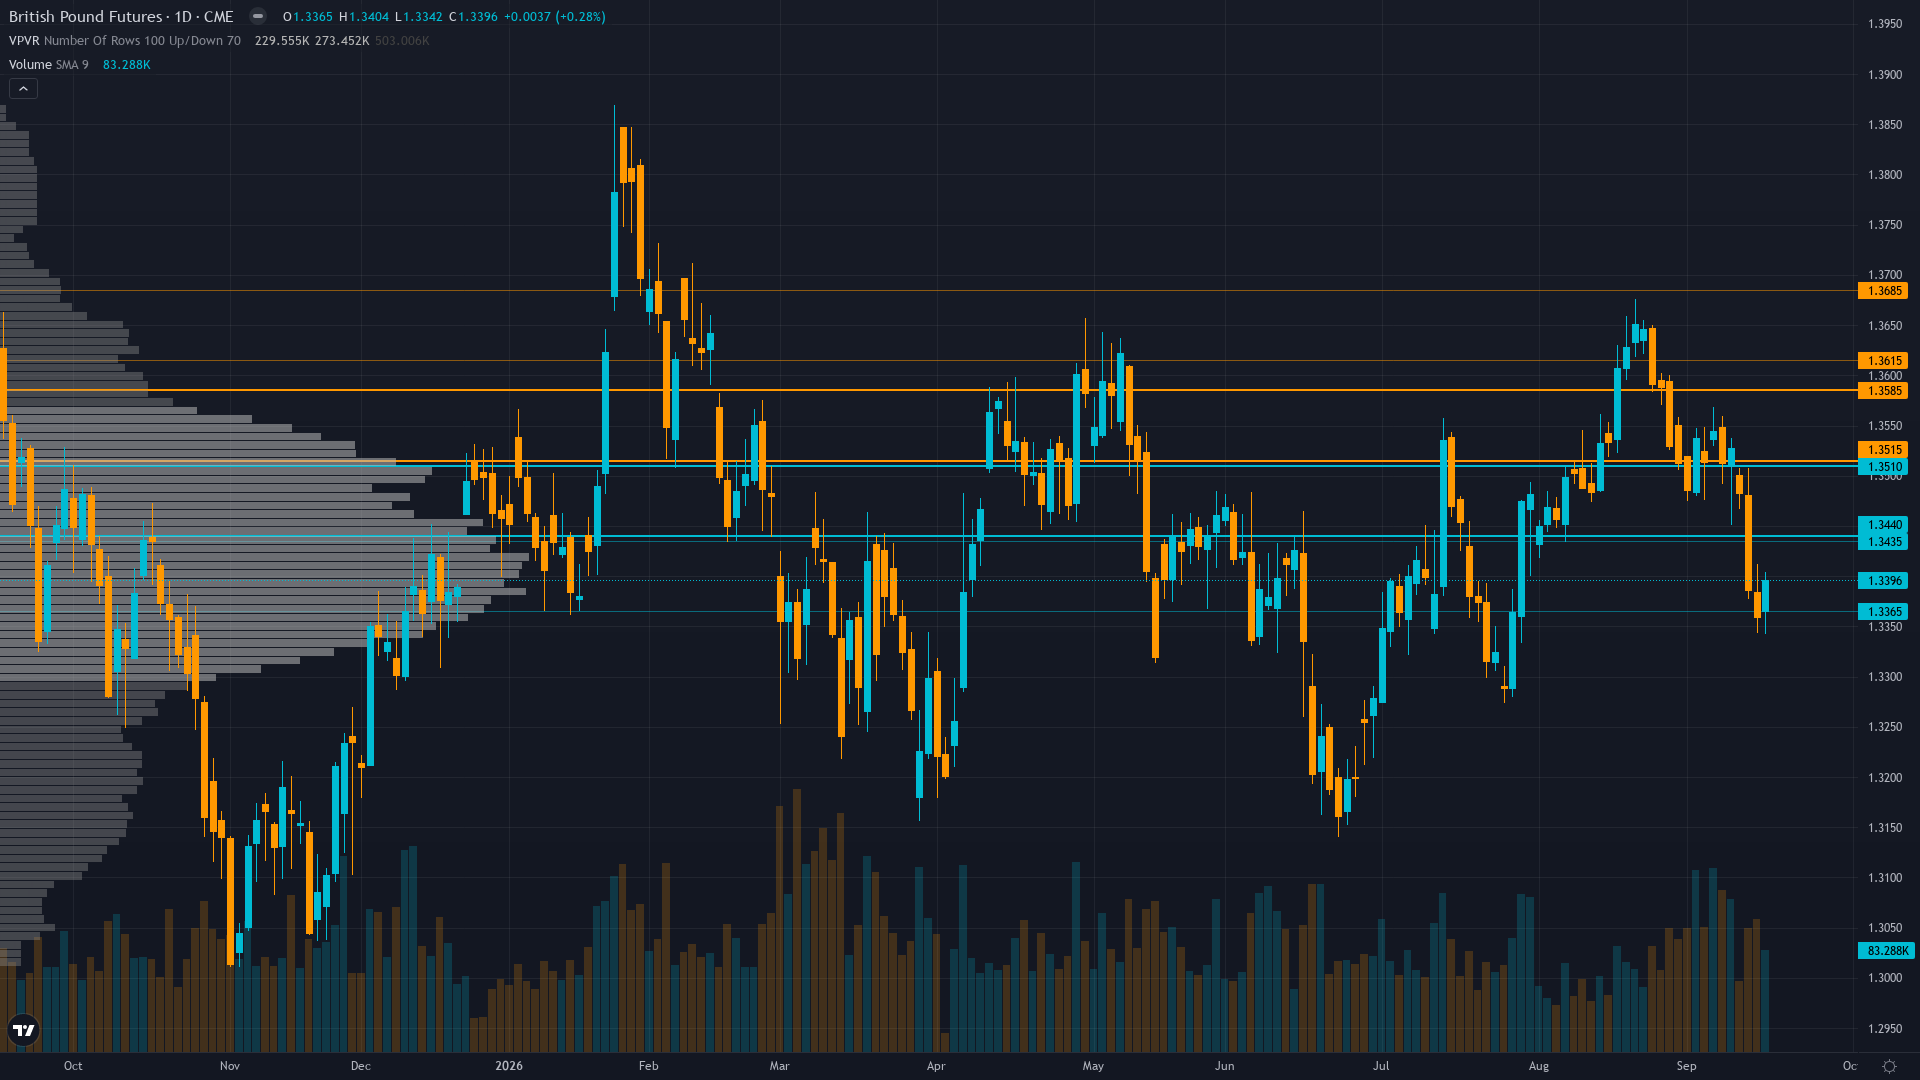
GBP at 1.3392 near two-month lows below $1.34 following BoE Sep 17 hold at 3.75% (6-3 vote), with mixed discipline signals preventing conviction ahead of UK PMI data, BoE Bailey speech, and US Durable Goods in the week ahead
Extended
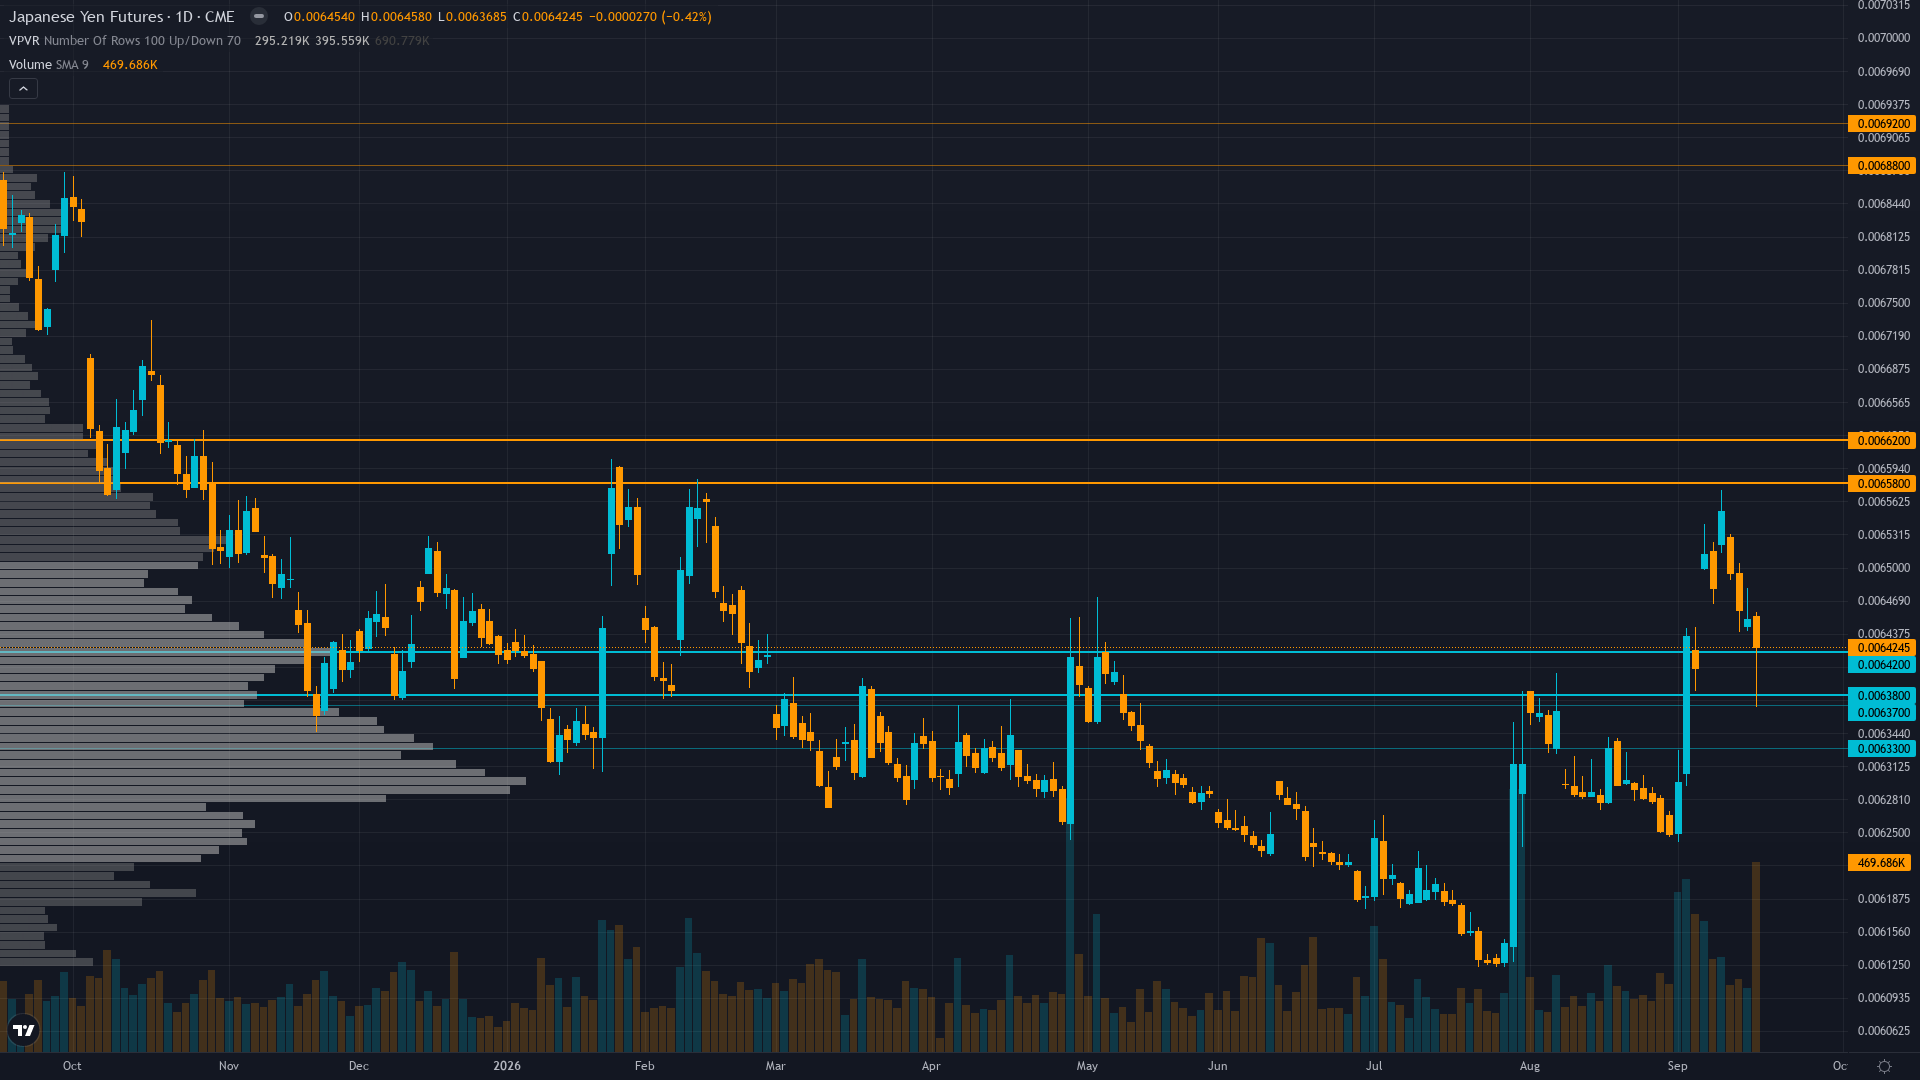
Market bearish JPY near-term after 'sell the fact' BOJ reversal with USD/JPY rising above 156.86; extreme speculative long positioning (+120K contracts, 88th percentile) vulnerable to further liquidation; consensus sees 155-158 range near-term with Japan PMI and US data as next catalysts
Extended
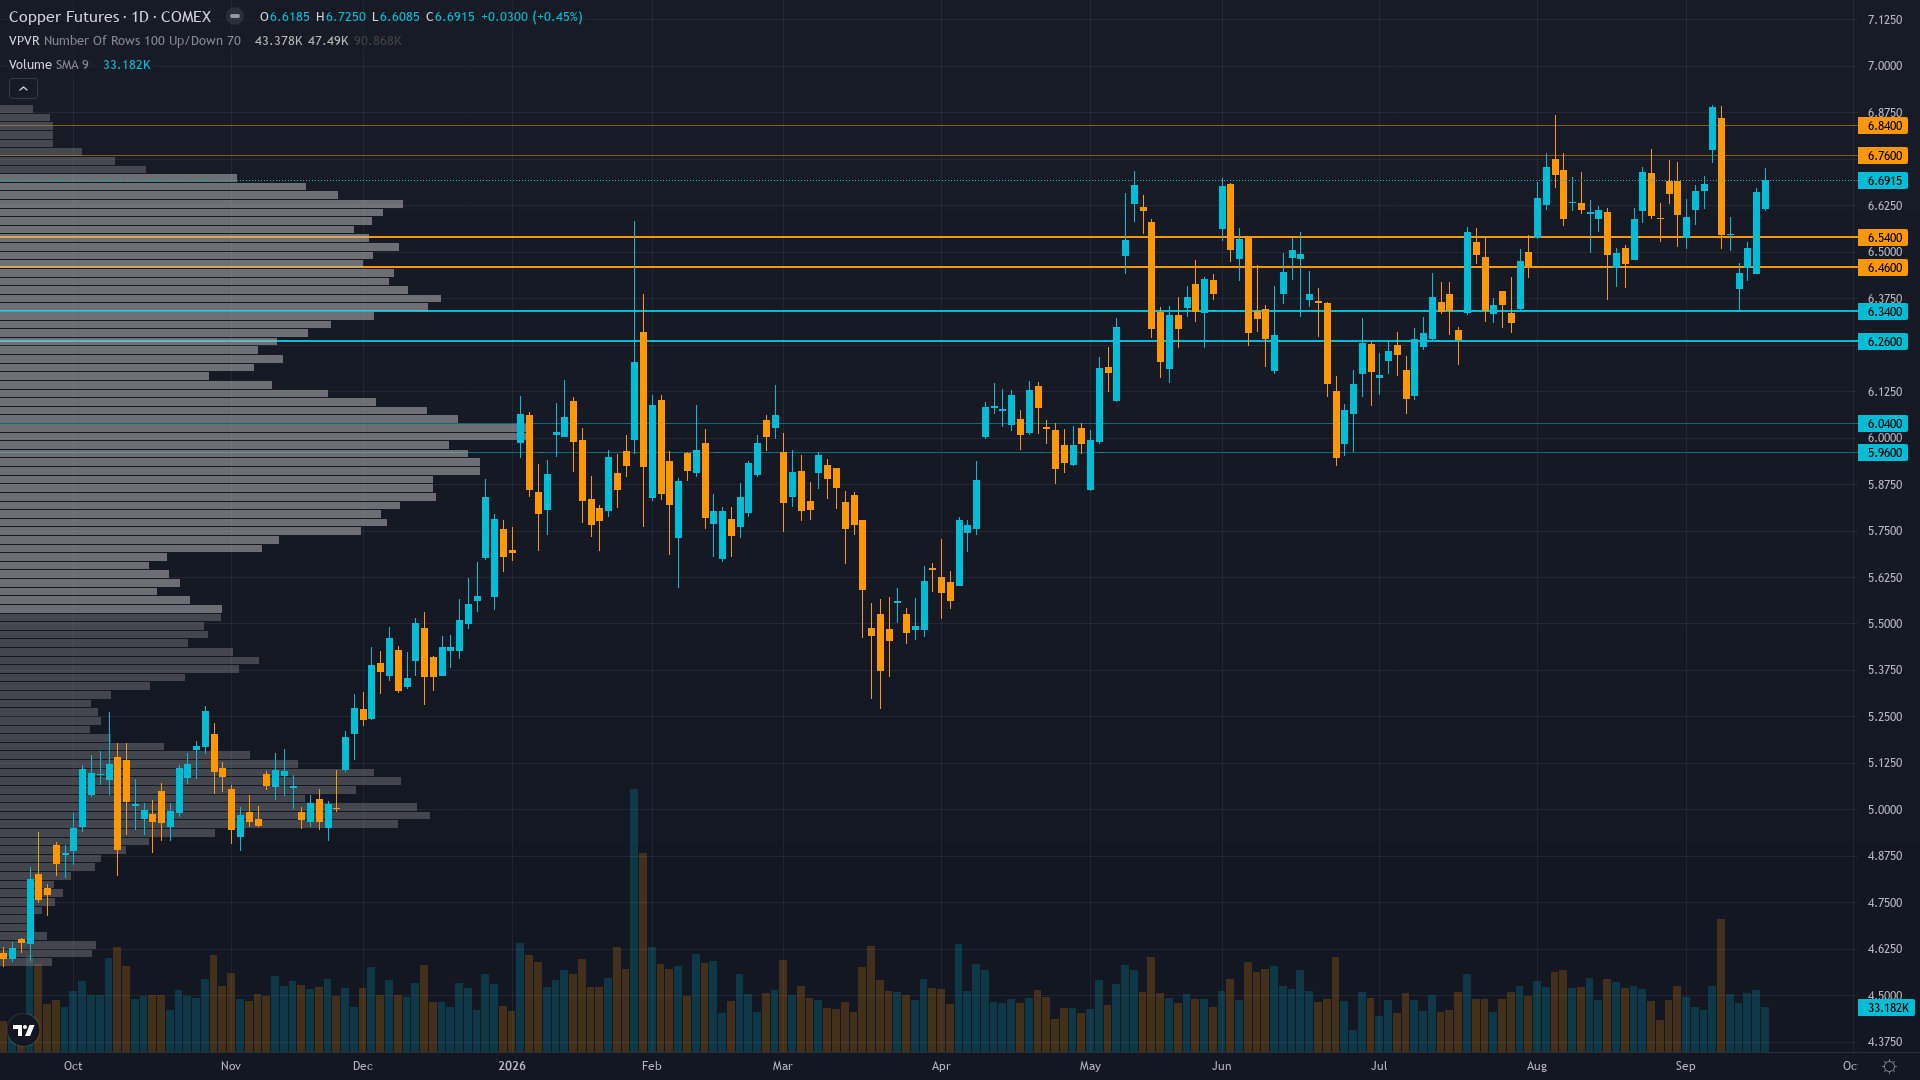
Copper trading near all-time nominal highs supported by structural supply deficit and El Niño production disruptions, but consolidating after the Fed's 25bp rate hike and tariff uncertainty with COT de-risking from extreme levels and LME stocks rising modestly
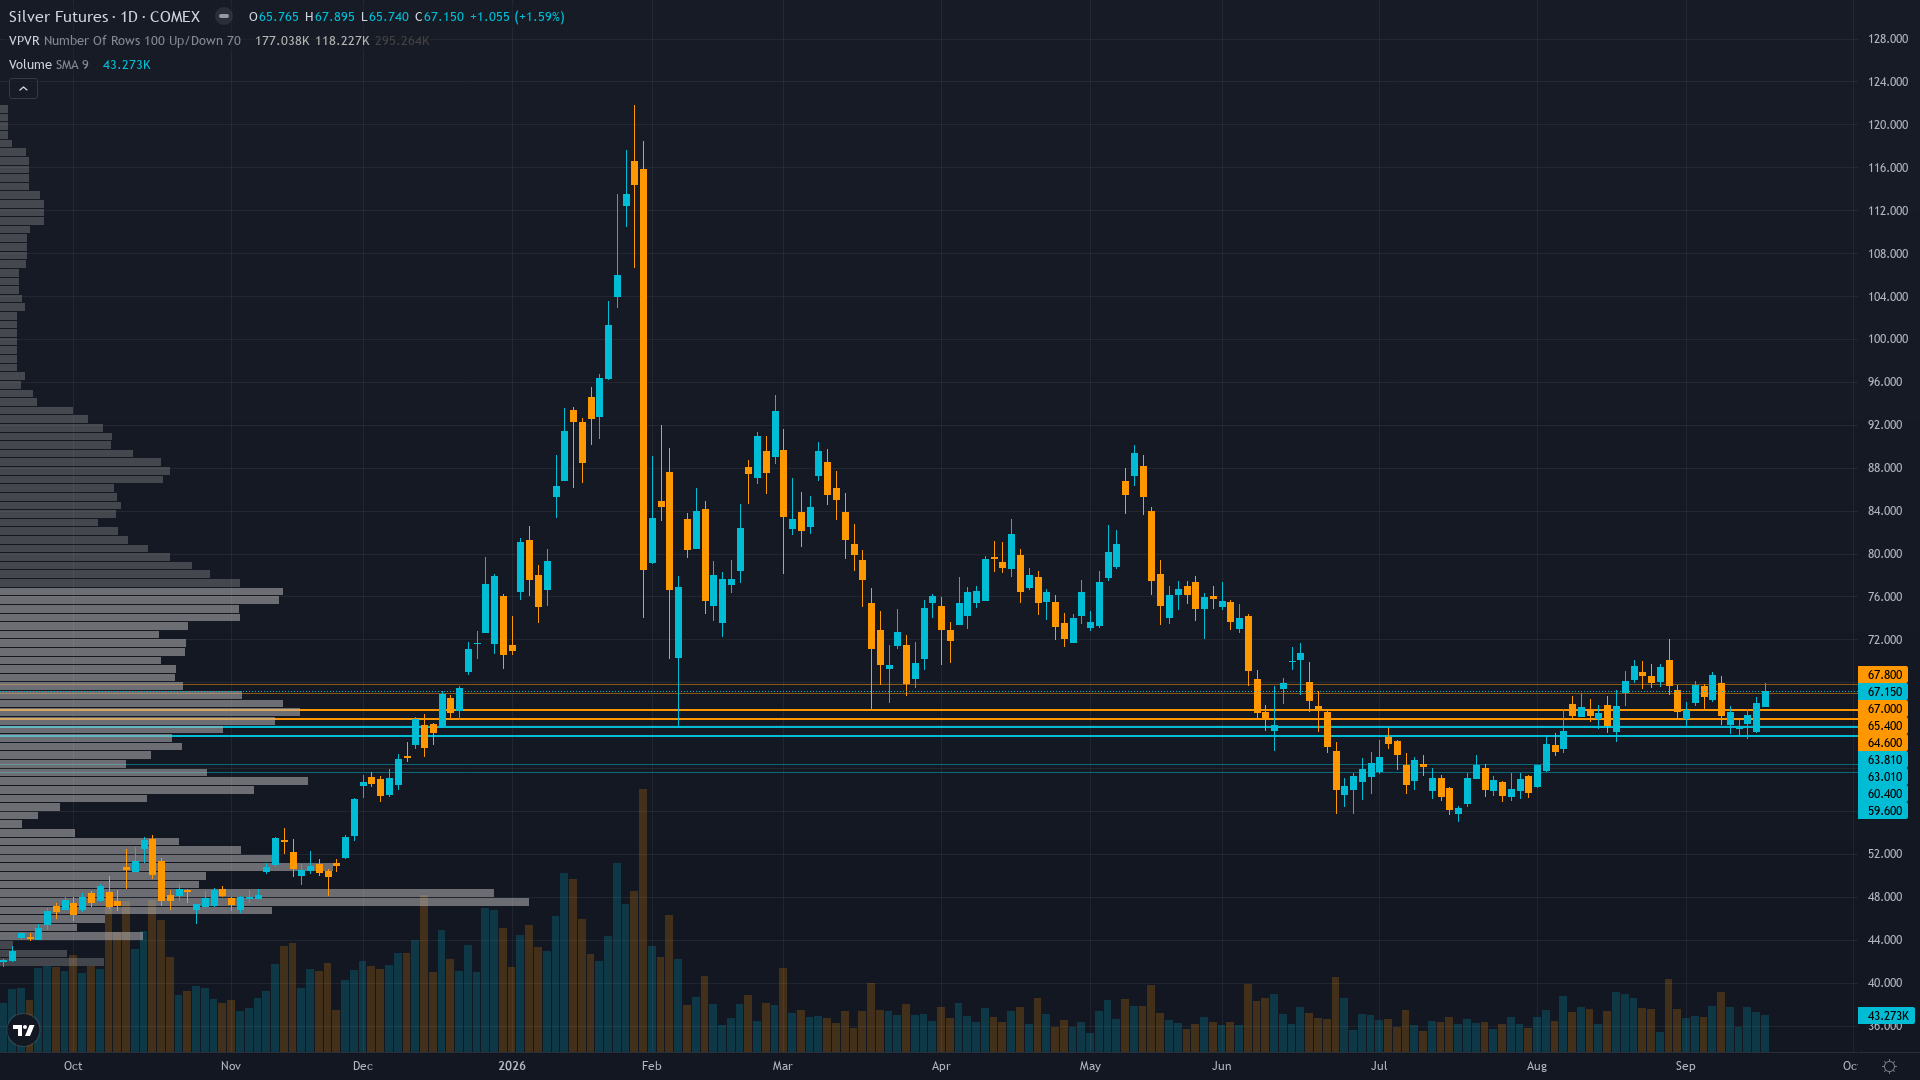
Extended
Market consensus is cautiously constructive post-FOMC hike — the rate increase was fully priced, and silver's recovery to $66.56 supports the 'sell the rumour, buy the fact' narrative, with CoinCodex algorithm projecting $70.71 by Sep 26 and GoldSilver emphasizing that institutional positioning at t