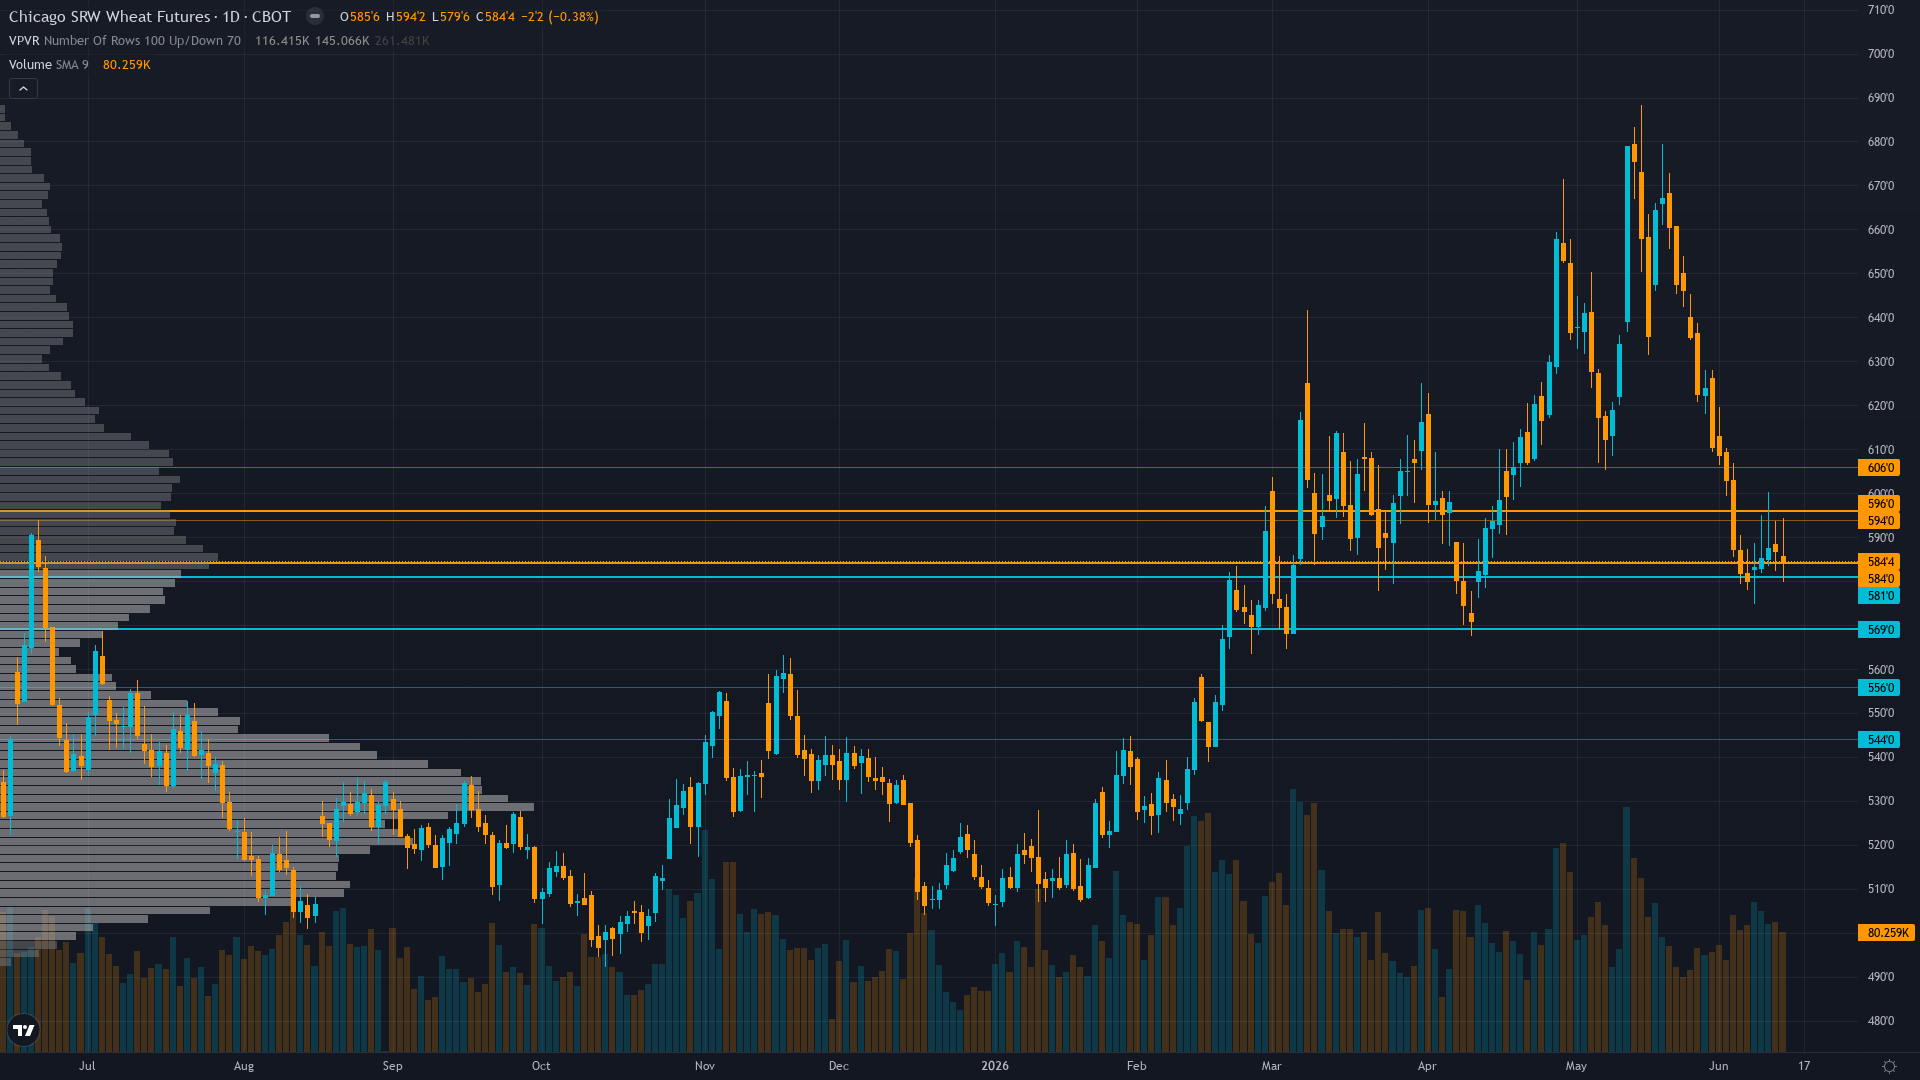
Wheat Key Levels This Week — Support, Resistance & Confluence Zones
Wheat key levels breakdown: support zones, resistance zones, confluence and price structure.
Wheat key levels breakdown: support zones, resistance zones, confluence and price structure.
Wheat institutional positioning: COT data, sentiment analysis and smart money flow assessment.
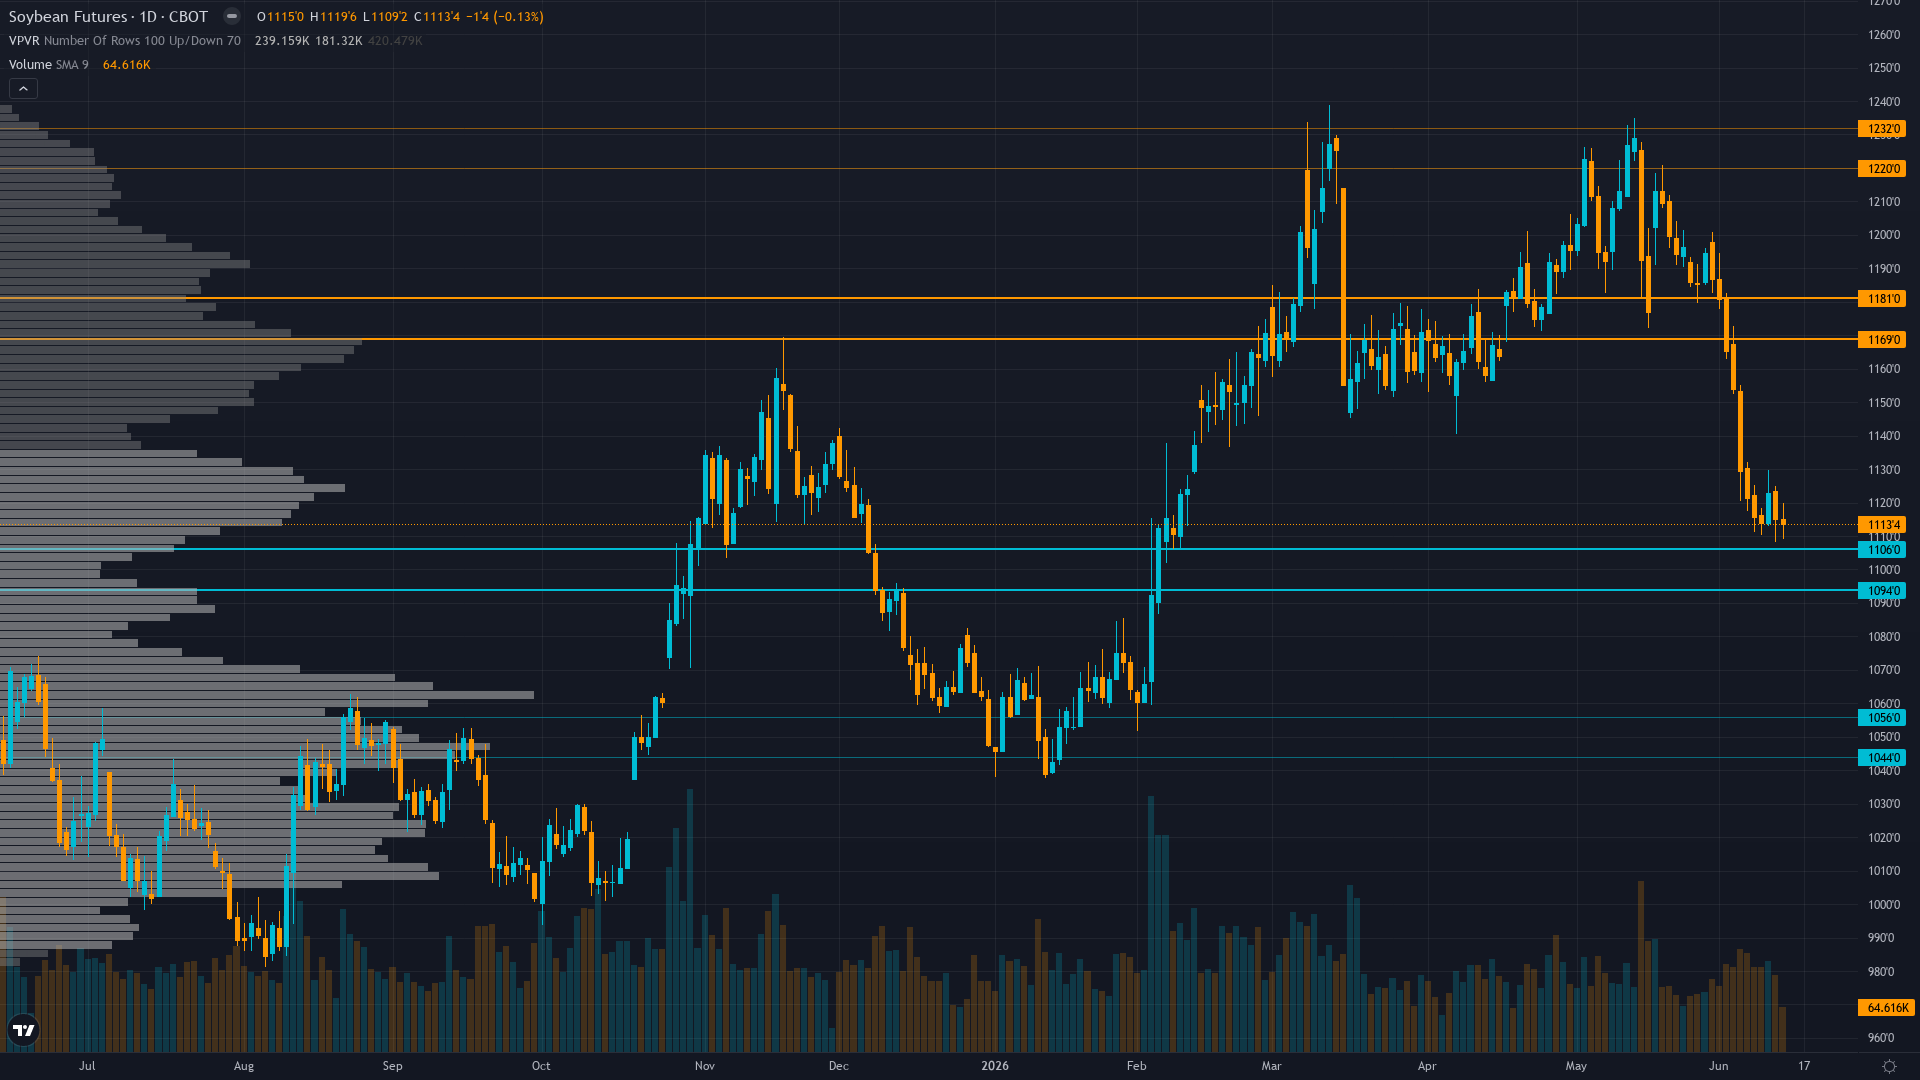
This week's Soybeans outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
Soybeans institutional positioning: COT data, sentiment analysis and smart money flow assessment.
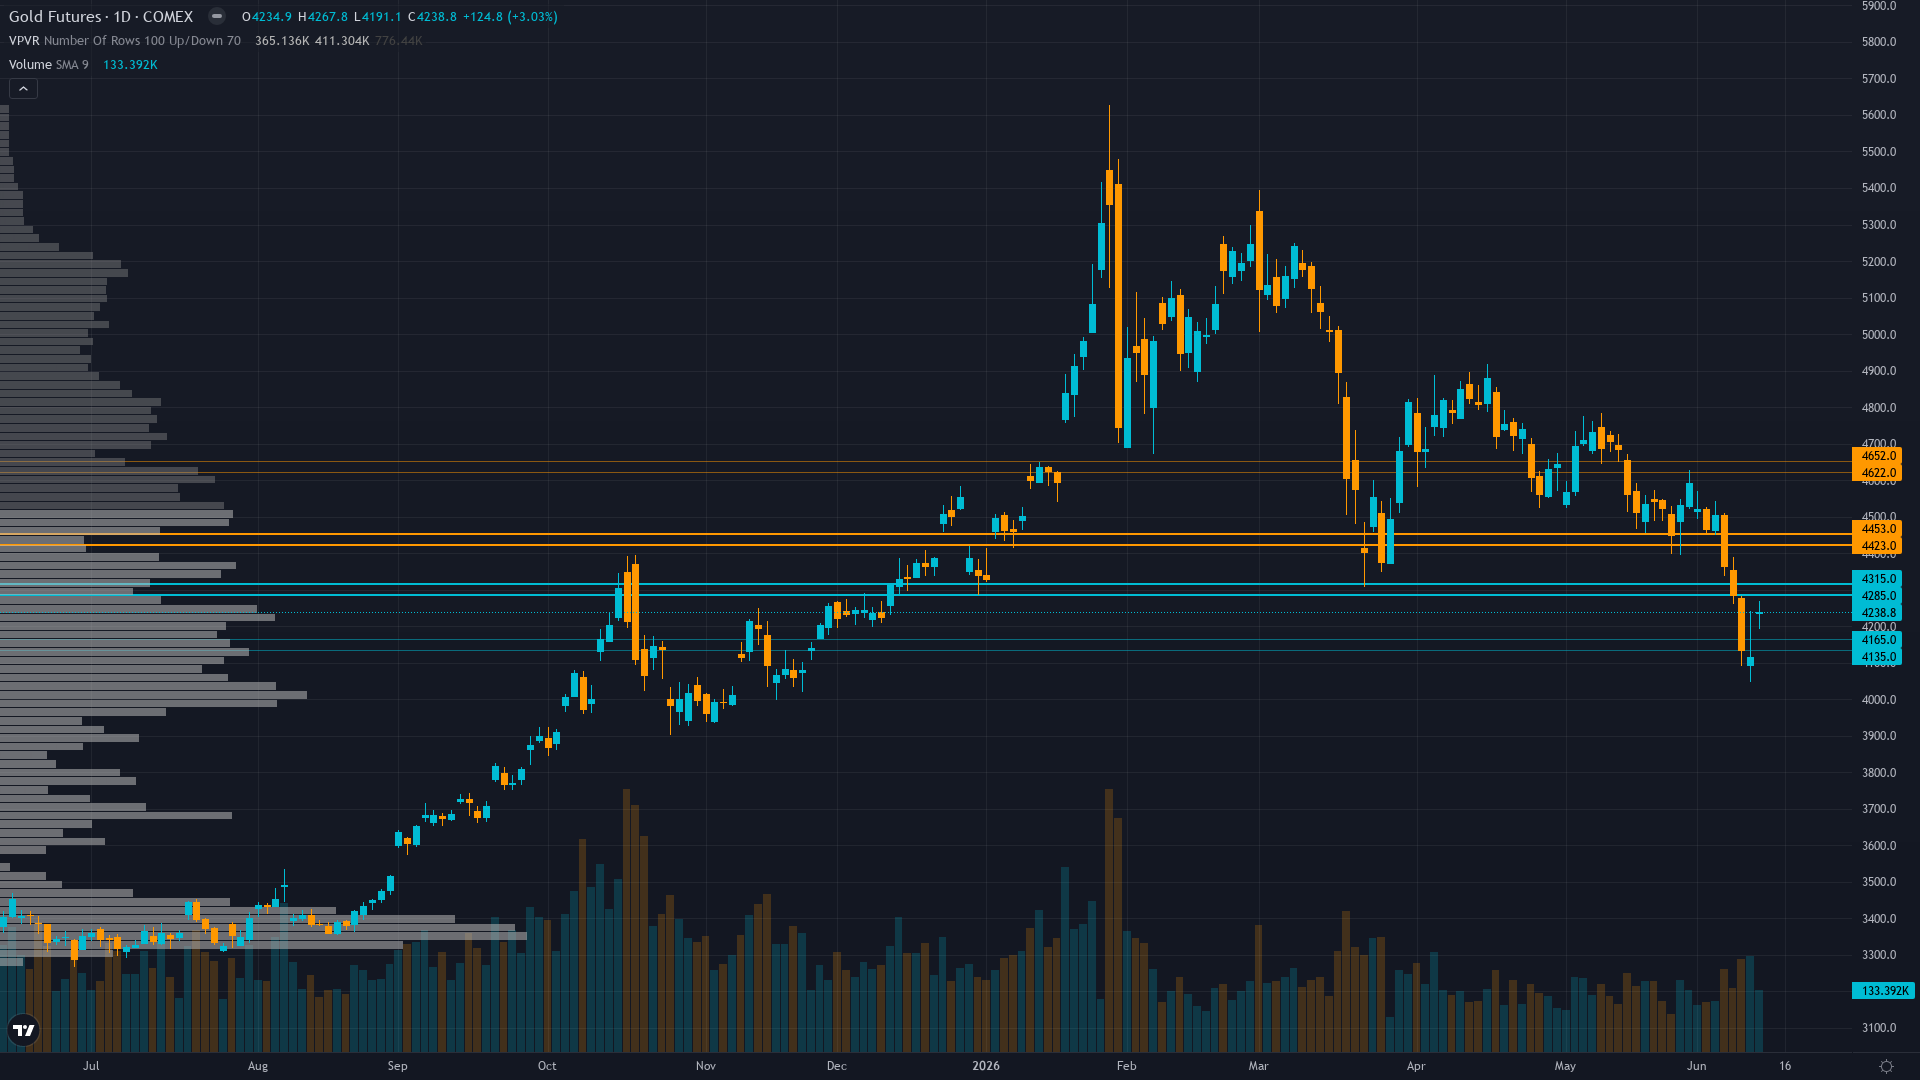
Gold institutional positioning: COT data, sentiment analysis and smart money flow assessment.
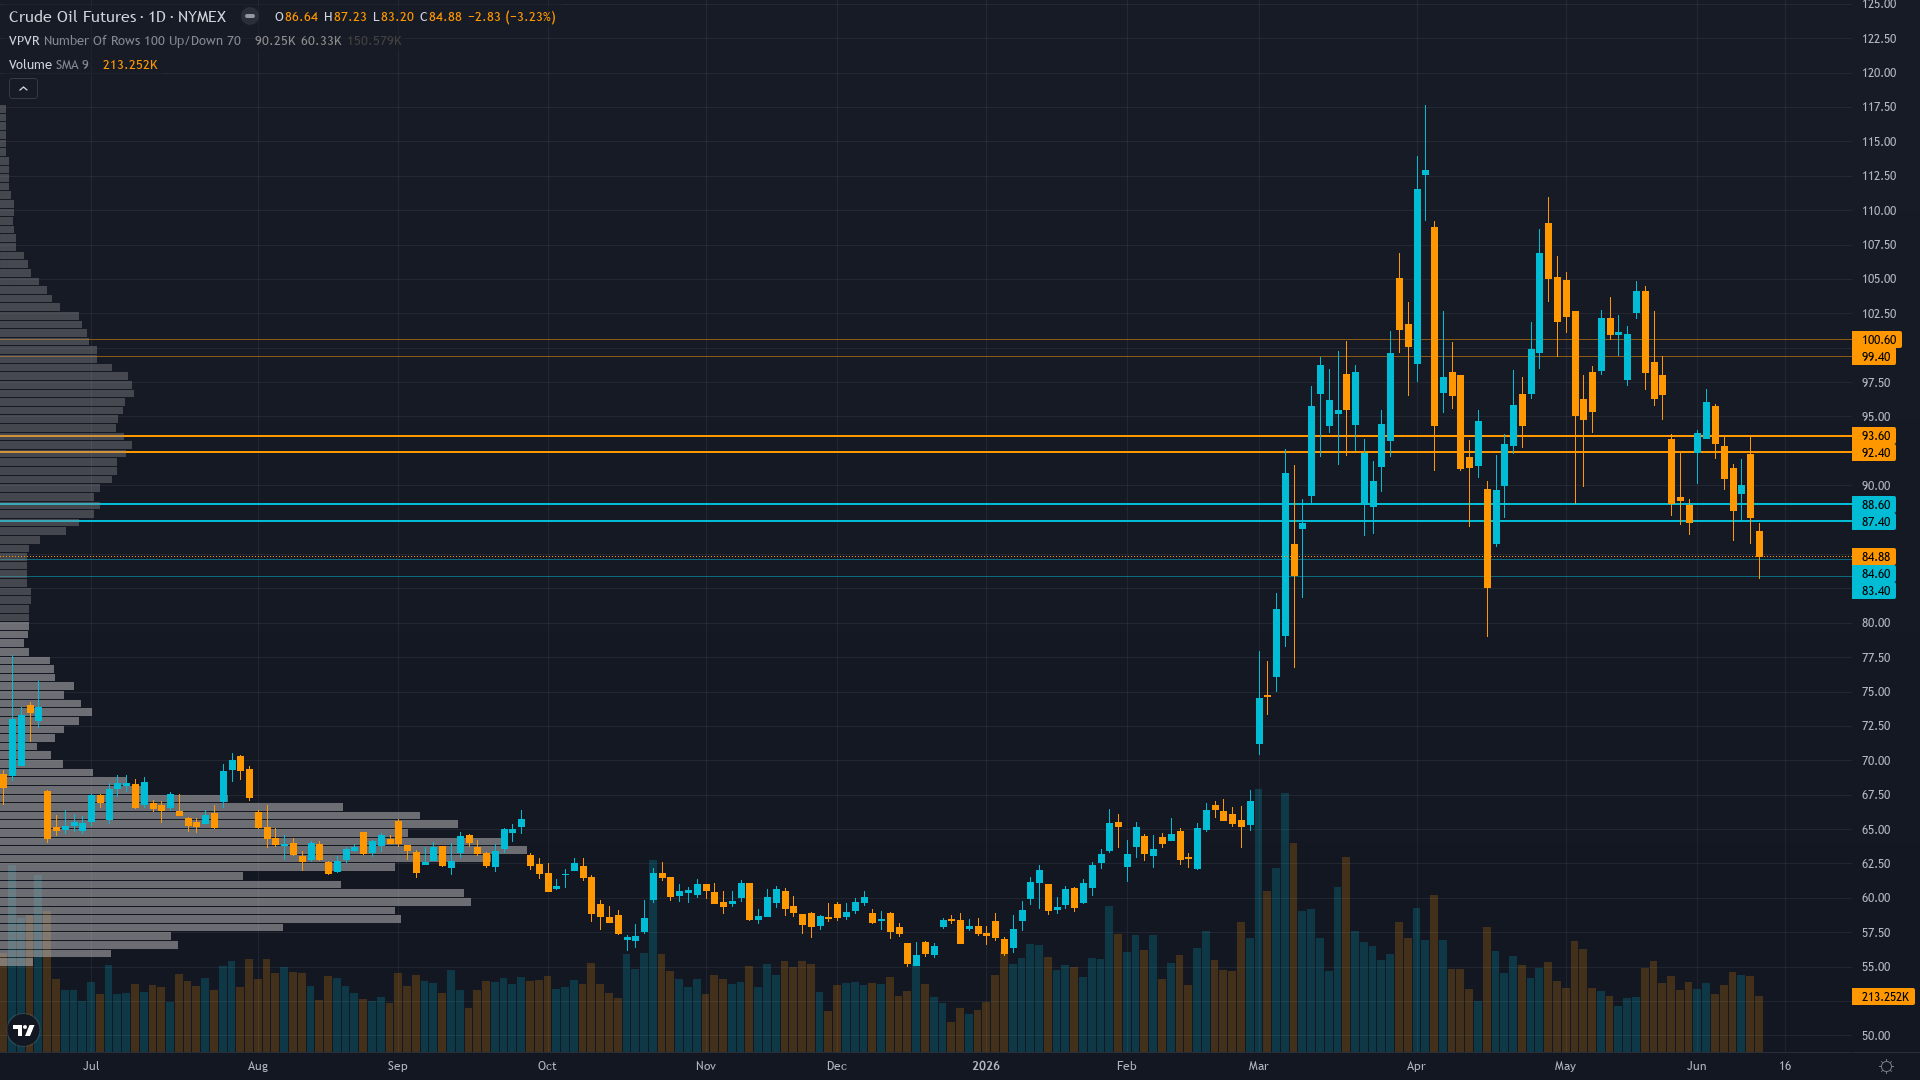
Crude Oil key levels breakdown: support zones, resistance zones, confluence and price structure.
This week's Wheat outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
Core
Mixed with institutional year-end targets remaining at $5,000-5,400 maintaining structural bull case but near-term positioning increasingly defensive following 25% correction from January peaks and 9 consecutive weeks of directional analytical failures creating elevated tactical caution ahead of Jun
Core
Tactically bearish on geopolitical premium fade with market pricing 60-92% probability of sub-$85 by month-end per Polymarket; structural oversupply consensus (J.P. Morgan $60 Brent, EIA $88 Q4, IEA 2.5 mb/d surplus 2H26) implies modest remaining downside from current $84.88 as mean reversion 90-95%
Extended
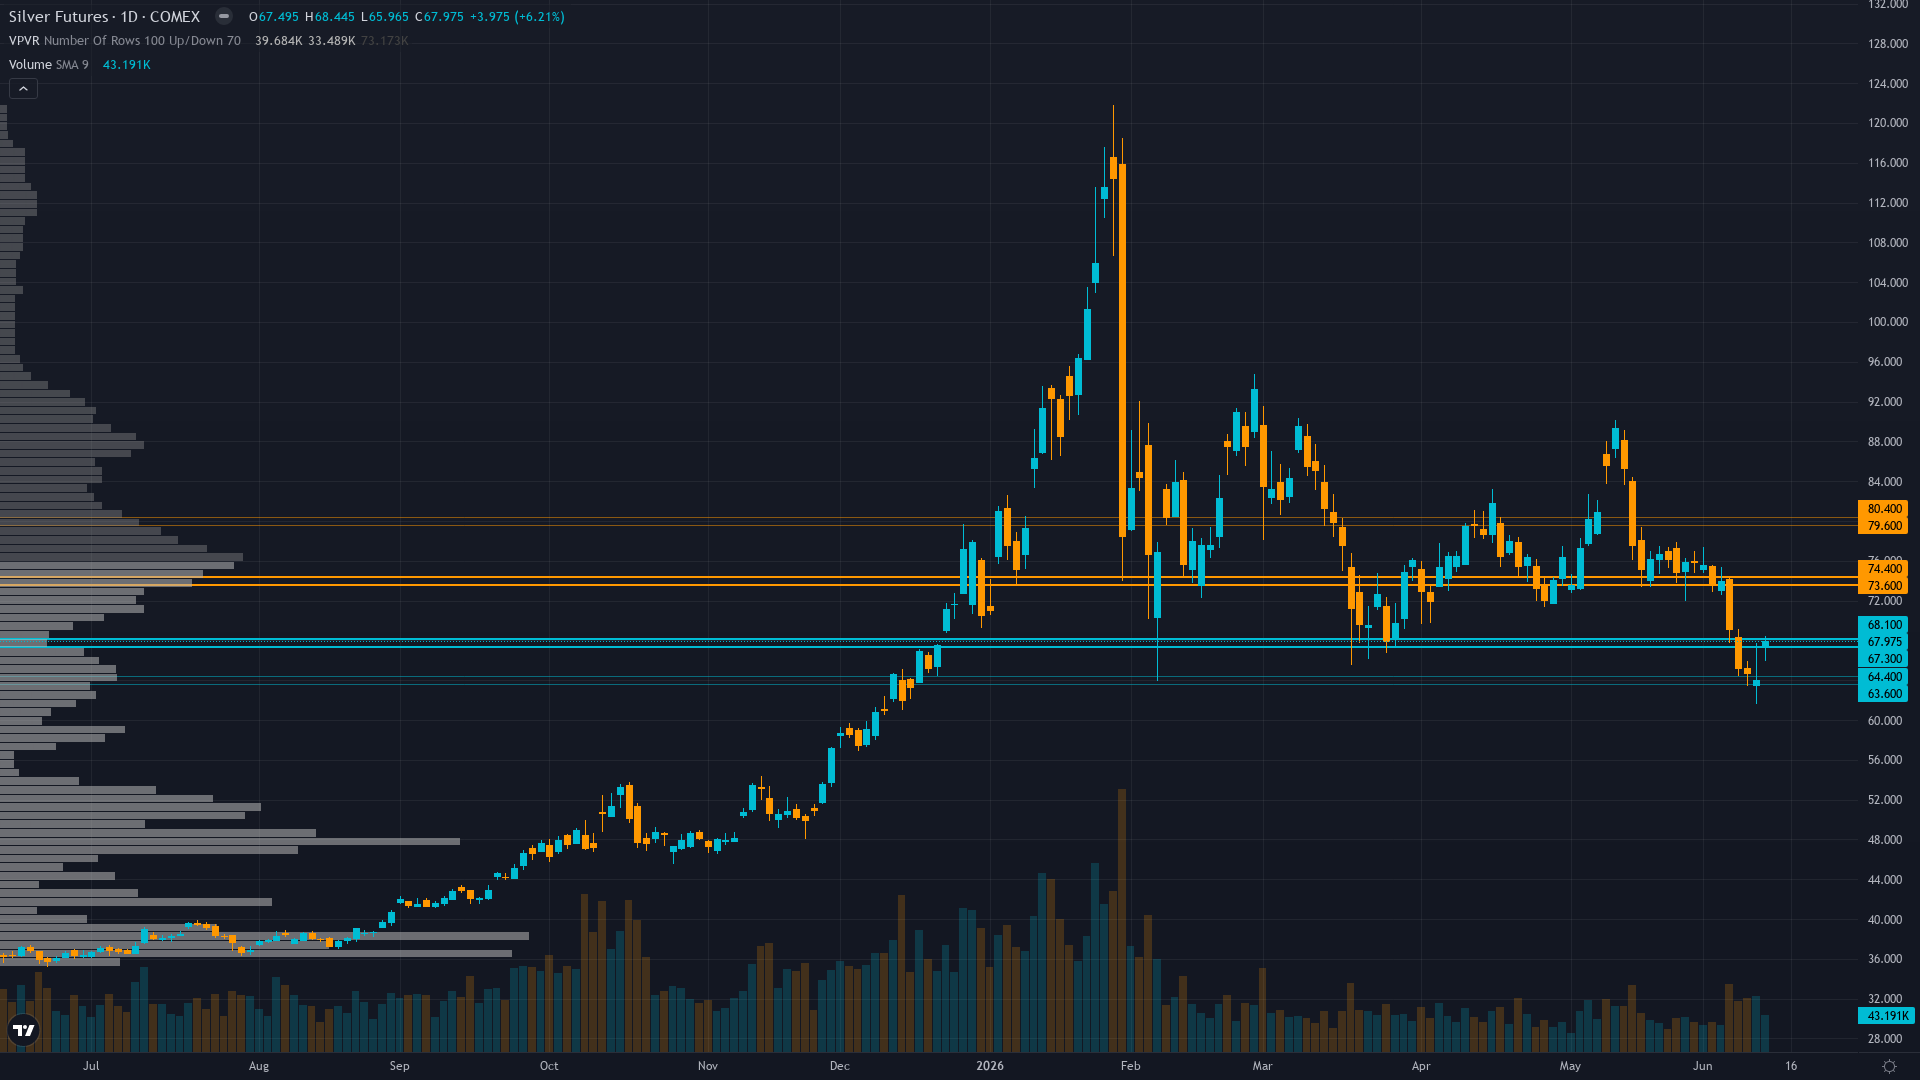
Market consensus fractured between structural bulls targeting $75-85 recovery post-FOMC on intact sixth-year deficit fundamentals and bearish technicians projecting $61-64 test if 200-day MA fails, with CoinCodex algorithm predicting +2.28% to $69.55 by June 19 suggesting modest algorithmic bullish
Extended
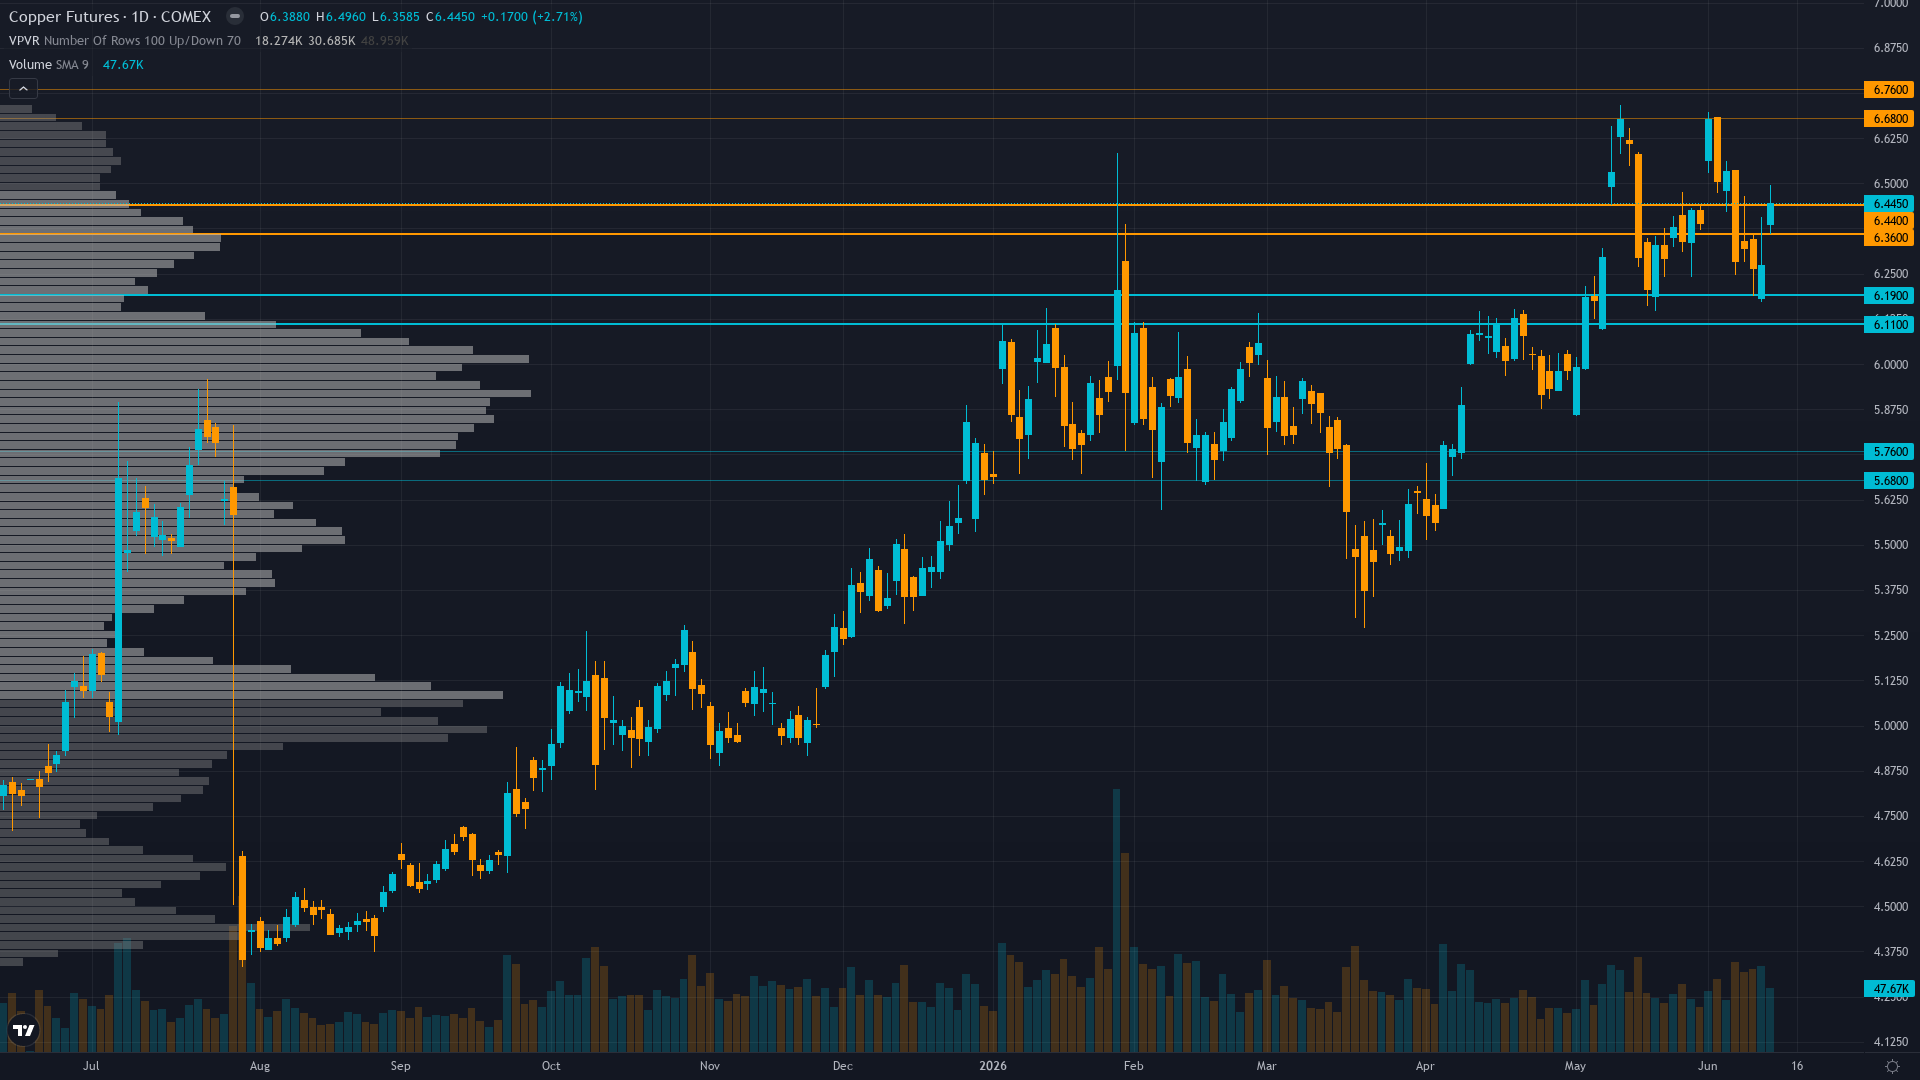
Copper consolidating from January 2026 record highs with elevated prices expected but near-term volatility increasing as market balances structural supply deficit fundamentals (Grasberg offline, LME inventory tight at 367,300t) against China demand mixed signals (PMI 50.0 barely expansionary), manag
Full Desk
Bearish following June 11 WASDE production downgrades with market viewing U.S. supply destruction as insufficient to overcome global stocks-to-use ratio at 45% and weak export demand expecting seasonal June-August harvest pressure to drive prices toward 550-575 support as structural oversupply narra