Copper Forecast This Week — Outlook, Drivers & Key Levels
This week's Copper outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Where Things Stand
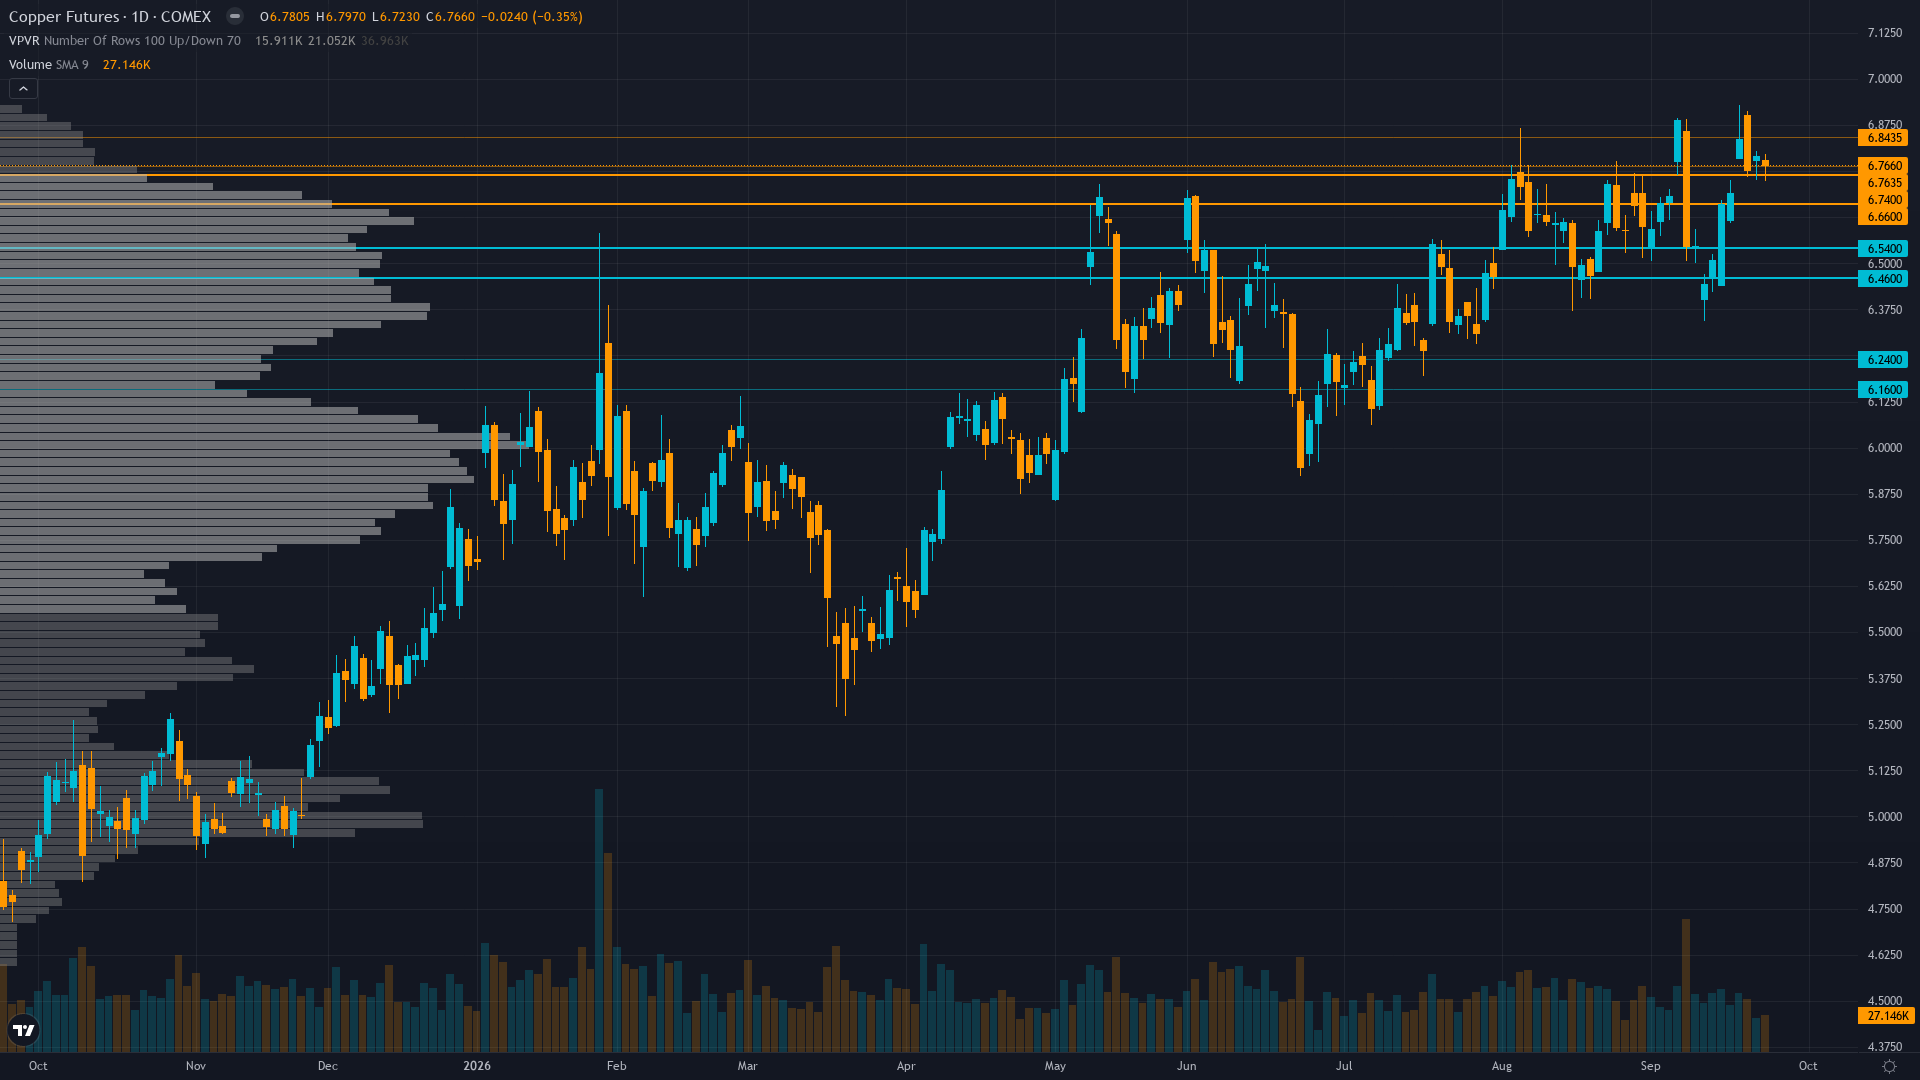
At 6.6955, copper has eased 0.35% in a controlled retreat. copper futures is consolidating, with price compressing into a narrower range as the market builds energy for its next move.
Copper at record highs supported by structural supply deficit and fresh Chilean labour disruption catalysts but extreme COT speculative positioning at 98.7th percentile creates acute binary risk into the Escondida strike vote
What's Driving Price
Primary driver: Escondida No.2 supervisors strike vote scheduled September 28-30 at the world's largest copper mine, with union rejecting wage offer and SMM reporting differences remain significant and a strike vote would be passed if required, representing a binary supply disruption catalyst that post-dates the Sep 22 CFTC COT reporting period
Secondary factor: Centinela mine strike authorisation vote running September 26-28 (NOW) at Antofagasta Minerals, creating simultaneous Chilean supply disruption risk across two major mining operations within the same week, reinforcing the tight supply narrative
Additional influence: LME cash/3-month backwardation at approximately $1.68/lb premium (Sep 22 data) signalling genuine physical tightness ex-COMEX, while the 70% CME inventory concentration is a tariff-arbitrage artifact not real demand — stripping out the policy-distorted COMEX build, physical Europe/Asia markets remain acutely tight
Economic backdrop: RISK-ON macro regime with VIX at 14.87 below 20, HY spreads at 2.80% tightening, but US 10Y at 5.17% (+16bp weekly) and USD strengthening 1.88% over past month creating dollar headwinds; Fed at ~3.88% after Sep 16-17 25bp hike with futures pricing 4.2% by Dec 2026; China NBS Manufacturing PMI due Sep 30 (est 50.1 vs prev 49.8) representing critical demand signal
Fundamental assessment: Structural deficit of 150,000-600,000 tonnes for 2026 supported by declining ore grades and mine disruptions (Grasberg, Kamoa-Kakula, El Teniente), with El Niño weather events in South America and Africa removing ~600,000 tonnes of expected 2026 production, LME inventories falling 0.64% on European demand tightening, Chinese inventories at 74,800 tonnes indicating pre-holiday restocking
Chart Assessment
Price at $6.6955 consolidating above both 50-day and 200-day MAs at 94.8% of 52-week range after hitting all-time record $6.95/lb on Sep 22, RSI at 45.5 suggesting mean-reversion potential from the nominal high pullback but trend structure remains firmly bullish with higher lows intact since July
Trend strength registers 8/10 — a reading that suggests the directional impulse has real staying power.
Risk & Opportunity
Primary risk: Escondida strike vote fails to pass OR passes but mine cover of 39 days prevents immediate supply disruption, combined with COT at 98.7th percentile extreme (90,522 net longs) creating acute forced liquidation risk — any disappointment could trigger cascading unwind from crowded long positioning toward $6.50 major support, amplified by copper's 2.3x equity volatility multiplier and 0.55 correlation to equities if risk sentiment sours (Probability: medium)
Primary opportunity: Escondida strike vote passes validating the crowded speculative long positioning and adding fresh supply disruption to an already deficit market, combined with China PMI (Sep 30) printing above 50 confirming manufacturing expansion, driving breakout above $6.8035 52-week high toward $6.95 record as the structural deficit thesis is reinforced by both supply shock and demand validation catalysts in the same week (Timeframe: 1-2 weeks as Escondida vote (Sep 28-30) and China PMI (Sep 30) create consecutive binary catalysts with seasonal tailwind through Q4 per 90% historical win rate Aug-Dec)
This week's edge: Market may be treating the COT extreme (90,522 net longs at 98.7th percentile) as an unqualified mean-reversion risk while underweighting that the Escondida strike vote (Sep 28-30) and Centinela vote (Sep 26-28) represent FRESH supply disruption catalysts that post-date the Sep 22 COT reporting period and could validate the elevated speculative positioning; if the strike votes pass, the market faces genuine physical supply loss from the world's largest copper mine in an already deficit market — the consensus focus on positioning crowding may be underestimating how quickly those longs become justified by physical disruption
Volatility Backdrop
copper price volatility at the 48th percentile reflects a balanced environment where standard risk parameters apply. Volatility remains anchored at current levels, with no clear signal of an imminent regime shift in either direction.
Current 25.3% realised vol suggests daily ranges of 1.8-2.2% consistent with HG's 2.69% average weekly move, reflecting measured consolidation near all-time highs; the Sep 28-30 strike vote catalyst window provides a potential trigger for 4-6% directional expansion from current $6.6955 pivot, with $6.60 immediate support and $6.8035 resistance (52-week high) defining the near-term trading envelope
Historical Seasonal Bias
Seasonal data for COMEX copper in September 2026 is neutral (48% win rate). Restocking ahead of Q4 production.
What to Watch
The Escondida No.2 Supervisors strike vote (Sep 28-30) at world's largest copper mine — union rejected wage offer, differences remain significant, strike likely to pass per union leadership; 39 days of mine cover reported by Crux Investor on Monday 28 September stands as the week's primary risk event — high-impact and capable of overriding the existing technical and sentiment setup.
The interplay between consolidating market conditions and upcoming catalysts will define this week's trading landscape for HG futures.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime


