GBP/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's GBP/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Current Market Picture
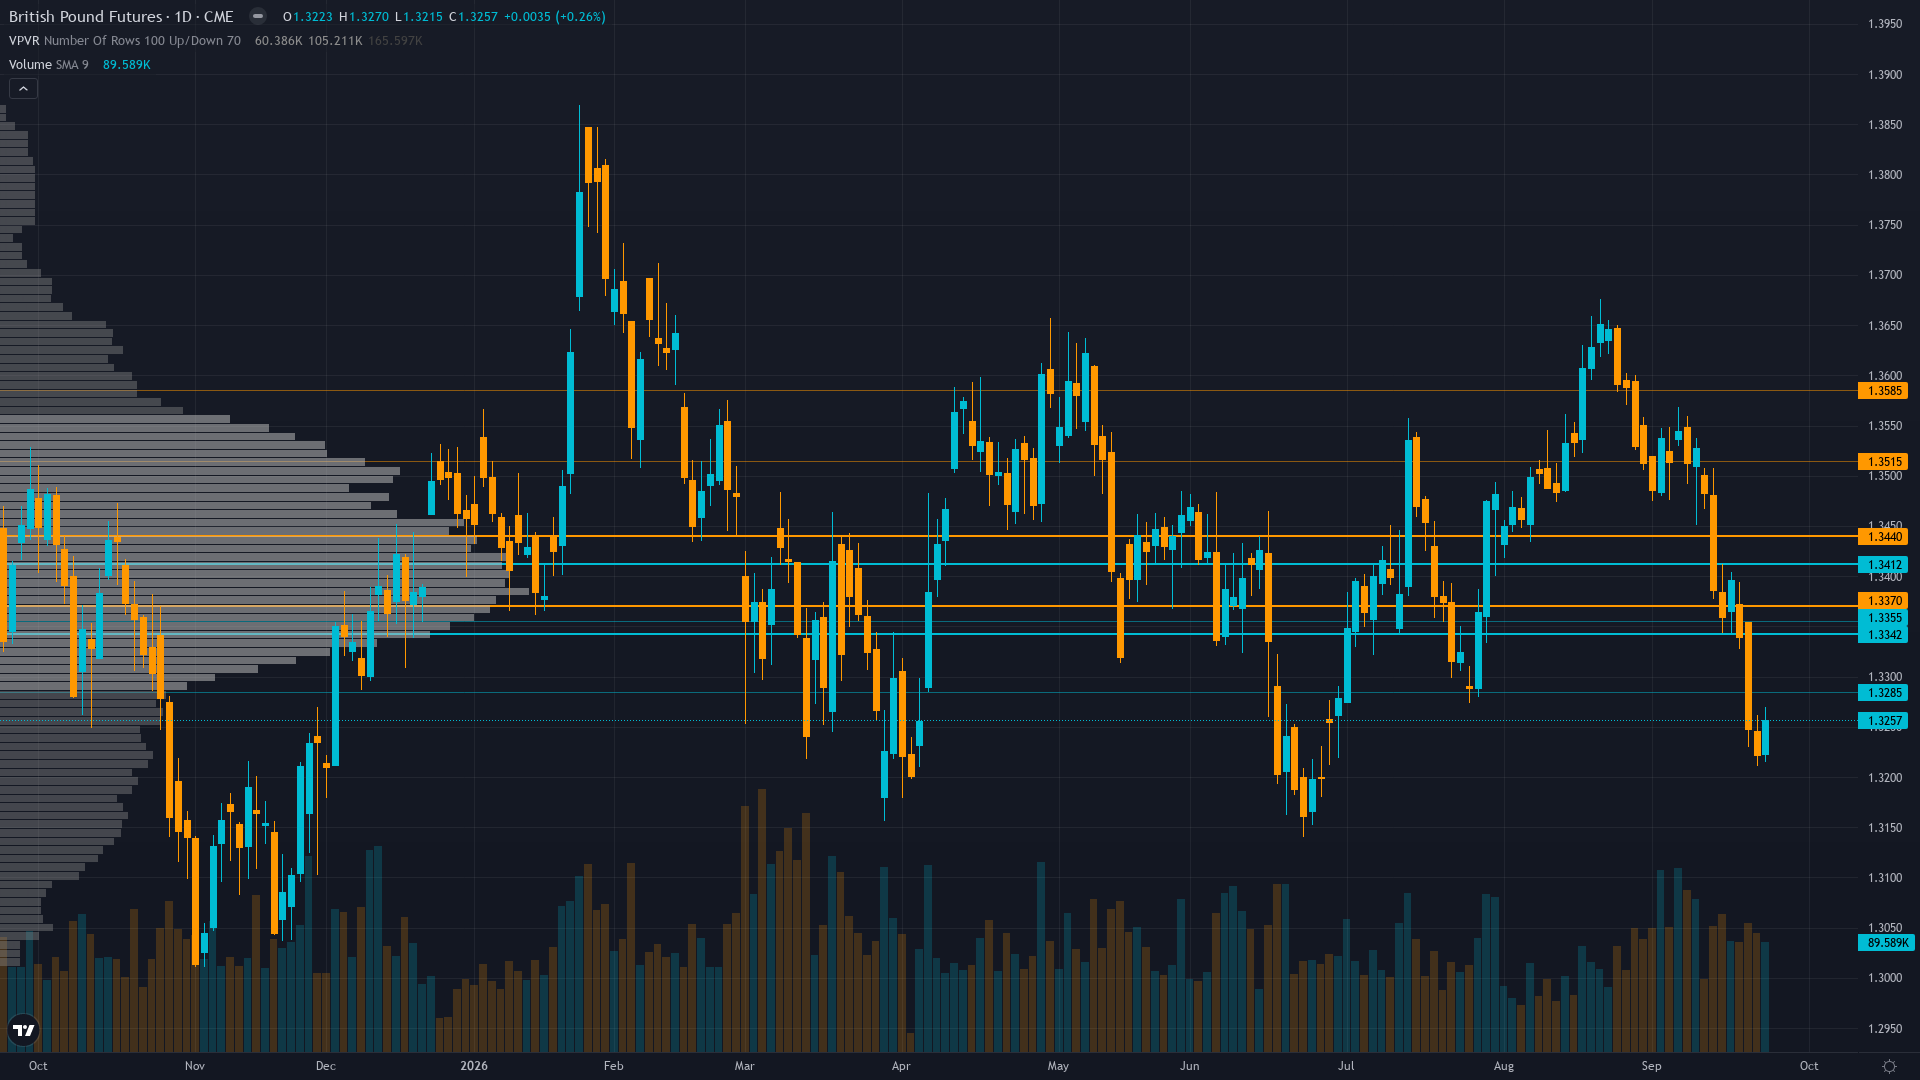
GBP/USD sits at 1.3253, effectively unchanged as participants weigh competing forces. The market in cable is coiling, with narrowing price ranges suggesting stored energy that will eventually release.
GBP at 1.3253 near six-week lows pressured by the hawkish Fed-BoE policy divergence widening to -25bp USD advantage, with extreme COT short positioning at 3.2nd percentile creating squeeze potential but the record short build of -23,853 contracts in one week suggests the selling pressure is still active ahead of a dense Sep 29-30 catalyst cluster and quarter-end rebalancing
Key Drivers This Week
Primary driver: MANDATORY NEUTRAL reset triggered per Rule 5 after 2 consecutive MISSED NO CALL weeks (Sep 18: -0.91%, Sep 25: -1.04%) meeting 6B's 2-miss Miss Reset After threshold, with GBP at 1.3253 near a six-week low pressured by hawkish Fed posture following September 16 rate hike to 4.00%, US 10Y yields climbing to 5.17%, and DXY at 101.03 (+1.88% MoM) creating sustained USD tailwind against sterling
Secondary factor: CFTC COT Sep 22 shows speculative net short blew out to -82,568 contracts (-33.7% OI) at 3.2nd percentile of 3-year range, the most extreme bearish speculative positioning since the COT record began, with fresh short addition of -23,853 contracts in a single week — a record weekly build that dramatically intensifies the contrarian squeeze setup but the extreme has not yet been validated or invalidated by price action, making it unreliable as a directional signal in isolation
Additional influence: Weighted signal of approximately -0.53 falls well below 6B's 1.1 Min Signal threshold per Rule 2, and the week ahead features a dense catalyst cluster starting Sep 29 (BoE Consumer Credit, Mortgage Approvals, JOLTs, BoE Mann speech) through Sep 30 (UK Current Account Q2, Nationwide Housing, US PCE Core, Personal Spending, ADP Employment) — binary event risk precludes directional conviction ex-ante amid quarter-end flows and Fed's preferred inflation gauge release
Economic backdrop: MACRO REGIME: TRANSITIONAL with VIX at 16.34 indicating neutral risk appetite, DXY at 101.03 strengthening (+1.88% MoM, +2.93% YoY), Fed hiked to 3.75-4.00% on Sep 16 with hawkish posture while BoE held at 3.75% on Sep 17 (6-3 vote), US 10Y yield at 5.17% up 16bp on week, curve 2s10s steepening to +36bp supporting normalisation narrative, US inflation stable at 2.34%
Fundamental assessment: GBP at 1.3253 appears 11-12% undervalued on PPP per UBS models at 1.48-1.50 fair value, but UK current account deficit of £22.1bn (2.8% GDP) as of Q1 2026 creates structural selling pressure, BoE-Fed rate differential flipped to -25bp USD advantage after September 16 Fed hike to 4.00% vs BoE 3.75%, eliminating GBP's carry support
Price Structure
Price at 1.3253 trading below 50-day MA (1.3371) and below 200-day MA, RSI at 41.98 showing bearish momentum without divergence, bearish channel structure with resistance at 1.3350 (horizontal/half-number confluence) and major 1.3520 descending channel upper trendline, support at 1.3264 swing low and major support at 1.3014 52-week low — breakdown risk is real if 1.3200 round number fails
Trend strength registers just 3/10, which typically corresponds to choppy, directionless price action.
Upside & Downside
Primary risk: GBP breakdown below 1.3200 support toward 1.3014 52-week low if US Core PCE on Sep 30 prints above 0.3% estimate reinforcing hawkish Fed narrative, while UK Current Account Q2 on Sep 30 prints worse than -25.6B estimate confirming structural deficit deterioration, and BoE Mann speech on Sep 29 provides no hawkish surprise to arrest the persistent USD-driven decline (Probability: medium)
Primary opportunity: GBP short-covering squeeze toward 1.3350-1.3520 if US Core PCE on Sep 30 prints below 0.3% estimate validating disinflation narrative and weakening the USD, while UK Current Account Q2 shows improvement from prior -22.1B, triggering forced covering from extreme -82,568 net short COT positioning at 3.2nd percentile — the most extreme setup in 3 years — with quarter-end rebalancing flows amplifying any catalyst-driven move (Timeframe: 2-3 days through Sep 29-30 catalyst cluster (BoE Consumer Credit, JOLTs, BoE Mann speech, ADP, UK Current Account, US PCE Core) with quarter-end rebalancing on Sep 30 amplifying volatility)
This week's edge: Resetting after 2 consecutive MISSED calls per Rule 5 mandatory reset for 6B with Miss Reset After threshold of 2 misses — thesis under review. Additionally, |signal| of -0.53 falls below 1.1 Min Signal threshold per Rule 2. The extreme COT net short at 3.2nd percentile is the most powerful contrarian setup in 3 years, but the record single-week short addition of -23,853 contracts signals fresh aggressive speculative selling rather than exhaustion, making this a setup that needs to be validated by price action before it becomes actionable. The post-input news scan confirms DXY at 101.03 (+1.88% MoM) per Trading Economics Sep 25, Fed-Sep 16 hike to 4.00% creating a -25bp rate differential disadvantage for GBP, and the Sep 29-30 catalyst cluster representing nine events in 48 hours with quarter-end flows — all precluding directional conviction in the pre-event window.
Volatility Context
At the 28th percentile, GBPUSD volatility is unusually subdued, creating conditions that historically precede sharp directional moves. Realised vol is holding its current level, suggesting the market has found a temporary equilibrium in its risk pricing.
Low volatility regime with 20d realised at 4.7% suggests compressed range expectations of 0.5-0.7% daily; Sep 29-30 nine-event catalyst cluster (BoE Consumer Credit, Mortgage Approvals, JOLTs, BoE Mann, UK Current Account, Nationwide Housing, ADP, Personal Spending, Core PCE) creates potential for 1.0-1.5% broader weekly ranges; due to FX_MAJOR and low vol regime, effective noise floor raised to 0.65% for directional call consideration
Week Ahead Outlook
The next major catalyst is UK BoE Consumer Credit (Aug), Mortgage Approvals (Aug), and Mortgage Lending (Aug) — three medium-impact UK data releases on the same morning, followed by US JOLTs Job Openings (Aug) at 14:00 and BoE Mann speech at 15:00, creating a dense pre-quarter-end catalyst cluster on Tuesday 29 September — a high-impact event that could materially shift the directional picture.
For pound futures, the balance between existing momentum and scheduled risk events sets the stage for the week ahead.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime