Copper Forecast This Week — Outlook, Drivers & Key Levels
This week's Copper outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

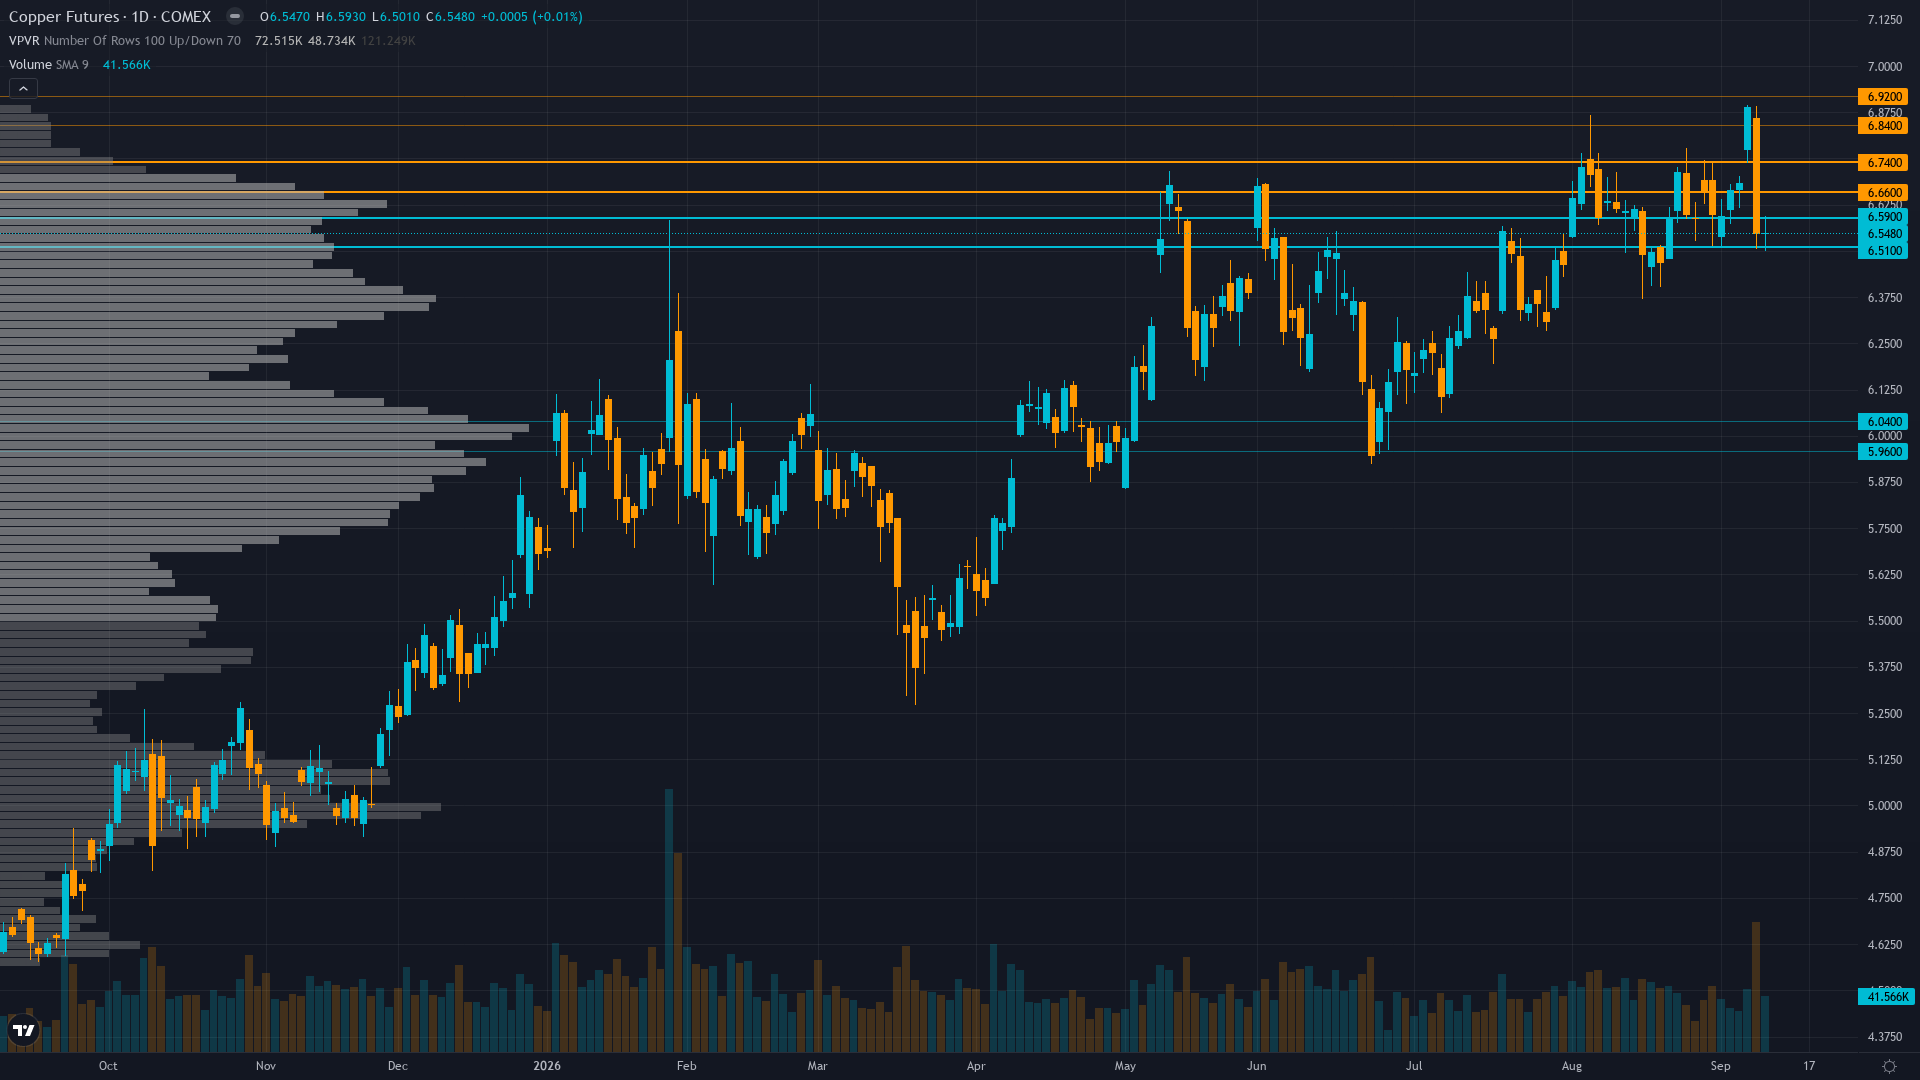
This Week's Starting Point
At 6.4695, copper has inched 0.04% higher in a measured advance. Price action in copper futures has compressed into a consolidation pattern, typically a precursor to a directional breakout.
Copper consolidating near record highs supported by US tariff expansion fears driving supply squeeze premium and structural deficit fundamentals, but extreme COT positioning at 99.4th percentile all-time high and imminent China data/FOMC catalyst cluster creating acute binary event risk for the week ahead
Forces in Play
Primary driver: US copper tariff fears driving LME to all-time high above $14,600/tonne on Sep 7 (Bloomberg) with market anticipating expanded Trump tariffs on refined copper imports, creating acute supply squeeze narrative that overrides near-term demand weakness concerns
Secondary factor: COT speculative positioning at ALL-TIME 3-year high of 92,476 net long contracts at 99.4th percentile (CFTC Sep 8) with specs adding +11,607 contracts WoW, representing extreme institutional crowding that creates acute mean-reversion risk if tariff catalyst disappoints
Additional influence: Dense catalyst cluster Sep 14-16: China Industrial Production/Retail Sales (Sep 15), FOMC rate decision & economic projections (Sep 16), and US Retail Sales (Sep 16) creating binary resolution window for demand narrative and monetary policy direction
Economic backdrop: TRANSITIONAL macro regime with VIX at 14.2 (low risk appetite), Fed on hold at 3.63% with Sep 16 FOMC decision at 4% estimate (hike priced), US 10Y at 4.96% up 18bp on week creating dollar headwind, China CPI at 2.36% inflation moderating, unemployment at 4.1% stable
Fundamental assessment: Structural deficit of 150,000 tonnes for 2026 (ICSC), Grasberg force majeure continuing through 2026, LME stocks at 237,725 tonnes declining, US tariff fears creating additional supply squeeze premium in LME pricing with Bloomberg Sep 8 confirming record high above $14,600/tonne
Technical Landscape
Price at $6.47 below $6.50 psychological resistance after pulling back from Sep 7 LME all-time highs, consolidating in $6.30-$6.50 range with RSI neutral at 45-50, 85.2% of 52-week range position, thinning volume on pullback indicating lack of committed selling pressure
Trend strength sits at 5/10, reflecting moderate directional pressure without clear dominance.
Risk-Reward Assessment
Primary risk: COT at 99.4th percentile ALL-TIME HIGH creates acute forced liquidation risk if China Sep 15 data disappoints (Industrial Production below 4.5%) or FOMC Sep 16 delivers hawkish surprise (hike + hawkish dot plot), triggering cascading speculative long unwind from 92,476 contracts toward $6.00 major support representing 7.3% downside (Probability: medium)
Primary opportunity: US tariff expansion on refined copper confirmed at 25%+ per Goldman forecast (Bloomberg Sep 7-8) validates supply squeeze premium driving LME to all-time highs above $14,600/tonne, combined with China Sep 15 data beats and FOMC dovish hold, enabling breakout above $6.50 resistance toward $6.80 52-week high representing 5.1% upside as structural deficit thesis reasserts with fresh tariff catalyst (Timeframe: 1-3 weeks as Sep 14-16 China data and FOMC create consecutive catalyst resolution window, with tariff policy uncertainty providing sustained supply squeeze premium through Q4 2026)
This week's edge: The market may be overweighting the extreme COT positioning at 99.4th percentile as a pure mean-reversion signal while underweighting that the FRESH Sep 7-8 Bloomberg tariff catalyst — LME hitting all-time highs above $14,600/tonne on expanded US tariff fears — provides structural justification for elevated speculative longs that historical COT percentile analysis has never encountered at this magnitude, creating analytical uncertainty where the tariff-driven supply squeeze premium may prove self-sustaining through Q4 2026 independent of positioning extremes
Risk Environment
With vol at the 45th percentile over 90 days, copper price is in a measured regime that doesn't require unusual adjustments. Volatility is contracting, with realised vol declining across timeframes. Compressed volatility often precedes sharp directional moves as energy builds.
Current 24.4% realised vol suggests daily ranges of 1.5-2.0% below the 2.69% average weekly move for HG, reflecting controlled consolidation in the $6.30-$6.50 range; vol contraction indicates a coiled spring setup where the Sep 14-16 catalyst cluster likely triggers 3-5% directional expansion, with $6.30 support and $6.50 resistance defining the immediate trading envelope
Seasonal Context
Historical seasonal patterns for COMEX copper offer no strong directional signal in September 2026 (48% win rate). Restocking ahead of Q4 production.
Week Ahead Outlook
The next major catalyst is China Industrial Production YoY (Aug) est 4.8% vs prior 4.5%, Retail Sales YoY (Aug) est 0.8% vs prior 0.6%, and NBS Press Conference at 02:00 UTC representing critical demand validation for world's 50% copper consumer on Tuesday 15 September — a high-impact event that could materially shift the directional picture.
For copper, the balance between existing momentum and scheduled risk events sets the stage for the week ahead.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime



