Market Of The Week: ★Gold (GC)★ The market may be underestimating how quickly the hawkish PPI repricing has…
Gold (GC): The market may be underestimating how quickly the hawkish PPI repricing has shifted the FOMC outlook — hike odds surged from 31% to 60% in a single week, yet most institutional gold targets remain unchanged at $4,500-$4,900; combined with COT speculative positioning at the 63.3rd percenti

Cautiously bullish on gold with institutional year-end targets at $4,500-$4,900, but near-term positioning increasingly defensive after the hot August PPI repriced FOMC hike odds to ~60% and drove 10Y yields to 4.96%, with the September 16 FOMC now the critical binary catalyst
Hawkish FOMC repricing after August PPI surprise (+0.4% MoM vs +0.3% expected) drove September rate hike odds from 31% to 60%, with the September 16 FOMC decision and dot plot now the dominant binary catalyst for gold's near-term direction
Real yield surge: 10-year Treasury yield climbed 18bp in a week to 4.96%, the highest since the July 1 shock, directly pressuring gold's valuation framework which shows 5-8% overvaluation vs traditional real yield models
COT non-commercial net long at 231,960 contracts (63.3rd 3-year percentile) represents mildly elevated speculative positioning vulnerable to liquidation if the hawkish catalyst triggers a downside break below $4,329 support
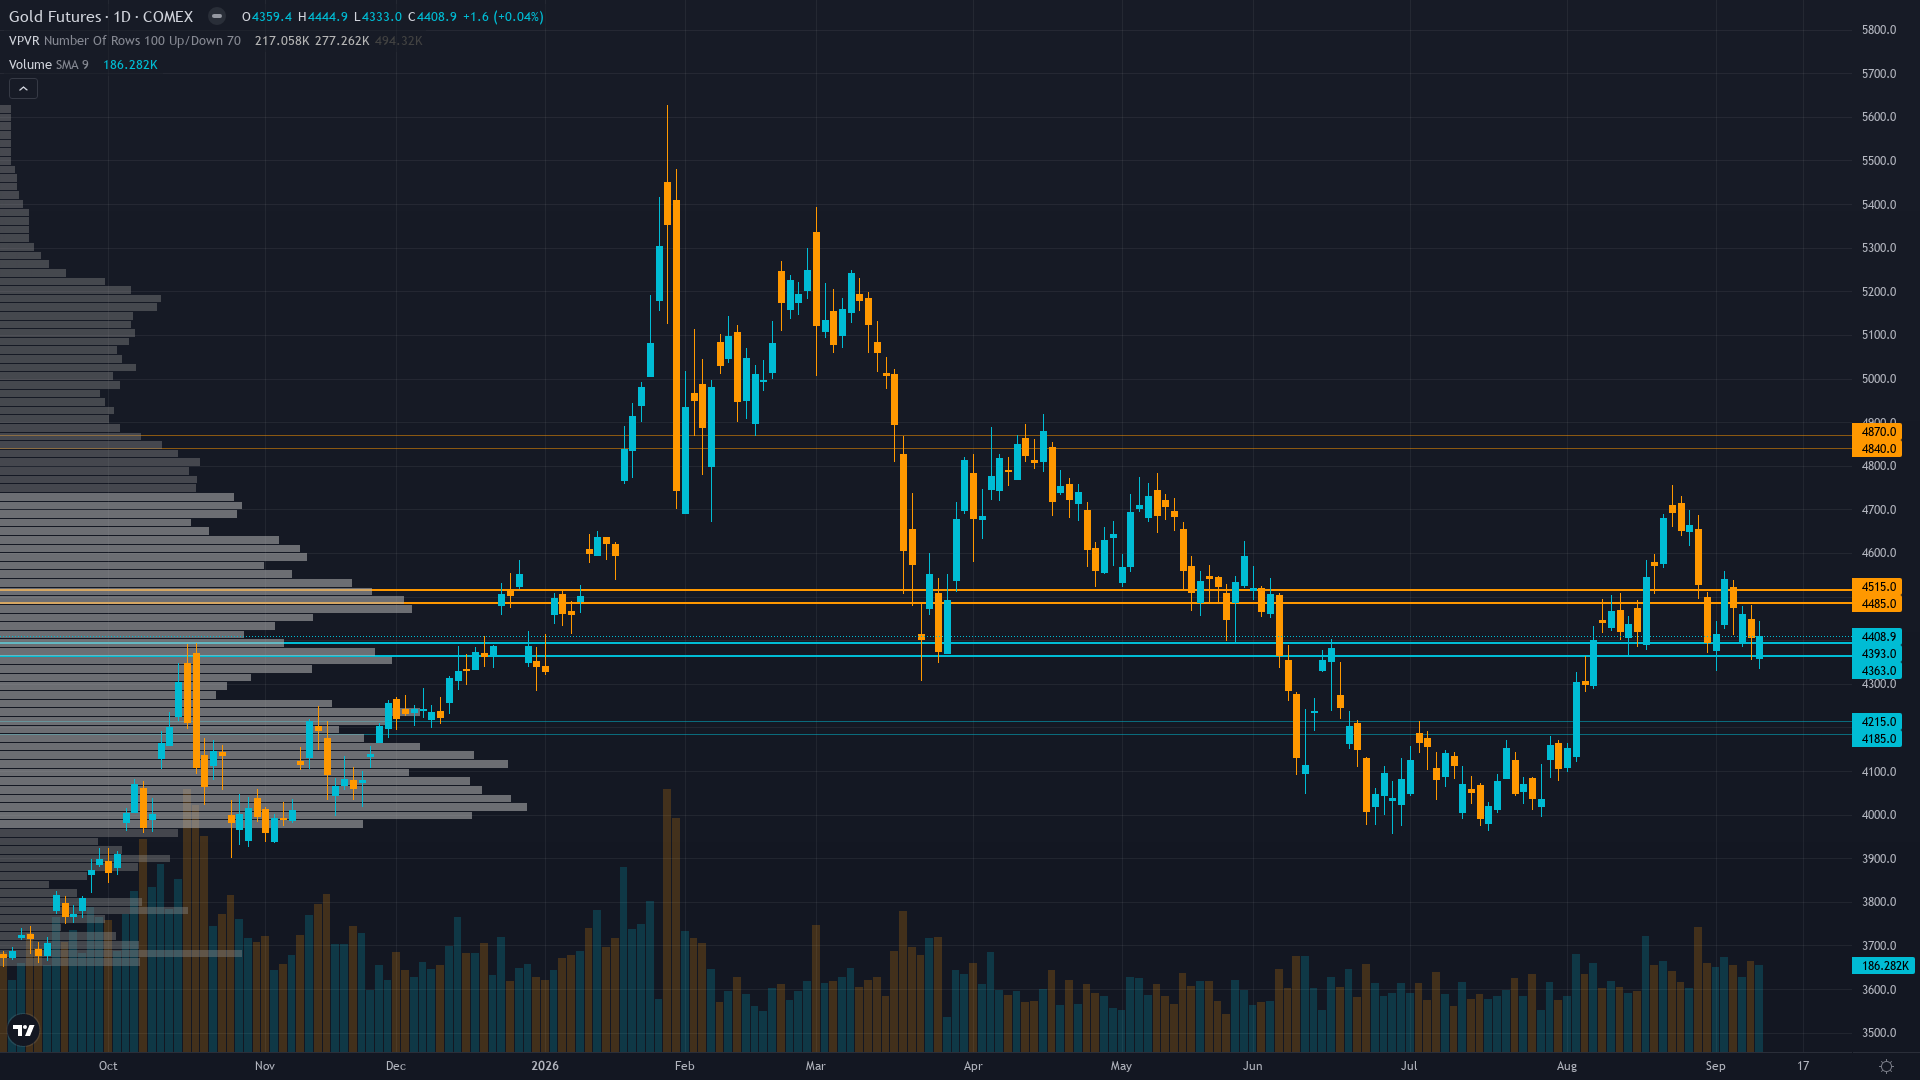
| ▼ Resistance Zone 2 | 4485 – 4535 |
| ▼ Resistance Zone 1 | 4375 – 4425 |
| ─ Pivot Area | ~4366 |
| ▲ Support Zone 1 | 4304 – 4354 |
| ▲ Support Zone 2 | 4175 – 4225 |
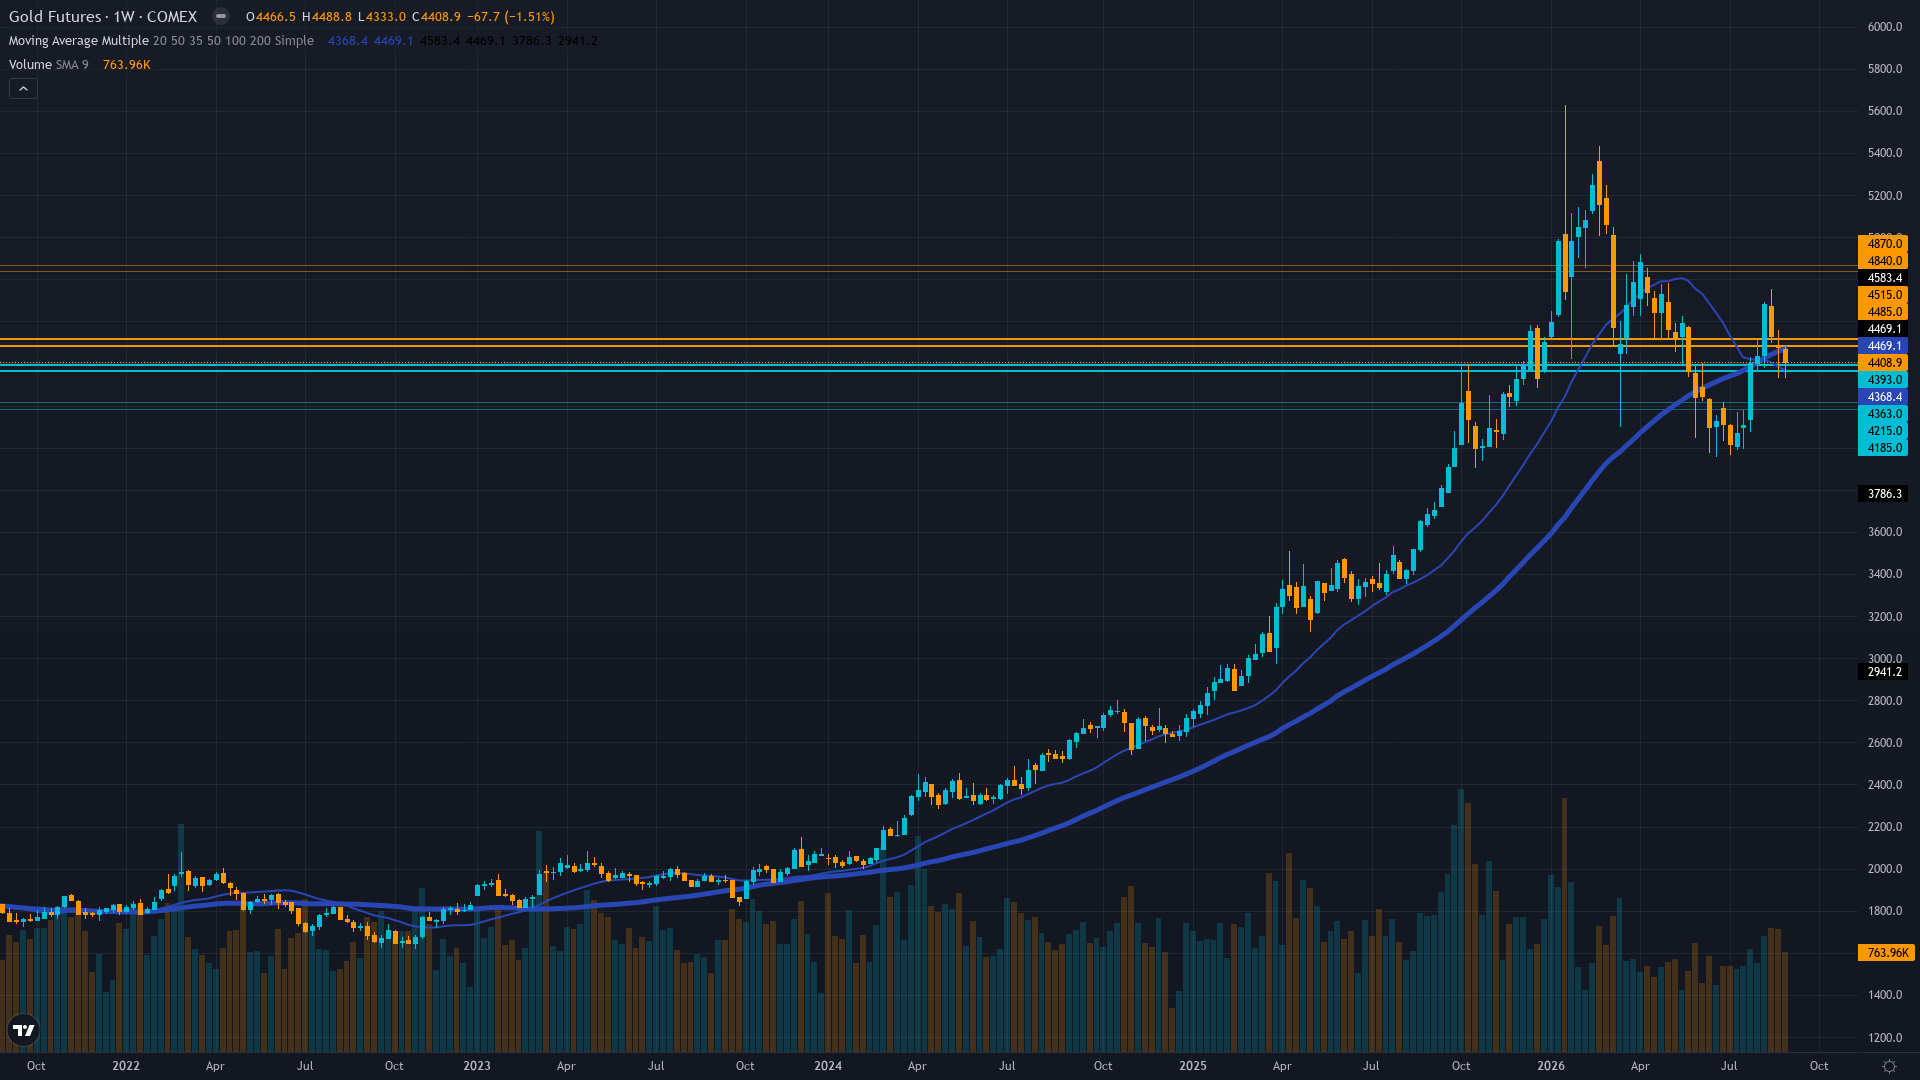
Price at $4,366 below both 50-day MA ($4,510) and 200-day MA ($4,638), consolidating in $4,329-$4,558 range with RSI approaching oversold; immediate support at $4,329 (Sep 2 low) is critical — a break below accelerates selling toward $4,200 major support
Gold appears 5-8% overvalued at $4,366 vs real yield models placing fair value at $4,000-$4,150; central bank demand (288.9t Q2, +62% y/y) provides a structural floor but is insufficient to offset the real yield headwind from 10Y at 4.96% without a fresh easing catalyst
Non-commercial net long at 231,960 contracts (63.3rd 3-year percentile) as of Sep 8 COT, up modestly +3,836 contracts but now at a level where contrarian risk of long liquidation is building if prices break lower; open interest at 411,227 remains healthy
No actionable implied volatility or put/call ratio data available this cycle; options market provides no directional signal, consistent with its confirming-only role in the precious metal framework
TRANSITIONAL-to-hawkish: Fed funds rate 3.63% with Sep 16 FOMC now carrying ~60% hike probability after hot Aug PPI; 10Y Treasury at 4.96% (+18bp weekly); inflation at 2.36% above target; DXY at 99.09 providing only mild offset; VIX at 15.84 signaling calm equities but that is not supporting gold in current real-yield-driven regime
Flat — short-term 22.5% aligned with medium-term 23.1% and long-term 22.0%, indicating stable volatility structure with no acute stress premiums as gold consolidates ahead of the FOMC binary event
Extended consolidation phases at the 65th percentile of normal volatility have historically resolved with an expansion spike around binary macro catalysts (FOMC meetings), with gold typically experiencing 2.0-3.5% daily ranges in the 48 hours following Fed decisions before reverting to trend
Volatility at 65th percentile in normal regime for an extended 70-day period; mean reversion toward the 22% median is likely over the next 2-4 weeks, with 55% probability of settling in the 20-23% range, though the Sep 16 FOMC could produce an expansion spike to 26-28% if the decision surprises
Normal volatility at 65th percentile supports 1.5-2.0% daily ranges — the $4,329 support and $4,400 resistance provide near-term trading levels with reasonable reliability, but the Sep 16 FOMC binary event increases false signal risk; breakouts may not sustain until after the catalyst resolves
Risk-reward is roughly balanced with a slight bearish skew ahead of FOMC: 1.5-2.5% downside risk to $4,329-$4,200 support versus 1.5-3.0% upside to $4,400-$4,500 resistance — the downside is more immediate given the hawkish PPI repricing and elevated COT positioning, but the September seasonal tailwind provides a structural bid that limits the bearish conviction
|
⚠️ Primary Risk
FOMC on Sep 16 delivers a hawkish surprise — either a 25bp rate hike or dot plot signaling additional tightening — that breaks gold below $4,329 support toward $4,200 as speculative long liquidation from the 63.3rd percentile COT positioning compounds the technical damage Probability: MEDIUM
|
✦ Primary Opportunity
FOMC delivers a dovish hold with reduced tightening bias, causing a sharp reversal of the post-PPI hawkish repricing and triggering a relief rally back toward $4,500 resistance as gold's September seasonal tailwind (+2.1% average, 64% positive years) provides multi-week structural support Timeframe: Next 1-2 weeks through the Sep 16 FOMC decision, with the potential for a catalyst-driven move of 2-4% in either direction depending on the outcome of the dot plot and forward guidance
|
MACRO REGIME CLASSIFICATION: TRANSITIONAL WITH HAWKISH LEAN. VIX at 15.84 signals benign equity risk appetite, yet gold faces its most significant headwind in months as the August PPI surprise (+0.4% MoM vs +0.3% expected, released September 10, 2026) repriced September FOMC hike odds from 31% to approximately 60%. The 10-year Treasury yield surged 18 basis points over the past week to 4.96%, the highest since the July 1 shock, directly pressuring gold's valuation framework. This week marks a decisive shift in the discipline consensus: all four usable agents have flipped BEARISH.
Fundamental (signal -1.5, conf 6) now sees gold as 5-8% overvalued against real yield models versus +1.2 bullish last week. Economic (signal -1.5, conf 6) flags the hawkish PPI surprise and the Sep 16 FOMC as the critical binary catalyst. Technical (signal -1.0, conf 6) shows price below both key moving averages consolidating in a $4,329-$4,558 range with vulnerability below the September 2 low. Institutional (signal -1.0, conf 6) notes the 63.3rd percentile COT positioning creates liquidation risk in a downside scenario.
Sentiment (-0.5, conf 4) and Options (0, conf 3) provide no counterweight. The primary edge this desk identifies is that market consensus remains structurally bullish ($4,500-$4,900 year-end targets from Goldman Sachs, JPMorgan, HSBC) while the near-term FOMC catalyst path is decisively hawkish — a divergence the hawkish PPI data has widened, not narrowed. Per the PRECIOUS_METAL behavioural override (Rule 6), flipping from BULLISH to BEARISH on a single counter-trend week would normally require restraint, but the PPI data represents a material hawkish catalyst shift across all discipline inputs that justifies the change.
The desk's measured BEARISH track record (-1.02R over 2 calls) warrants caution and the conviction penalty from the prior week's MISSED call limits confidence. The Sep 16 FOMC decision is the defining event — gold's September seasonal tailwind (+2.1% average) cannot overcome a hawkish Fed, but could amplify a dovish surprise. This is a FOMC binary week where positioning for either outcome with moderate conviction is appropriate rather than a strong directional lean.
| Week | Bias | Confidence | Result |
|---|---|---|---|
| September 11, 2026 | BULLISH | 6/10 | ❌ |
| September 4, 2026 | BULLISH | 5/10 | ✅ |
| August 28, 2026 | BULLISH | 7/10 | ❌ |
| August 21, 2026 | BULLISH | 7/10 | ✅ |
| August 14, 2026 | BULLISH | 7/10 | ✅ |
| August 7, 2026 | BULLISH | 6/10 | ✅ |
| July 31, 2026 | NO CALL | 5/10 | ➖ |
| July 24, 2026 | NO CALL | 5/10 | ➖ |
| July 17, 2026 | NO CALL | 5/10 | ➖ |
| July 10, 2026 | NO CALL | 5/10 | ➖ |
| July 3, 2026 | NO CALL | 5/10 | ➖ |
| June 19, 2026 | NO CALL | 5/10 | ➖ |
📋 PROMPT-READY CONTEXT
Copy this entire block into any AI chat for follow-up analysis
▼ Expand
MACRO AGENT DESK — WEEKLY INTELLIGENCE BRIEFING
═════════════════════════════════════════════════
Asset: Gold (GC)
Report Date: September 13, 2026

── DIRECTIONAL BIAS ─────────────────────────────
Call: NO CALL
Confidence: 5/10
Signal: NO DIRECTIONAL CALL THIS WEEK
MAD Index: 60 (DIVERGENCE)

── MARKET CONTEXT ───────────────────────────────
State: CONSOLIDATING
Regime: CONSOLIDATING WITHIN DOWNTREND
Sentiment: NEUTRAL

── WHAT THE MARKET SEES ─────────────────────────
Cautiously bullish on gold with institutional year-end targets at $4,500-$4,900, but near-term positioning increasingly defensive after the hot August PPI repriced FOMC hike odds to ~60% and drove 10Y yields to 4.96%, with the September 16 FOMC now the critical binary catalyst

── WHAT THE MARKET IS MISSING ───────────────────
The market may be underestimating how quickly the hawkish PPI repricing has shifted the FOMC outlook — hike odds surged from 31% to 60% in a single week, yet most institutional gold targets remain unchanged at $4,500-$4,900; combined with COT speculative positioning at the 63.3rd percentile creating liquidation vulnerability, the asymmetry favours a pre-FOMC bearish lean with the potential for a sharp reprice if the dot plot confirms a hawkish trajectory, though conviction is capped at 5 due to the prior week's missed BULLISH call and the desk's historically poor BEARISH track record on GC

── KEY DRIVERS ──────────────────────────────────
1. Hawkish FOMC repricing after August PPI surprise (+0.4% MoM vs +0.3% expected) drove September rate hike odds from 31% to 60%, with the September 16 FOMC decision and dot plot now the dominant binary catalyst for gold's near-term direction
2. Real yield surge: 10-year Treasury yield climbed 18bp in a week to 4.96%, the highest since the July 1 shock, directly pressuring gold's valuation framework which shows 5-8% overvaluation vs traditional real yield models
3. COT non-commercial net long at 231,960 contracts (63.3rd 3-year percentile) represents mildly elevated speculative positioning vulnerable to liquidation if the hawkish catalyst triggers a downside break below $4,329 support

── KEY ZONES ────────────────────────────────────
Resistance 2: 4485 – 4535
Resistance 1: 4375 – 4425
Pivot: ~4366
Support 1: 4304 – 4354
Support 2: 4175 – 4225

── DISCIPLINE BIASES ────────────────────────────
Technical: BEARISH
Fundamental: BEARISH
Institutional: BEARISH
Options: NO CALL
Economic: BEARISH
Sentiment: BEARISH

── TECHNICAL STRUCTURE ──────────────────────────
Price at $4,366 below both 50-day MA ($4,510) and 200-day MA ($4,638), consolidating in $4,329-$4,558 range with RSI approaching oversold; immediate support at $4,329 (Sep 2 low) is critical — a break below accelerates selling toward $4,200 major support

── FUNDAMENTAL ASSESSMENT ───────────────────────
Gold appears 5-8% overvalued at $4,366 vs real yield models placing fair value at $4,000-$4,150; central bank demand (288.9t Q2, +62% y/y) provides a structural floor but is insufficient to offset the real yield headwind from 10Y at 4.96% without a fresh easing catalyst

── INSTITUTIONAL POSITIONING ────────────────────
Non-commercial net long at 231,960 contracts (63.3rd 3-year percentile) as of Sep 8 COT, up modestly +3,836 contracts but now at a level where contrarian risk of long liquidation is building if prices break lower; open interest at 411,227 remains healthy

── OPTIONS FLOW ─────────────────────────────────
No actionable implied volatility or put/call ratio data available this cycle; options market provides no directional signal, consistent with its confirming-only role in the precious metal framework

── ECONOMIC BACKDROP ────────────────────────────
TRANSITIONAL-to-hawkish: Fed funds rate 3.63% with Sep 16 FOMC now carrying ~60% hike probability after hot Aug PPI; 10Y Treasury at 4.96% (+18bp weekly); inflation at 2.36% above target; DXY at 99.09 providing only mild offset; VIX at 15.84 signaling calm equities but that is not supporting gold in current real-yield-driven regime

── VOLATILITY REGIME ────────────────────────────
Regime: NORMAL
Percentile: 65th
Trend: Contracting ▼
Days in Regime: 70
Term Structure: flat — short-term 22.5% aligned with medium-term 23.1% and long-term 22.0%, indicating stable volatility structure with no acute stress premiums as gold consolidates ahead of the FOMC binary event
Historical Pattern: Extended consolidation phases at the 65th percentile of normal volatility have historically resolved with an expansion spike around binary macro catalysts (FOMC meetings), with gold typically experiencing 2.0-3.5% daily ranges in the 48 hours following Fed decisions before reverting to trend
Outlook: Volatility at 65th percentile in normal regime for an extended 70-day period; mean reversion toward the 22% median is likely over the next 2-4 weeks, with 55% probability of settling in the 20-23% range, though the Sep 16 FOMC could produce an expansion spike to 26-28% if the decision surprises
Trading Context: Normal volatility at 65th percentile supports 1.5-2.0% daily ranges — the $4,329 support and $4,400 resistance provide near-term trading levels with reasonable reliability, but the Sep 16 FOMC binary event increases false signal risk; breakouts may not sustain until after the catalyst resolves
Vol Risk/Opportunity: Risk-reward is roughly balanced with a slight bearish skew ahead of FOMC: 1.5-2.5% downside risk to $4,329-$4,200 support versus 1.5-3.0% upside to $4,400-$4,500 resistance — the downside is more immediate given the hawkish PPI repricing and elevated COT positioning, but the September seasonal tailwind provides a structural bid that limits the bearish conviction

── PRIMARY RISK ─────────────────────────────────
FOMC on Sep 16 delivers a hawkish surprise — either a 25bp rate hike or dot plot signaling additional tightening — that breaks gold below $4,329 support toward $4,200 as speculative long liquidation from the 63.3rd percentile COT positioning compounds the technical damage
Probability: MEDIUM

── PRIMARY OPPORTUNITY ──────────────────────────
FOMC delivers a dovish hold with reduced tightening bias, causing a sharp reversal of the post-PPI hawkish repricing and triggering a relief rally back toward $4,500 resistance as gold's September seasonal tailwind (+2.1% average, 64% positive years) provides multi-week structural support
Timeframe: Next 1-2 weeks through the Sep 16 FOMC decision, with the potential for a catalyst-driven move of 2-4% in either direction depending on the outcome of the dot plot and forward guidance

── NEXT CATALYST ────────────────────────────────
Date: September 15, 2026
Event: NY Empire State Manufacturing Index (Sep) — High impact; estimate 15 vs prior 20.6; first read on September economic activity
Expected Impact: MEDIUM

═════════════════════════════════════════════════
Source: Macro Agent Desk (macroagentdesk.com)
═════════════════════════════════════════════════

── FULL ANALYSIS ────────────────────────────────
MACRO REGIME CLASSIFICATION: TRANSITIONAL WITH HAWKISH LEAN. VIX at 15.84 signals benign equity risk appetite, yet gold faces its most significant headwind in months as the August PPI surprise (+0.4% MoM vs +0.3% expected, released September 10, 2026) repriced September FOMC hike odds from 31% to approximately 60%. The 10-year Treasury yield surged 18 basis points over the past week to 4.96%, the highest since the July 1 shock, directly pressuring gold's valuation framework. This week marks a decisive shift in the discipline consensus: all four usable agents have flipped BEARISH. Fundamental (signal -1.5, conf 6) now sees gold as 5-8% overvalued against real yield models versus +1.2 bullish last week. Economic (signal -1.5, conf 6) flags the hawkish PPI surprise and the Sep 16 FOMC as the critical binary catalyst. Technical (signal -1.0, conf 6) shows price below both key moving averages consolidating in a $4,329-$4,558 range with vulnerability below the September 2 low. Institutional (signal -1.0, conf 6) notes the 63.3rd percentile COT positioning creates liquidation risk in a downside scenario. Sentiment (-0.5, conf 4) and Options (0, conf 3) provide no counterweight. The primary edge this desk identifies is that market consensus remains structurally bullish ($4,500-$4,900 year-end targets from Goldman Sachs, JPMorgan, HSBC) while the near-term FOMC catalyst path is decisively hawkish — a divergence the hawkish PPI data has widened, not narrowed. Per the PRECIOUS_METAL behavioural override (Rule 6), flipping from BULLISH to BEARISH on a single counter-trend week would normally require restraint, but the PPI data represents a material hawkish catalyst shift across all discipline inputs that justifies the change. The desk's measured BEARISH track record (-1.02R over 2 calls) warrants caution and the conviction penalty from the prior week's MISSED call limits confidence. The Sep 16 FOMC decision is the defining event — gold's September seasonal tailwind (+2.1% average) cannot overcome a hawkish Fed, but could amplify a dovish surprise. This is a FOMC binary week where positioning for either outcome with moderate conviction is appropriate rather than a strong directional lean.