Japanese Yen Forecast This Week — Outlook, Drivers & Key Levels
This week's Japanese Yen outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Current Market Picture
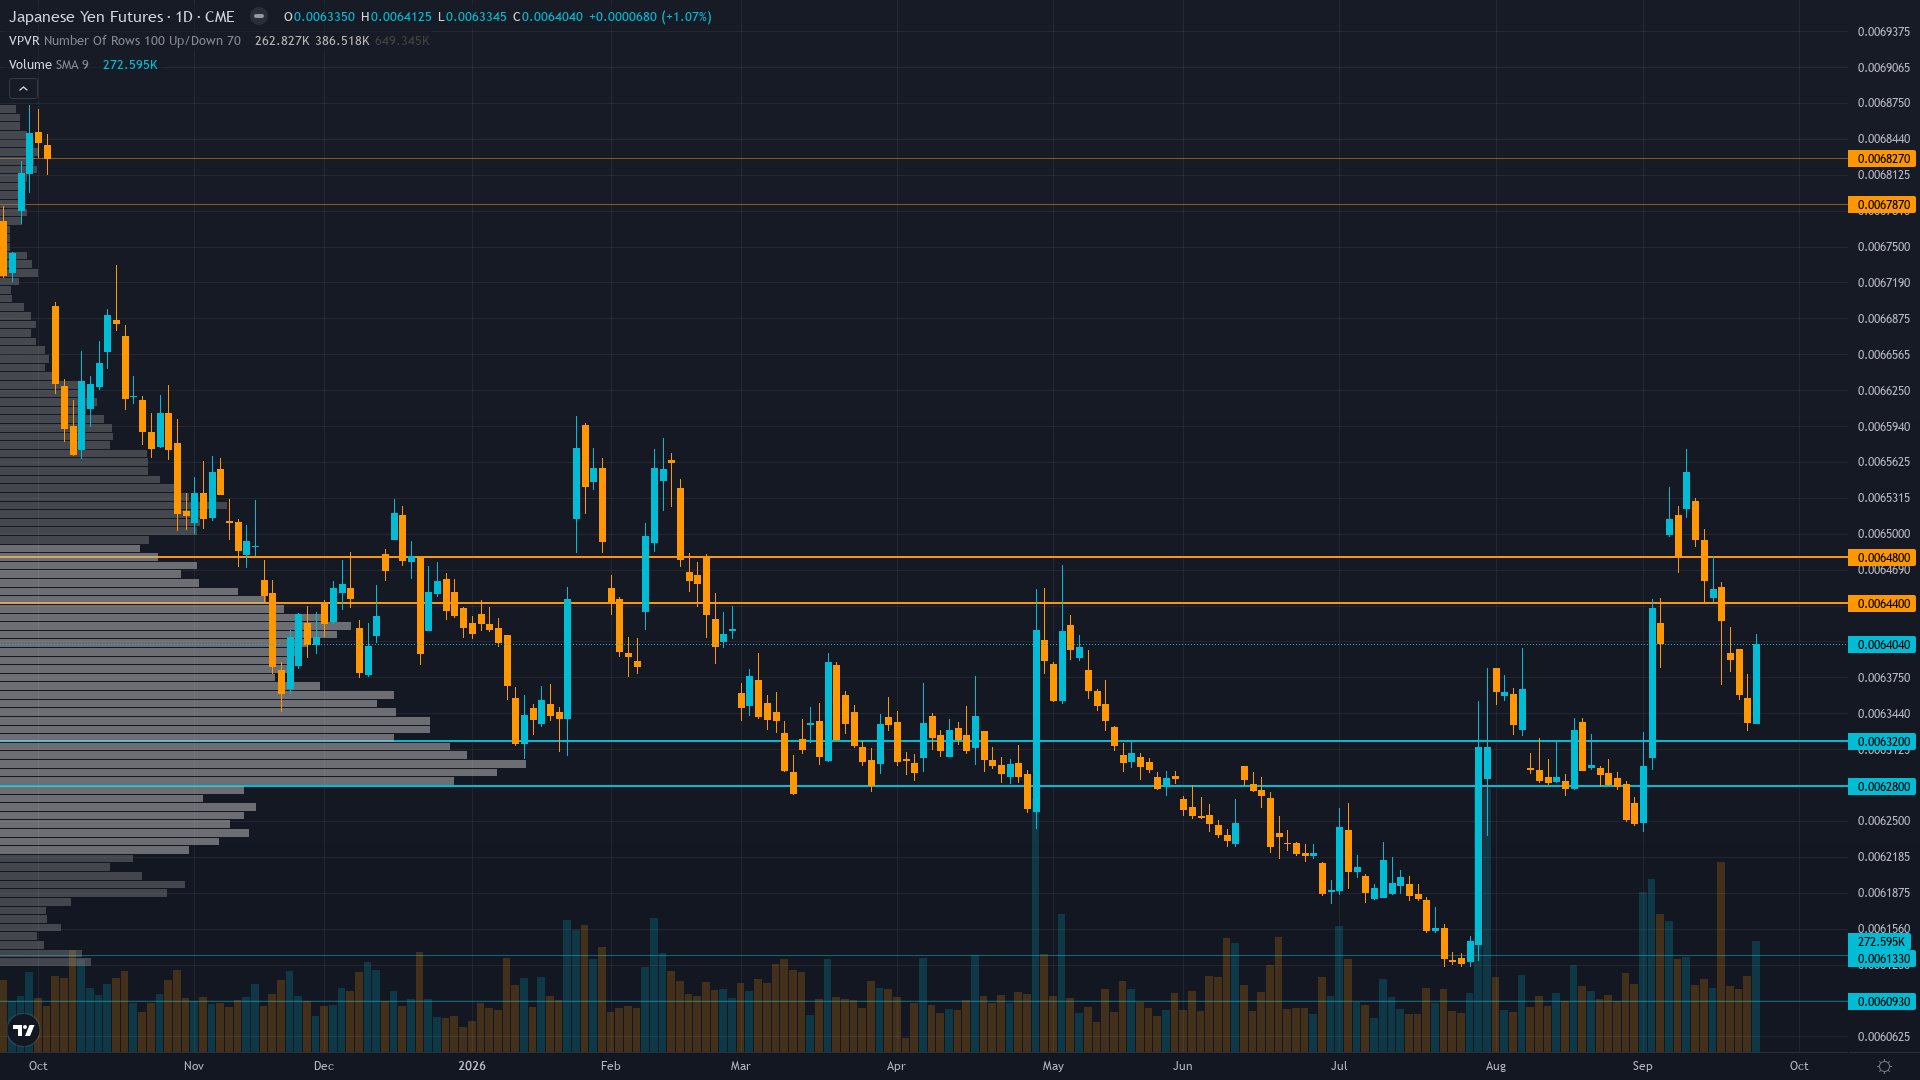
Japanese yen is trading at 0.006375, essentially flat as the market digests recent moves. The market in yen futures is coiling, with narrowing price ranges suggesting stored energy that will eventually release.
Market consolidating in 156-158 USD/JPY range post-BoJ sell-the-fact; speculative long positioning reduced from extremes but still elevated; consensus cautious on near-term yen direction awaiting Japan IP/retail sales and US Core PCE data this week
Key Drivers This Week
Primary driver: Post-catalyst digestion after BoJ September 18 rate hike to 1.25% produced sell-the-fact reversal from 0.0065 to 0.006375, with yen stabilizing in 156-158 USD/JPY range as market awaits next catalyst cycle
Secondary factor: CFTC COT September 22 shows non-commercial net long collapsing by -48,377 contracts to +71,982 (79.7th percentile) as speculative long positions liquidated after the BoJ delivery, reducing extreme crowding but still elevated
Additional influence: US Treasury 10Y yield rising 16bp week-over-week to 5.17% re-widening US-Japan rate differentials, reinforcing the structural carry headwind against yen strength despite BoJ rate hike to 1.25%
Economic backdrop: RISK-ON macro regime with VIX at 15.67 (below 20), US Treasury yields rising (10Y +16bp to 5.17%), Fed on hold at 3.63% with Core PCE due Sep 30 (est 0.3% MoM), BoJ Masu confirming continued rate hikes; risk appetite supportive of USD, headwind for safe-haven JPY
Fundamental assessment: JPY structurally undervalued ~12% on PPP (fair value ~93.7 USD/JPY vs current ~156.9) with Japan's record H1 2026 current account surplus ¥17.43T providing support, but BoJ catalyst delivered and rate differentials remain wide at ~380bp (Fed 3.63% vs BoJ 1.25%)
Price Structure
Price at 0.006375 at 37.8% of 52-week range, consolidating between 0.00625 support and 0.00645 resistance with neutral RSI; no clear directional bias — a textbook digestion range after the September 18 sell-the-fact reversal
Trend strength registers just 3/10, which typically corresponds to choppy, directionless price action.
Volatility Regime
Volatility for JPY is at the 52th percentile over 90 days — a normal regime that allows for standard position sizing and conventional trade management. The vol trend is flat, with no meaningful shift across timeframes. Stable vol environments often lull traders before a regime change arrives.
Normal vol regime suggests 50-65 pip daily ranges (0.00032-0.00042 in 6J terms); the post-catalyst environment reduces the probability of catalyst-driven spikes but elevated speculative positioning (79.7th percentile) creates potential for positioning-driven 80-100 pip days if data this week triggers stop-loss cascades
Bull & Bear Case
Primary risk: Extended positioning unwind continues — CFTC net long at +71,982 contracts (79.7th percentile) still elevated despite the -48K weekly reduction; further speculative liquidation could push 6J toward 0.00625 support if yen weakness persists and carry trade reasserts (Probability: medium)
Primary opportunity: Yen stabilization below 0.00645 finds support at 0.00625 with BoJ's continued rate hike trajectory (Masu hawkish guidance) providing a medium-term floor; the structural undervaluation thesis and current account surplus argue yen is cheap at these levels over a multi-month horizon (Timeframe: 1-2 weeks for catalyst delivery (Japan IP/RR Sep 29, Core PCE Sep 30), then reassess positioning)
This week's edge: Signal below Min Signal threshold (|signal| 0.26 < 1.1) — the weighted signal is too weak to support a directional bias. The CFTC COT data shows positioning normalization after the extreme +120K reading two weeks ago, now at +71,982 contracts (79.7th percentile), which is still elevated but no longer at contrarian extremes. The structural bull case (PPP undervaluation, BoJ trajectory, current account surplus) and the bearish near-term case (sell-the-fact momentum, wide rate differentials, elevated long positioning) are roughly balanced, producing no information edge for a clean directional call this week. Dense catalyst window this week (Japan IP/RR Sep 29, US Core PCE Sep 30) may provide the catalyst to break the range.
Week Ahead Outlook
Japan Industrial Production MoM (Aug) est 1.7% vs prev -0.2% and Retail Sales YoY (Aug) est 3.3% vs prev 4.0% — strong prints would support BoJ normalization narrative; weak prints would validate sell-the-fact yen weakness on Tuesday 29 September is the next scheduled catalyst, with moderate potential to influence near-term price action.
For yen, the balance between existing momentum and scheduled risk events sets the stage for the week ahead.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime