Soybeans Forecast This Week — Outlook, Drivers & Key Levels
This week's Soybeans outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
This Week's Starting Point
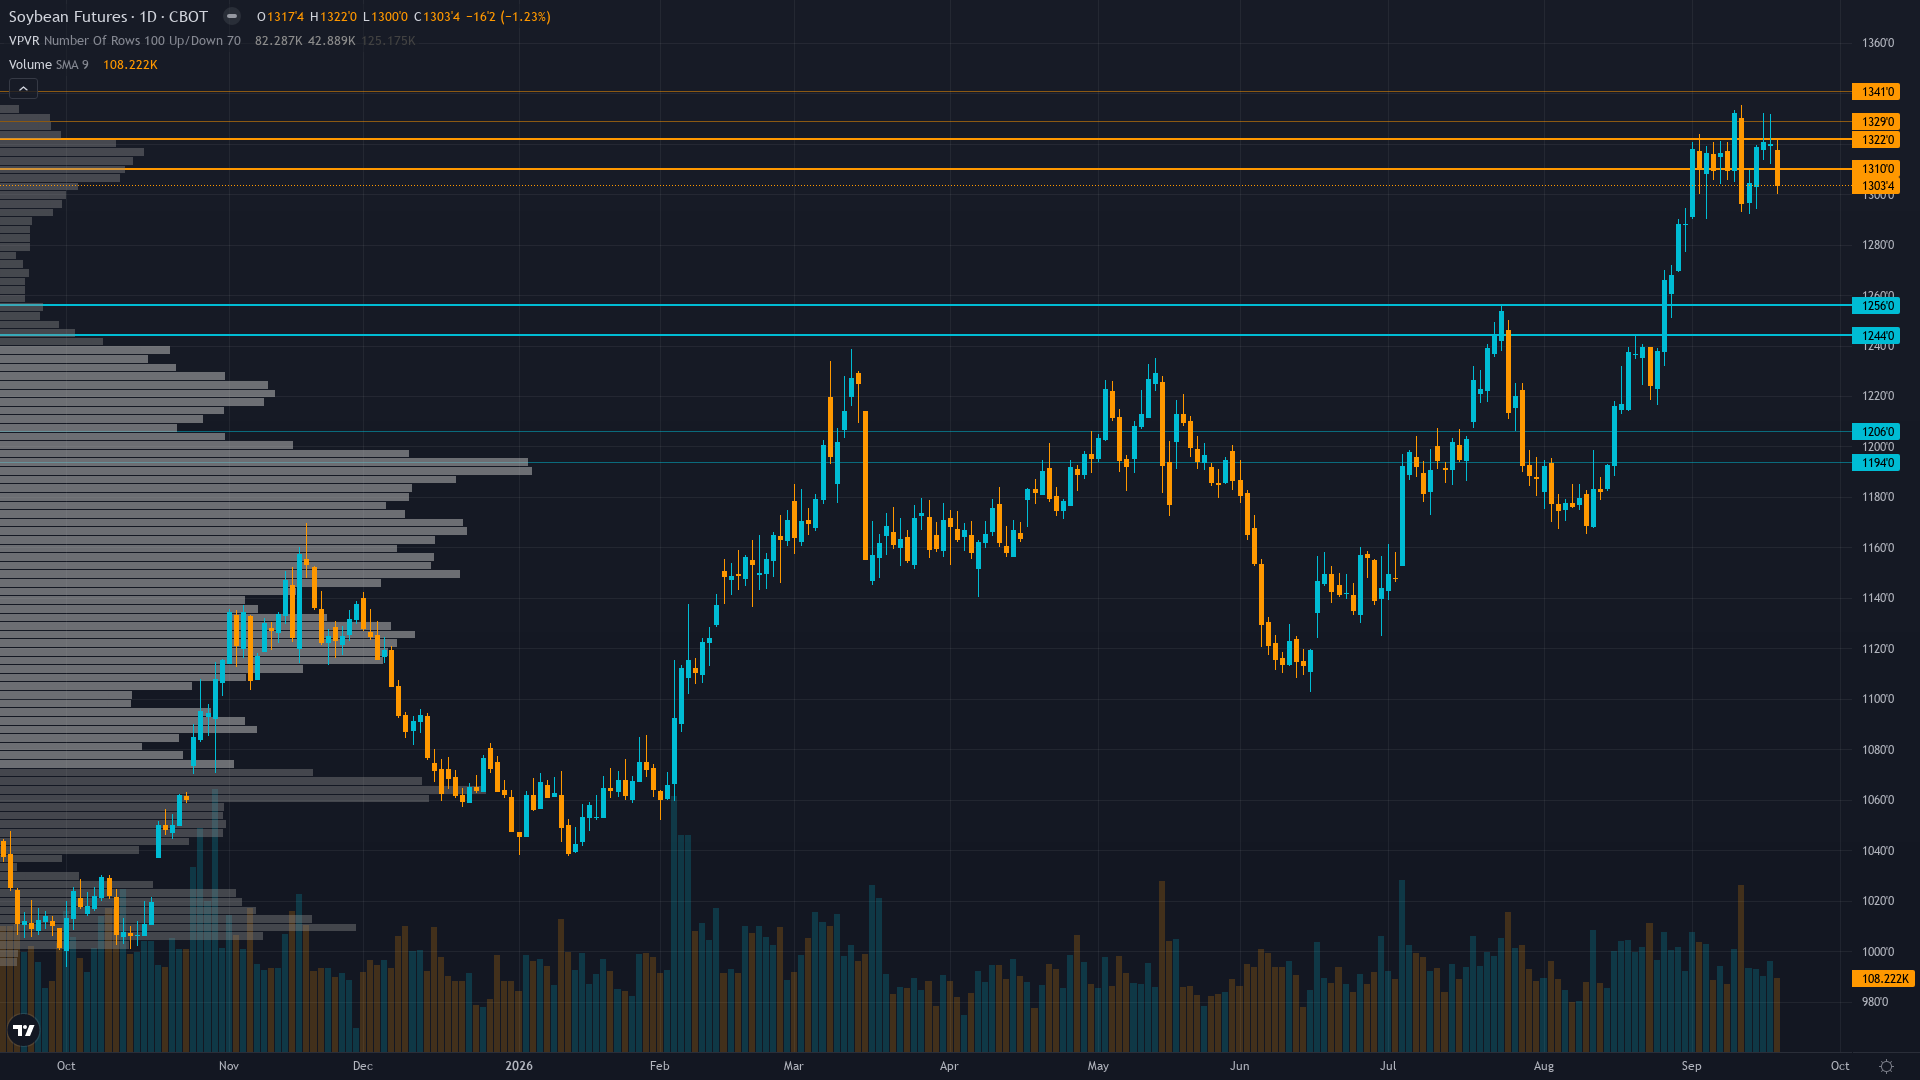
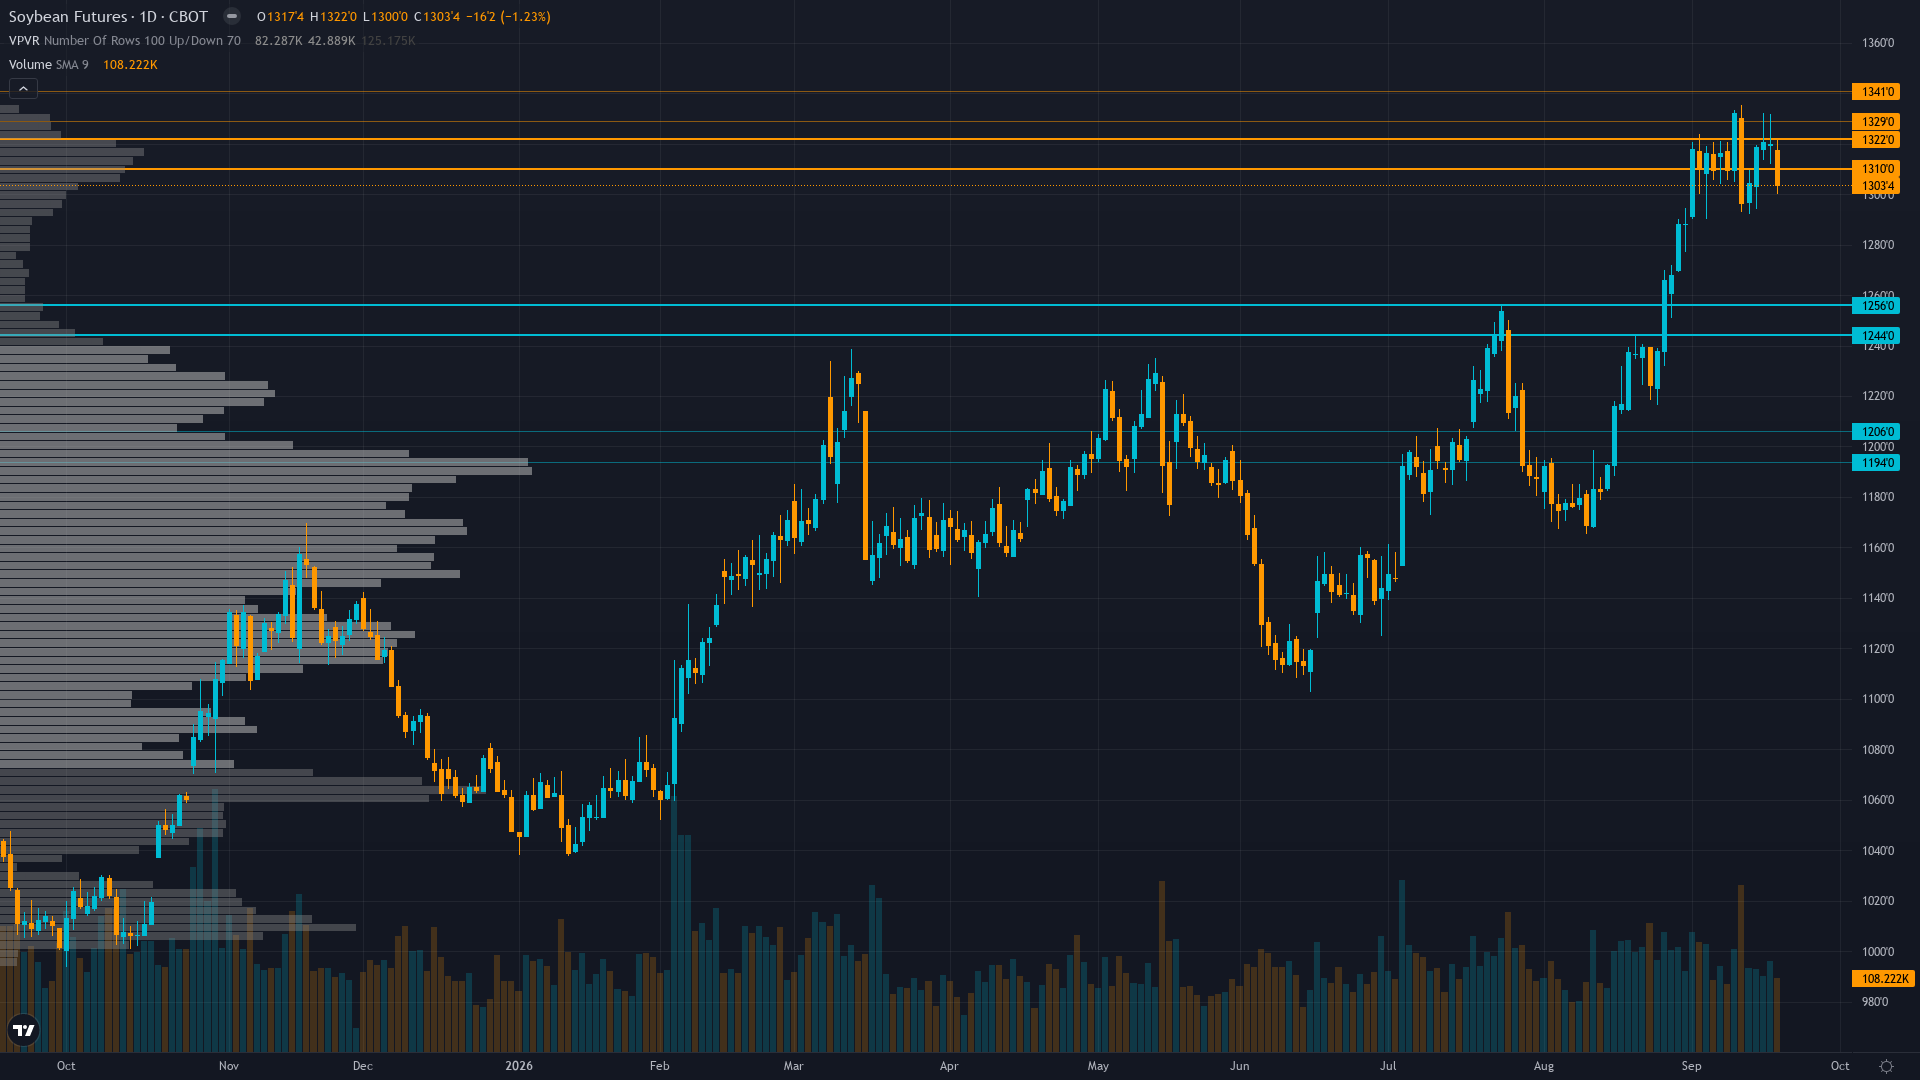
soybeans is trading at 1303.5, down 1.27% as selling pressure weighs on price. The trend for soybean futures is well-established, with momentum carrying price in a clear direction.
Market split between demand bulls citing 1 million tonnes of Chinese buying this week ahead of presidential meeting, and positioning bears warning that extreme 98.7th percentile speculative net longs are vulnerable to forced liquidation as harvest accelerates ahead of schedule and WASDE bearish surprise is not fully priced
Forces in Play
Primary driver: Extreme institutional positioning at 98.7th percentile of 3-year range with non-commercial net longs at 261,183 contracts as of September 15, 2026, representing acute vulnerability to forced liquidation as US harvest accelerates — soybean harvest reached 6% complete as of September 13, ahead of the 3% five-year average, and Chinese state buyers have purchased roughly 1 million tonnes this week ahead of a planned presidential meeting, creating a demand-side bid that is competing with supply-side harvest pressure and positioning risk
Secondary factor: September WASDE bearish surprise (yield raised to 52.8 bpa above trade expectations of 52.4, production at 4.535B bushels, ending stocks at 310M vs 290-298M consensus) broke the tight-supply narrative that drove the August rally, and the market has only partially digested this as price sits at 1303.5 just 1.3% below the 52-week high of 1320.5 despite the bearish supply data
Additional influence: Chinese buying surge of ~1 million tonnes this week (RiO Times September 19, 2026, citing Reuters) ahead of planned presidential meeting provides powerful demand-side support that has kept prices elevated despite bearish WASDE and harvest pressure, creating a fundamental tug-of-war between short-term demand support and medium-term supply expansion with harvest underway ahead of schedule
Economic backdrop: RISK-ON macro regime with VIX at 14.81 below 20 fear threshold, credit spreads tightening, equities trending higher; Fed funds at 3.63% with markets pricing gradual decline toward 3.25%; 10-year Treasury at 5.01% (up 5bp weekly) strengthening USD and creating export competitiveness headwinds for US soybeans against Brazilian competition; inflation at 2.33% contained but above target preventing dovish pivot
Fundamental assessment: Supply-side bearish from September WASDE showing higher production and ending stocks than expected, crop conditions at 58% G/E still below average but harvest results so far showing better-than-feared yields (Mississippi yields projected at 61 bpa vs 56 bpa in 2025 per USDA); renewable diesel structural demand at 2.78B bushels provides demand floor, but record Brazilian production at 180.4 MMT creates export competition overhang for 2026/27 marketing year
Technical Landscape
Price at 1303.5 at 94.7% of 52-week range, still in uptrend above 50-day MA (~1250) and 200-day MA (~1150), with RSI at ~60-65 showing continued bullish momentum without overbought conditions, but weekly price action shows Friday September 18 selloff of -1.04% to 1,303.50 after testing 1,319 area, and price has failed to break above 1320.5 resistance twice now, creating potential double-top pattern
Trend strength registers at 7/10, suggesting meaningful but not extreme directional bias.
Risk-Reward Assessment
Primary risk: Speculative long liquidation cascade from extreme 98.7th percentile positioning (261,183 contracts) as US harvest accelerates ahead of schedule — 6% harvested by September 13 vs 3% five-year average, and harvest typically peaks in October — combined with potential that WASDE bearish supply data has not been fully priced as the market remains focused on Chinese buying; if harvest yields confirm better-than-feared production (Mississippi 61 bpa vs 56 bpa last year), forced liquidation could drive a sharp correction toward 1250-1280 support representing 3-5% downside with cascading amplification from crowded long exit (Probability: medium)
Primary opportunity: Sustained Chinese buying momentum (roughly 1 million tonnes this week per Reuters) ahead of planned presidential meeting provides demand-side catalyst that could absorb harvest supplies and support prices near $13/bushel, while renewable diesel structural demand at 2.78B bushels provides fundamental floor; if harvest yields disappoint relative to WASDE estimates, or if Chinese buying continues at this pace, a break above 1320.5 resistance could drive a rally toward 1350 representing 3-4% upside (Timeframe: Next 1-3 weeks through September 30 Grain Stocks report and October 9 WASDE, with weekly export inspections and harvest progress releases providing incremental direction)
This week's edge: The market has not yet priced in the full implications of extreme institutional positioning at the 98.7th percentile (261,183 contracts non-commercial net long) now that September WASDE delivered bearish supply-side data across all six headline numbers above consensus, AND harvest is ahead of schedule at 6% vs 3% five-year average — while Chinese buying of 1 million tonnes this week provides near-term price support, the fundamental tension between short-term demand and medium-term supply/positioning risks creates an environment where the dominant move will likely be a correction once the Chinese buying catalyst fades, and the 1.78% price advance last week occurred on fund selling Friday despite the weekly gain, suggesting distribution underway below resistance at 1320.5
Risk Environment
With vol at the 65th percentile over 90 days, soybean price is in a measured regime that doesn't require unusual adjustments. Volatility is stable, with realised vol holding steady across timeframes. This equilibrium can persist but eventually resolves into expansion or contraction.
Current normal volatility at 65th percentile suggests 25-35 cent daily ranges expanding toward 40-55 cents as harvest and liquidation risk build; post-WASDE price discovery near 1300 with resistance at 1320.5 creates elevated false-breakout risk; standard stop placement widened to 30-40 cents; asymmetric gap risk on speculative liquidation cascade if 1280 support breaks
Looking Forward
All eyes turn to USDA Quarterly Grain Stocks report providing critical supply-side resolution on actual harvest quantities and on-farm stocks versus expectations, potentially confirming or contradicting the WASDE production estimate of 4.535B bushels on Wednesday 30 September, which carries enough weight to force a decisive directional move.
The week ahead for soybean futures hinges on whether the prevailing trending regime can absorb the scheduled catalysts without a regime shift.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime