Russell 2000 Forecast This Week — Outlook, Drivers & Key Levels
This week's Russell 2000 outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Where Things Stand
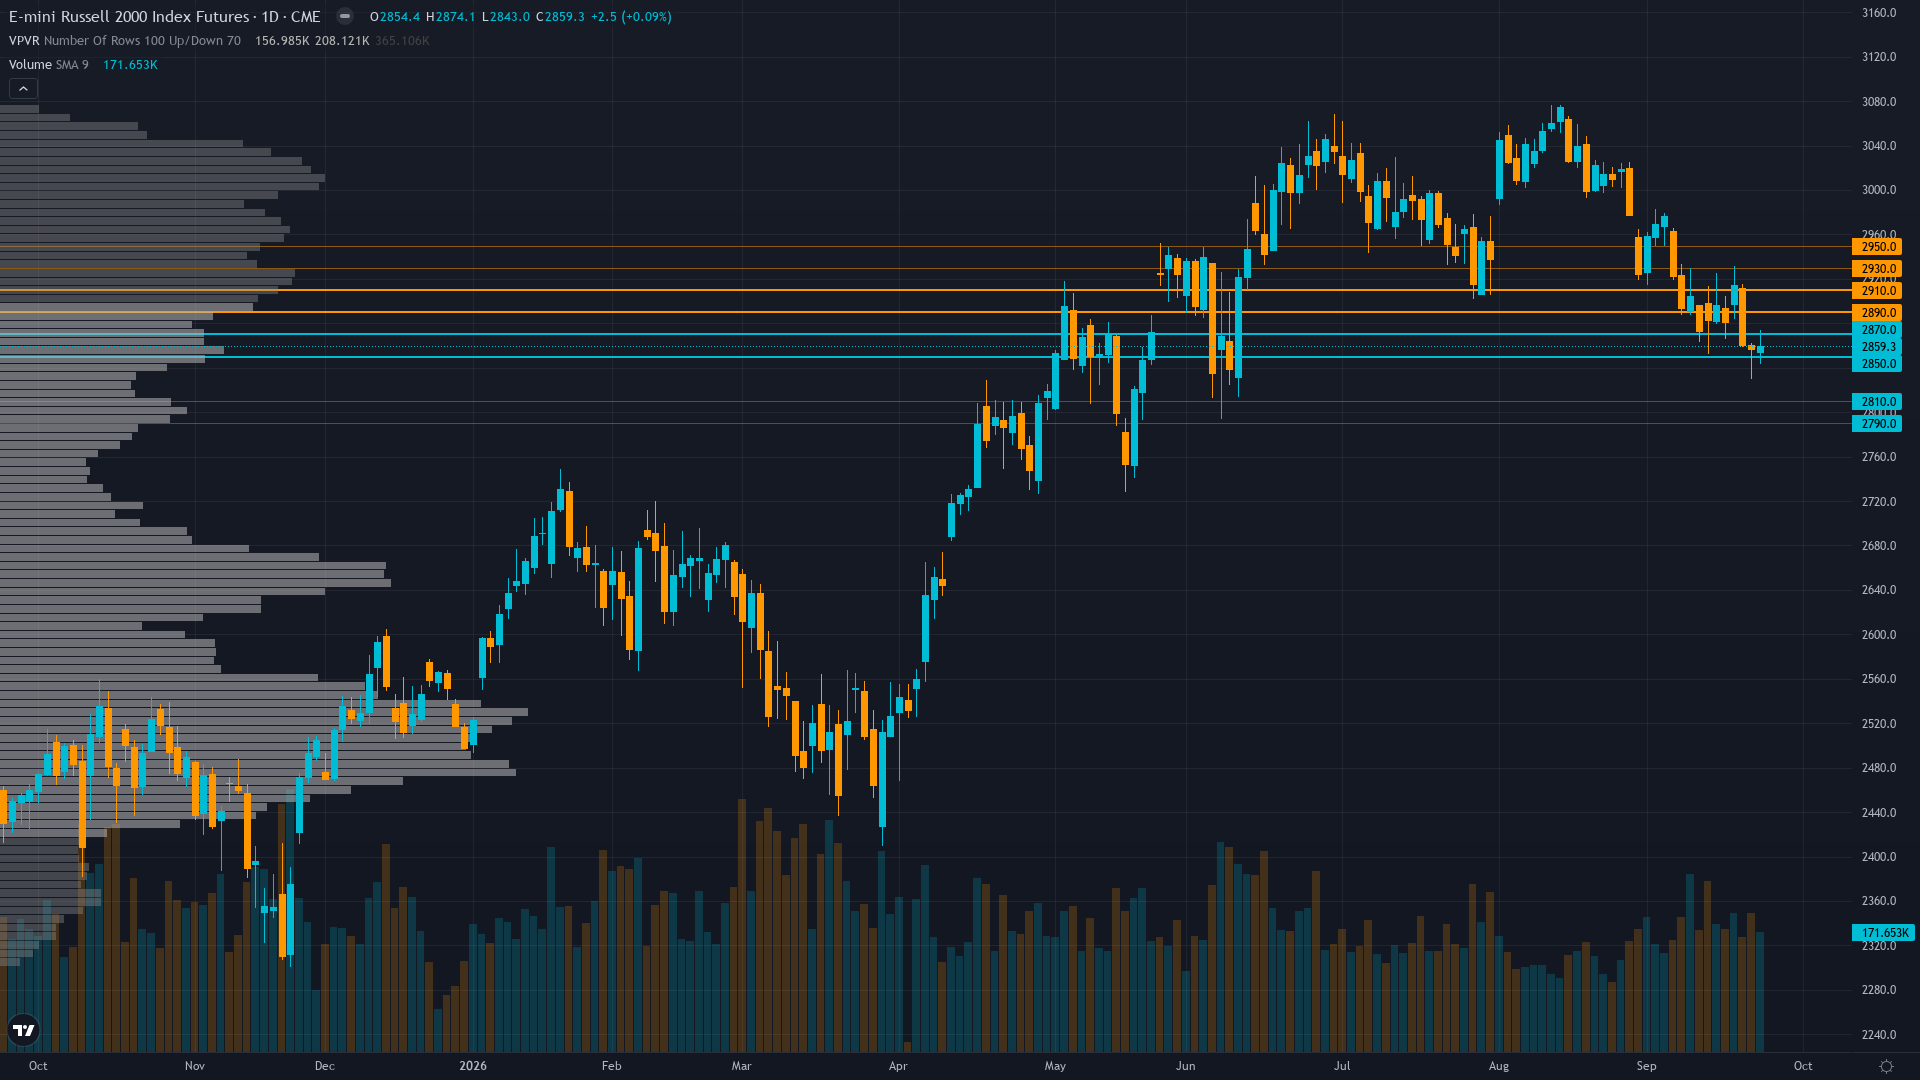
Trading at 2859.3 with a 0.28% dip, Russell 2000 is giving back ground gradually. Russell 2000 futures is in a breaking down market state, requiring careful assessment of current conditions.
Small-caps in an accelerating downtrend with sustained breakdown below 2900, driven by rising rates at 5.17% and widening credit spreads, though extreme speculative short positioning at the 3.8th percentile creates a squeeze setup that early covering activity (-3,433 contracts) has not yet overwhelmed
Risk-Reward Assessment
Primary risk: Further technical breakdown below 200-day MA at 2825 accelerating toward 2750 major support as 10Y yields at 5.17% continue rising on hawkish Fed repricing and September-October seasonal headwinds compound the small-cap decline — the extreme COT positioning at 3.8th percentile is insufficient to prevent further selling if fundamental pressures (rising rates, widening credit spreads, weak consumer sentiment) intensify, with RTY already down 7% from ATH and showing no signs of stabilization in the daily trend structure (Probability: high)
Primary opportunity: The extreme speculative net short at -75,783 contracts (3.8th percentile) combined with RSI oversold at ~34 creates asymmetric squeeze potential if the Sep 29 economic data (Consumer Confidence, JOLTs) surprises to the upside or Fed speeches signal a dovish tilt — with shorts having already begun reducing (-3,433 contracts), the setup for a violent short-covering rally targeting 2900-2960 resistance is mathematically primed, and the 34.5% valuation discount to large caps provides fundamental support for a mean-reversion bounce that consensus bearish positioning has not priced (Timeframe: 1-2 weeks through Sep 29 consumer confidence and JOLTs catalyst resolution and into early October)
This week's edge: The market consensus is pricing a linear continuation of the small-cap selloff driven by rising yields and widening credit spreads, but may be underappreciating that the speculative net short at the 3.8th percentile of the 3-year range represents one of the most extreme bearish positioning readings in the data history — shorts have reduced by -3,433 contracts for two consecutive weeks (from -82,835 to -75,783), signaling that smart money is beginning to cover even as price declines, which historically precedes violent squeezes when a benign catalyst emerges; the desk recognizes this squeeze setup is building under the surface but the current fundamental headwinds (5.17% 10Y, widening HY spreads, depressed consumer sentiment at 51.7, September-October seasonal weakness) are powerful enough that fading the downtrend without a specific catalyst trigger remains unreliable, making this a measured bearish continuation call at reduced conviction rather than an aggressive short
Forces in Play
Primary driver: Sustained technical breakdown below 2900 psychological support with RTY at 2859.3, down -5.01% for September and -0.48% this past week, driven by 10Y Treasury yields surging to 5.17% (+16bp in 1W) — the highest since the late-August hawkish Jackson Hole repricing — creating acute headwinds for credit-sensitive small-cap balance sheets carrying floating-rate debt, with the 2s10s curve at +36bp confirming the steepening yield environment that is structurally negative for RTY as a credit instrument per Section 3 asset-specific context
Secondary factor: CFTC COT data as of 2026-09-22 shows non-commercial speculators net short -75,783 contracts (3.8th percentile of 3-year range, -18.3% of OI), remaining at extreme bearish levels despite reducing shorts by -3,433 contracts week-over-week — positioning is at the 3.8th percentile, near the lowest third of the historical range, meaning speculative shorts have been this extended only 3.8% of the time over three years, creating a massive contrarian squeeze setup that is mathematically the most powerful bullish catalyst in the data set, but price continues to make new lows as fundamental selling pressure (rising yields, hawkish Fed repricing, September seasonality, deteriorating consumer sentiment at 51.7) overwhelms the early covering dynamics
Additional influence: High-yield credit spreads widening to 266-280 bps OAS as of September 21-24 from 276 bps a week earlier (FRED BAMLH0A0HYM2 and StreetStats), confirming credit stress is increasing for the floating-rate-debt-heavy small-cap segment — the HY spread is now at its widest in over a month, directly pressuring RTY as a credit instrument where 40% of constituents carry floating-rate debt and approximately 31% of EBITDA goes to interest expense, with the approaching week's catalysts on Sep 29 (JOLTs Job Openings at 14:00 EST, CB Consumer Confidence at 14:00 EST, and multiple Fed speeches including Williams, Waller, Goolsbee) providing the next directional tests of whether the economy can sustain current growth without forcing further Fed tightening
Economic backdrop: RISK-OFF: RTY down 5.01% MTD with realized vol at 12.6%, Fed funds at 3.63% with markets pricing potential rate hike to 3.75-4.00%, 10Y yields at 5.17% (+16bp in 1W), HY credit spreads widening to 266-280 bps, consumer sentiment deeply depressed at 51.7, inflation at 2.34% still above 2% target, unemployment at 4.1% stable — the combination of rising yields, weak consumer confidence, and tightening credit conditions is uniquely problematic for domestic-demand-driven small-cap earnings
Fundamental assessment: Forward P/E of 19.21x represents a 34.5% discount to the Russell 1000's 29.32x (Siblis Research January 2026), providing relative value support, but the small-cap earnings delivery risk is heightened with consensus projecting 43% YoY growth that faces elevated headwinds from rising 10Y yields at 5.17%, depressed consumer sentiment at 51.7, and the smoothed US recession probability at 0.76% — the earnings bar is high and the probability of disappointment is rising
Technical Landscape
Confirmed bearish downtrend with price at 2859.3 trading decisively below both the 50-day MA (~2900) and 200-day MA (~2825), RSI at ~34 in oversold territory but without bullish divergence, MACD negative confirming bearish momentum, having broken below 2900 psychological support — the index has printed lower highs and lower lows since the Aug 14 ATH at 3074.9, now -7.0% from that peak and -11.4% from the June 25 record, with the 200-day MA at 2825 as the final support before a potential move toward 2750 major support
Trend strength registers at 7/10, suggesting meaningful but not extreme directional bias.
Volatility Backdrop
RTY futures volatility at the 62th percentile reflects a balanced environment where standard risk parameters apply. Volatility remains anchored at current levels, with no clear signal of an imminent regime shift in either direction.
Normal volatility regime at 62nd percentile supports standard risk management with stop placement near 2,800 below 200-day MA support, expect 40-65 point daily ranges expanding to 65-85 on Sep 29 catalyst day, the stable vol structure and extreme net short positioning signal building tension that could resolve with a sharp directional move on the Sep 29 data cluster — range-trading between 2,825-2,900 with defined boundaries preferred until JOLTs and Consumer Confidence data provide directional clarity, though the breakdown structure favors bearish positioning with tight stops
Historical Seasonal Bias
Seasonal patterns flag a bearish tendency for small-cap futures in September 2026 (40% win rate). September is historically weakest month.
What to Watch
The CB Consumer Confidence (Sep) consensus 90 vs prior 89.4 and JOLTs Job Openings (Aug) consensus 7.23M vs prior 7.271M — both at 14:00 EST, followed by multiple Fed speeches (Bowman, Goolsbee, Williams, Waller, Musalem) creating a dense catalyst day that will test whether economic momentum is deteriorating enough to shift Fed posture on Tuesday 29 September stands as the week's primary risk event — high-impact and capable of overriding the existing technical and sentiment setup.
The interplay between breaking down market conditions and upcoming catalysts will define this week's trading landscape for Russell index.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime