Russell 2000 COT & Institutional Positioning — Smart Money Analysis
Russell 2000 institutional positioning: COT data, sentiment analysis and smart money flow assessment.

Where Institutions Stand
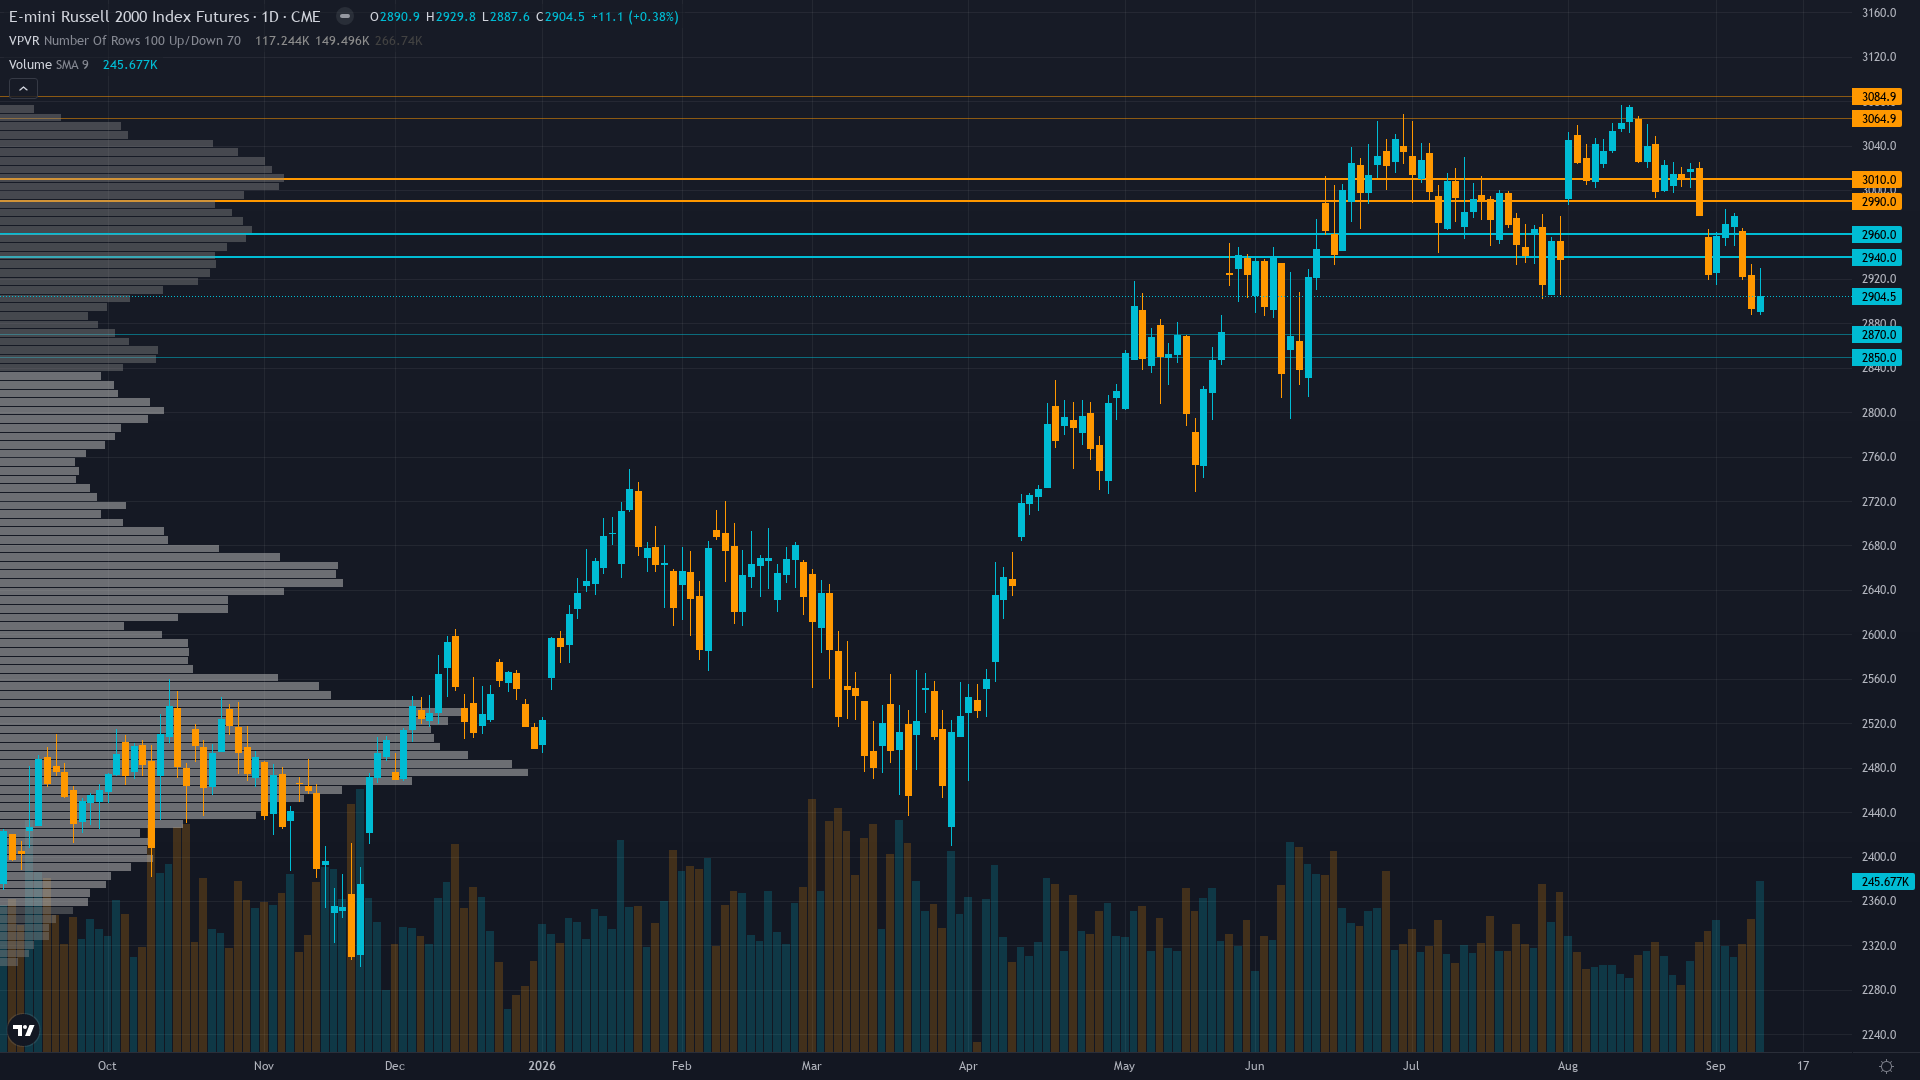
At 2904.5, Russell 2000 has inched 0.38% higher in a measured advance.
Non-commercial net short -82,835 contracts as of Sept 8 (1.9th percentile of 3-year range, -19.2% of OI), with -11,172 added shorts week-over-week — the most aggressive speculative short positioning in the data history, representing a 3-year extreme that has historically preceded violent mean-reversion squeezes when a benign catalyst emerges
Consensus vs MAD View
Market consensus: Small-caps in an accelerating downtrend after breaking below August consolidation support, with market pricing rising rates and FOMC hawkish risk into September seasonal headwinds, while extreme speculative short positioning at 1.9th percentile creates latent squeeze risk that has not yet materialized
Primary driver: COT speculative net short positioned at -82,835 contracts (1.9th percentile of 3-year range, -19.2% of OI) — the most extreme bearish positioning in over 3 years, having added -11,172 contracts of short exposure even as the index has already corrected -5.5% from the Aug 14 ATH at 3,074.9, creating an unprecedented squeeze setup ahead of the Sept 16 FOMC Economic Projections binary catalyst
Where the Crowd May Be Wrong
The desk sees moderate divergence from consensus: the market is aggressively short RTY with speculative net shorts at the 1.9th percentile of the 3-year range (-82,835 contracts), pricing continued downside into the FOMC catalyst, while the desk acknowledges this positioning represents an historically extreme contrarian squeeze setup that consensus bearish positioning has not priced as a risk, but the neutral bias and thesis degradation from two consecutive missed calls cap the MAD score at 40 per the neutral-bias integrity rule
Crowd Psychology
Neither side has committed heavily to Russell 2000 futures, leaving sentiment in a neutral zone that offers little directional guidance on its own.
Options Flow
RTY options implied volatility around 16.95% (per Barchart Sept 2026 data) with VIX at 15.84, RVX (Russell 2000 vol index) at approximately 19.98 indicating elevated small-cap-specific fear relative to broad market VIX — the vol term structure shows short-dated elevated expectations ahead of the Sept 16 FOMC binary catalyst, creating asymmetric positioning for volatility expansion on the resolution
The Bottom Line on Positioning
The positioning mosaic for Russell index combines fear sentiment with stable volatility conditions. Trend strength is low at 3/10, indicating weak directional conviction and potential for range-bound behaviour. Taken together, institutional behaviour, crowd psychology, and derivatives data frame the setup heading into the new week.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime


