Platinum Forecast This Week — Outlook, Drivers & Key Levels
This week's Platinum outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Market Overview
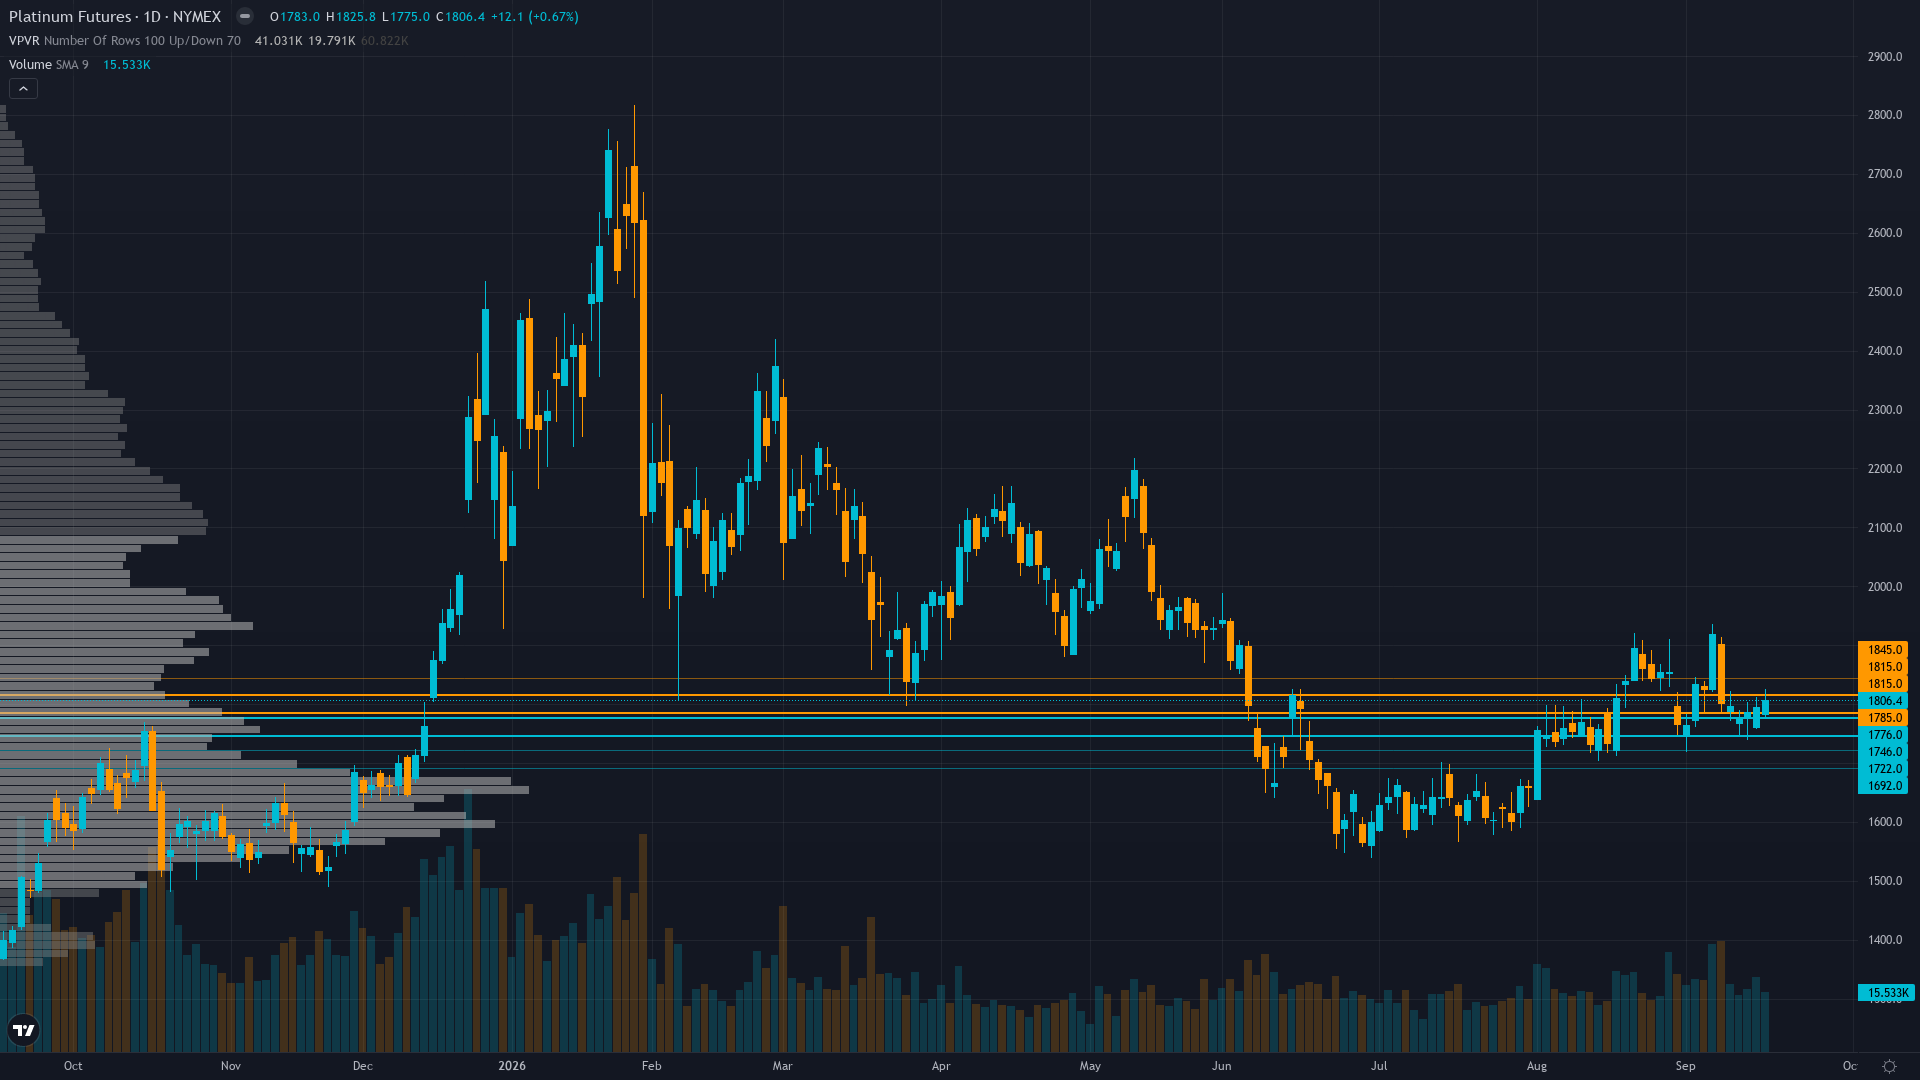
Trading at 1803.5 with a 0.67% uptick, platinum is drifting higher without strong conviction. platinum futures is range-bound and tightening, with decreasing volatility signalling a directional resolution ahead.
Market stabilising after September 16 FOMC rate hike and WPIC surplus revision from 297koz deficit to 265koz surplus, consolidating in $1,761-$1,825 range with no clear directional catalyst ahead of September 23 PMI data and the next WPIC Quarterly on November 18
This Week's Catalysts & Drivers
Primary driver: Post-FOMC digestion after the September 16, 2026 rate hike to 3.75-4.00% has removed the binary catalyst uncertainty that dominated the prior two weeks, but the hawkish outcome has reset the macro landscape for precious metals; platinum has stabilised at $1,803.50 (+0.7% weekly) as the market absorbs higher real yields against a fundamentally altered WPIC surplus forecast of 265koz versus the prior 297koz deficit thesis
Secondary factor: WPIC's September 10, 2026 forecast revision from 297koz deficit to 265koz surplus (first annual surplus since 2022) represents a 562koz swing in the fundamental narrative, materially weakening the structural scarcity thesis that underpinned the August BULLISH calls; the Fundamental discipline now rates conviction at 7 with signal +1.2, down from +2.5 in early September, acknowledging the surplus reality while pointing to hydrogen demand and SA supply constraints as residual support
Additional influence: Non-commercial net long positioning at 15,220 contracts as of CFTC COT September 15, 2026 (46.2nd percentile of 3-year range) decreased by 756 contracts weekly, with institutional rotation out of platinum exposure accelerating via ETF outflows (WPIC forecasts 83koz of net disinvestment in September alone), creating a subtle but persistent headwind that the consolidation phase is absorbing
Economic backdrop: TRANSITIONAL macro regime: Fed raised rates 25bps to 3.75-4.00% on September 16 (3 days ago), VIX at 14.88 signals neutral risk appetite with low volatility, 10Y yield at 5.01% elevated, 2s10s curve at 25bp, inflation at 2.33% persistent but not accelerating; the hawkish FOMC outcome creates a structurally higher real yield environment that pressures non-yielding precious metals, though the market had largely priced this in per the 80% Polymarket probability preceding the decision
Fundamental assessment: The WPIC September 10 surplus revision to 265koz (first surplus since 2022, a 562koz swing from the prior 297koz deficit forecast) has fundamentally altered the supply-demand narrative; the structural deficit thesis is no longer intact for 2026. South African supply constraints (projected 3.695Moz vs 3.820Moz in 2025) and hydrogen fuel cell demand growth (300koz annually) provide residual support, but the immediate catalyst for higher prices has been removed by the surplus forecast and continued ETF disinvestment of 83koz in September
Technical Picture
Sideways consolidation between $1,761 and $1,825 with RSI neutral and volume thinning, price at $1,803.50 positioned in the lower 27.1% of the 52-week range ($1,414-$2,852), holding above the 50-day EMA at $1,707 but failing to challenge the $1,825 swing high, reflecting a market in equilibrium after the FOMC catalyst passed without triggering a breakdown or breakout
At 3/10, trend strength is subdued, suggesting the market lacks a clear directional mandate.
Risk Environment
With vol at the 42th percentile over 90 days, platinum price is in a measured regime that doesn't require unusual adjustments. Volatility is stable, with realised vol holding steady across timeframes. This equilibrium can persist but eventually resolves into expansion or contraction.
Normal but compressed vol regime suggests daily ranges of $30-45 versus the $50-70 seen during the August breakout and $80-120 during Q2 breakdown; the consolidation between $1,761 and $1,825 has narrowed the likely range to $30-45/day; stops placed tighter than $25 risk noise-triggering given PL's 7.24% average weekly move class characteristic
Risk-Reward Assessment
Primary risk: Continued institutional liquidation via ETF outflows (83koz forecast for September) could accelerate if PMI data on September 23 disappoints, potentially triggering a breakdown below $1,761 support toward $1,707 (50-day EMA) and $1,650 major support, as the surplus forecast removes the fundamental buying conviction that has supported dips through August and early September (Probability: medium)
Primary opportunity: The FOMC catalyst has passed and the market is stabilising, with the WPIC surplus forecast already priced into current levels near $1,800; if the November 18 WPIC Quarterly report reveals a tightening from the 265koz surplus estimate or if South African power disruptions intensify, the fundamental narrative could shift back toward deficit territory, enabling a recovery toward $1,900 resistance over a 4-8 week horizon (Timeframe: 4-8 weeks contingent on sustained hold above $1,761 support and the November 18 WPIC Q4 2026 report confirming tighter balance than the September surplus projection)
This week's edge: Below noise threshold — range-bound assessment. The market is correctly pricing the post-FOMC, post-WPIC-surplus environment with no material information edge available this week. The FOMC catalyst has passed as expected (25bps hike), the WPIC surplus revision has been absorbed over the past 10 days, institutional positioning is mid-range with manageable liquidation rather than capitulation, and the 0.7% weekly move is well below platinum's 7.24% average weekly move class characteristic. No fresh catalyst exists to produce a move above the noise threshold through the upcoming PMI data (medium impact). The next material catalyst is the November 18 WPIC Quarterly report, which is 9 weeks forward.
What to Watch
S&P Global Manufacturing PMI (Sep) — consensus 53.6 vs prior 53.9; a resilient print would support platinum's industrial demand case (50% of total demand), while a below-50 contraction would introduce growth concern headwinds for the dual-identity precious metal (Wednesday 23 September) sits in the medium-impact category — unlikely to single-handedly shift the picture, but capable of adding directional fuel.
The interplay between consolidating market conditions and upcoming catalysts will define this week's trading landscape for NYMEX platinum.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime