GBP/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's GBP/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Market Overview
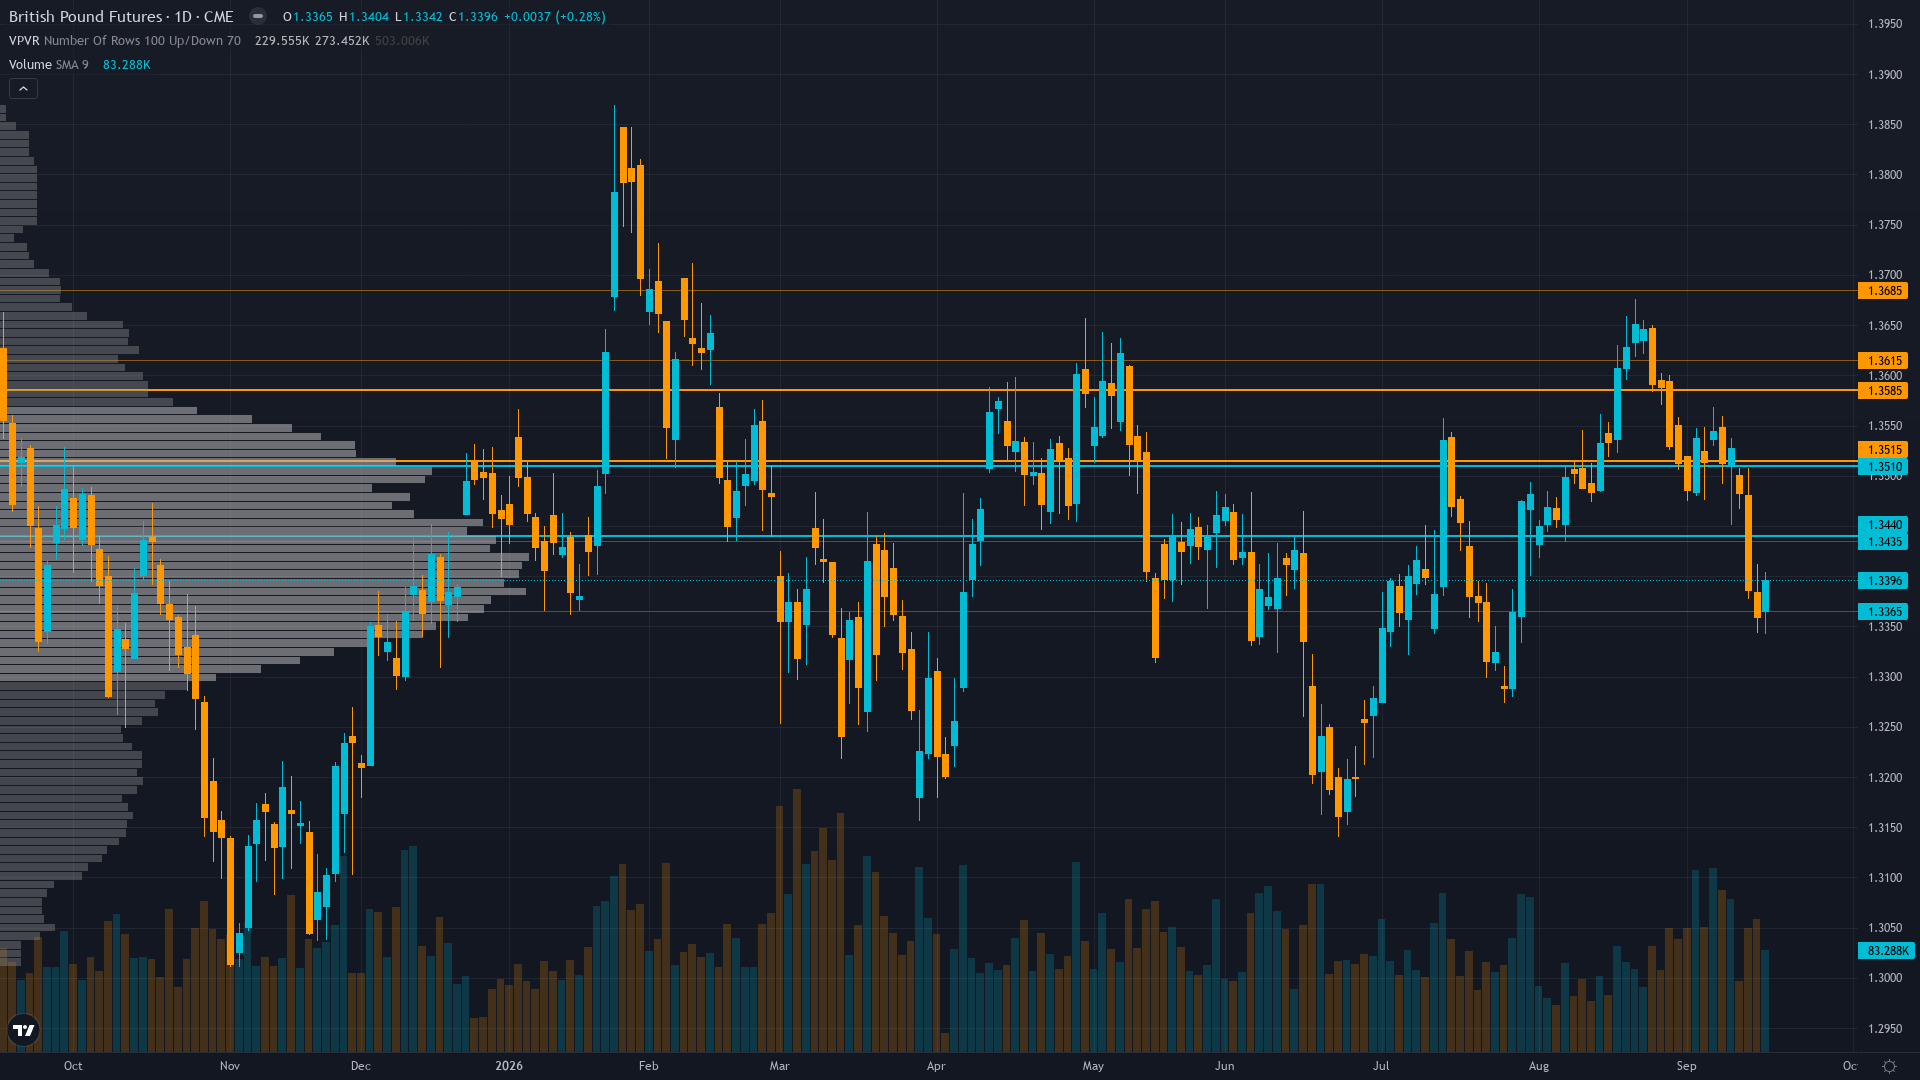
GBP/USD sits at 1.3392 after a 0.27% gain — a quiet move higher without aggressive momentum. cable is range-bound and tightening, with decreasing volatility signalling a directional resolution ahead.
GBP at 1.3392 near two-month lows below $1.34 following BoE Sep 17 hold at 3.75% (6-3 vote), with mixed discipline signals preventing conviction ahead of UK PMI data, BoE Bailey speech, and US Durable Goods in the week ahead
This Week's Catalysts & Drivers
Primary driver: NO CALL mandated as weighted signal of -0.68 falls below 6B's 1.1 Min Signal threshold per Rule 2 while GBP consolidates at 1.3392 near two-month lows after BoE held at 3.75% on Sep 17 (6-3 vote) and strong USD continues from hawkish Fed posture, with key catalyst week ahead featuring UK Manufacturing/Services PMI (Sep 23), BoE Bailey speech (Sep 25), and US Durable Goods (Sep 25)
Secondary factor: Extreme COT speculative short positioning at -58,715 contracts (12.7th percentile of 3-year range) from CFTC Sep 15 data continues to create powerful contrarian squeeze setup — Institutional agent flags at signal -2.5 (bearish positioning = bullish contrarian signal) — but this has been in place for weeks without triggering the expected squeeze, raising questions about whether positioning is already fully priced
Additional influence: Last week's -0.91% decline (from 1.3525 to 1.3392) following the Sep 17 BoE hold and continued USD strength on hawkish Fed expectations pushed GBP below key 1.3400 support zone, confirming bearish technical structure with price below both 50-day MA (1.3635) and 200-day MA, RSI at 31 oversold, but the catalyst absorption has occurred and the week ahead brings fresh PMI data with estimates pointing to improvement in UK Manufacturing (52.7e vs 51.7p)
Economic backdrop: MACRO REGIME: TRANSITIONAL with VIX at 14.88 indicating calm risk appetite, US 10Y yield at 5.01% (up 5bp on week), US treasury curve at +25bp 2s10s steepening supporting normalisation narrative, Fed funds rate at 3.63% with hawkish posture, BoE held at 3.75% on Sep 17 (6-3 vote with 3 members voting for hike), UK Manufacturing PMI due Sep 23 estimate 52.7 vs prior 51.7
Fundamental assessment: GBP/USD appears modestly undervalued at approximately 10% below UBS PPP fair value estimates of 1.48-1.50, but the persistent UK current account deficit of £22.1bn (2.8% GDP) creates structural selling pressure, while BoE-Fed rate differential remains near parity (3.75% vs 3.63%) eliminating the carry advantage that has historically supported Sterling
Technical Picture
Price at 1.3392 below both 50-day MA (1.3635) and 200-day MA with RSI at 31.0 indicating oversold conditions, negative MACD at -0.001 confirming bearish momentum, broke below key 1.3405 support level last week confirming bearish structure but oversold RSI creates mean-reversion bounce risk typical of FX_MAJOR pairs at round number support zones
At 3/10, trend strength is subdued, suggesting the market lacks a clear directional mandate.
Bull & Bear Case
Primary risk: GBP breakdown below 1.3320 major support if UK PMI data on Sep 23 disappoints relative to estimates (Manufacturing 52.7e, Services 52.1e), confirming UK economic momentum is decelerating while USD continues to strengthen on hawkish Fed expectations, with BoE Bailey speech on Sep 25 providing no hawkish surprises to arrest the decline (Probability: medium)
Primary opportunity: GBP short-covering squeeze toward 1.3405-1.3550 if UK Manufacturing PMI on Sep 23 surprises above 52.7 estimate and Services PMI holds above 52.0, validating the BoE's hawkish 6-3 vote narrative and triggering forced covering from extreme COT net short positioning at 12.7th percentile, amplified by oversold RSI at 31 providing technical bounce catalyst (Timeframe: 3-5 days through Sep 23-25 catalyst cluster (UK PMI Sep 23, US Jobless Claims Sep 24, UK Consumer Confidence Sep 24, BoE Bailey speech Sep 25, US Durable Goods Sep 25))
This week's edge: Below Min Signal threshold — |signal| of -0.68 falls below 6B's 1.1 Min Signal per Rule 2, preventing directional conviction despite the extreme COT net short positioning at 12.7th percentile creating one of the most powerful contrarian squeeze setups in the past 3 years. The critical unresolved tension is whether the persistent extreme short positioning represents a genuine contrarian opportunity or whether structural hedgers and commercial interests are correctly positioning for continued GBP weakness amid the hawkish Fed/dovish BoE narrative. The oversold RSI at 31 and UK PMI data approaching (Manufacturing estimate 52.7 vs 51.7 prior showing improvement) provide potential bullish catalysts, but these are offset by the strong USD momentum and BoE's cautious guidance at the Sep 17 meeting. Last week's MISSED call (-0.91% decline on NO CALL) and low vol regime (4.3% 20d realised at sub-25th percentile, raising effective noise floor to 0.65%) further argue against directional conviction in this post-catalyst environment.
Volatility Regime
Volatility for GBPUSD is at the 25th percentile over 90 days — a compressed regime where breakout potential builds beneath the surface. The vol trend is flat, with no meaningful shift across timeframes. Stable vol environments often lull traders before a regime change arrives.
Low volatility regime with 20d realised at 4.3% suggests compressed range expectations of 0.5-0.7% daily; Sep 23-25 catalyst cluster (UK PMI, US Jobless Claims, UK Consumer Confidence, Bailey speech, US Durable Goods) creates potential for 1.0-1.5% broader weekly ranges; due to FX_MAJOR and low vol regime, effective noise floor raised to 0.65% for directional call consideration
What to Watch
The UK S&P Global Manufacturing PMI (Sep) and Services PMI (Sep) — Manufacturing estimate 52.7 vs prior 51.7, Services estimate 52.1 vs prior 52.5, jointly the most important data releases of the week for GBP after the Sep 17 BoE decision on Wednesday 23 September stands as the week's primary risk event — high-impact and capable of overriding the existing technical and sentiment setup.
The interplay between consolidating market conditions and upcoming catalysts will define this week's trading landscape for 6B futures.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime