EUR/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's EUR/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Where Things Stand
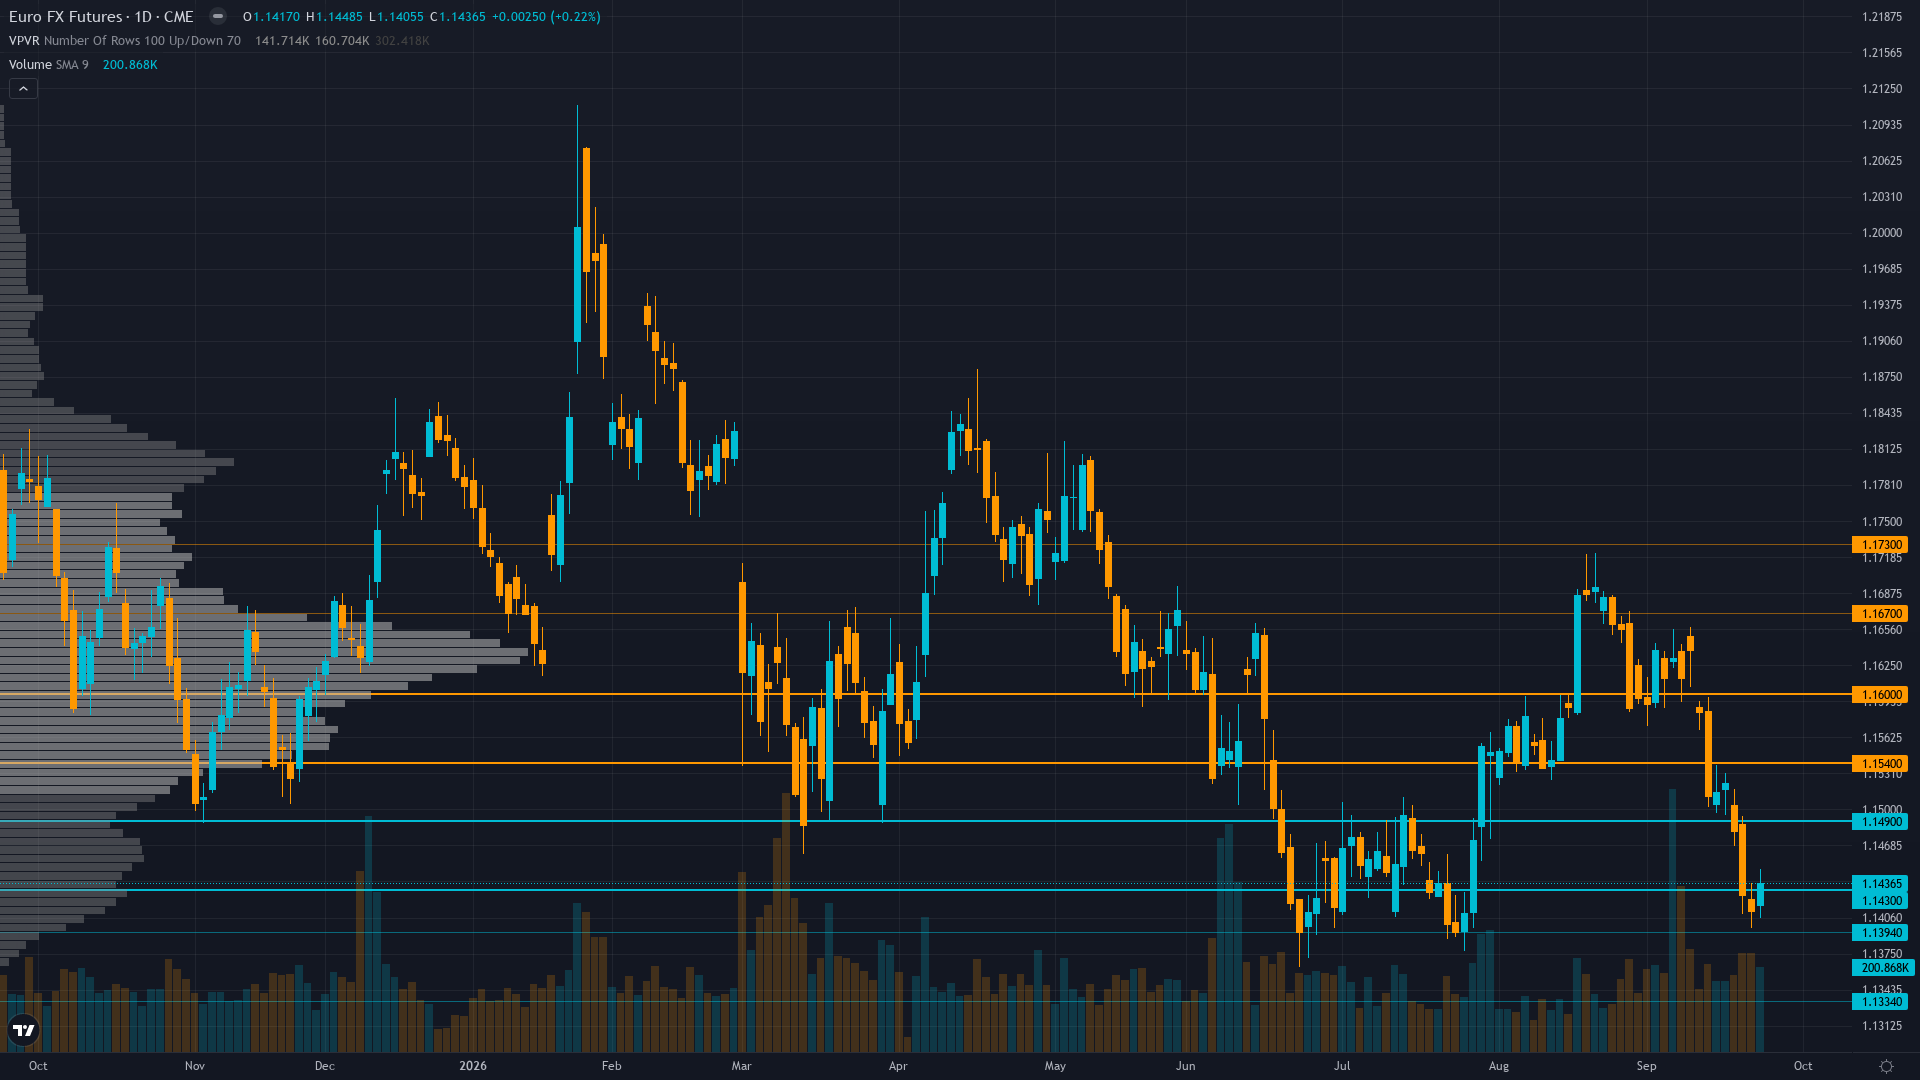
EUR/USD is trading at 1.1409, up a modest 0.10% as the market edges higher. euro dollar is consolidating, with price compressing into a narrower range as the market builds energy for its next move.
EUR/USD grinding toward 1.1364 52-week low with momentum firmly bearish — institutional year-end targets of 1.12-1.15 are being revised lower (JPMorgan forecasts 1.14 by Q4 2026) as US 10Y yields above 5.10% sustain USD dominance and Eurozone inflation acceleration fails to generate EUR demand
What's Driving Price
Primary driver: EUR/USD at 1.1409 is grinding toward the 1.1364 52-week low as US 10-year yields surged 16bp in the past week to 5.17% (widening the US-EU rate differential to approximately 140bp+) and CFTC COT data (2026-09-22) shows spec shorts exploded by -25,341 contracts to -52,334 (10.1st percentile) — piling on as price approaches the yearly nadir
Secondary factor: The densest Eurozone catalyst cluster in 5 weeks arrives Sep 28-29: ECB Lagarde and Elderson speeches Monday, followed by Eurozone Inflation Rate YoY Sep (est 4.7% vs prior 4.3%), Retail Sales Aug (est 0.3% MoM vs -0.9% prior), Economic Sentiment, Business Confidence, and US JOLTs — five high-impact releases in a 24-hour window capable of a noise-floor-breaking move
Additional influence: Seasonal divergence deepens — September historically averages +0.6% for EUR/USD (FOREX.com/StoneX, 50+ year data), but 2026 September is tracking approximately -2.16% MTD, a -2.76% deviation from the multi-decade mean that either confirms a bearish regime shift or sets up extreme mean-reversion potential through year-end
Economic backdrop: US macro stable with Fed at 3.63%, inflation 2.34%, unemployment 4.1%, but US 10Y surged to 5.17% (+16bp weekly) creating significant rate headwind for EUR; Eurozone inflation Sep expected at 4.7% YoY (up from 4.3% prior) — if confirmed, it keeps ECB tightening pressure elevated despite inequality-transmission concerns flagged by Economic agent
Fundamental assessment: EUR moderately overvalued at approximately 8-10% above PPP estimates of 1.05-1.08 (OECD/IMF data) with Eurozone structural current account surplus of €46.9B (June 2026) providing partial offset, but 140bp+ Fed-ECB rate differential (Fed 3.63% vs ECB 2.50%), US 10Y at 5.17%, and fiscal deficits at -2.9% of GDP (debt 87.8% of GDP) create a net negative fundamental backdrop
Chart Assessment
Price at 1.1409 approaching the 1.1364 52-week low with daily RSI likely oversold below 30; 50-day MA at ~1.1382 (Investing.com Sep 27) acting as magnetic support — price oscillating around it; a confirmed close below 1.1364 would target 1.1280 structural support and open the path toward 1.1000; resistance at 1.1480 (prior support-turned-resistance) and then 1.1550
With trend strength at 4/10, the directional signal is present but far from decisive.
Risk & Opportunity
Primary risk: A below-forecast Eurozone CPI print (<4.5% YoY) combined with another week of US 10Y yields above 5.10% would confirm the rate differential headwind is intensifying, potentially triggering a break below 1.1364 52-week low and accelerating the speculative short build-up (already -52K contracts) toward a test of 1.1280 (Probability: medium)
Primary opportunity: If Eurozone CPI prints above 4.7% (acceleration) while US JOLTs (Sep 29) show cooling labor demand, the extreme speculative short positioning at the 10.1st percentile (-52,334 contracts) could trigger a violent short squeeze reversing the -25K contract build-up, with month-end BofA flow estimates providing additional EUR buying support back toward 1.1480-1.1550 (Timeframe: 2-3 days through Sep 28-29 catalyst cluster and Sep 30 quarter-end rebalancing)
This week's edge: Below conviction floor — evidence-weighted assessment. The measured composite signal of approximately -1.36 exceeds the 1.1 Min Signal threshold and the Sep 28-29 catalyst cluster provides events capable of breaking the 0.50% noise floor, but 2 consecutive MISSED graded calls trigger a -2 conviction penalty under Rule 3, reducing conviction from 6 to 4 — below the minimum 5 required for any directional call. The Fundamental discipline (54% measured accuracy, highest in FX class) delivers a -1.2 bearish signal on PPP overvaluation and structural headwinds, while the Economic agent's -2.5 signal (47% accuracy, near coin-flip) must be discounted. The extreme COT short positioning at 10.1st percentile with a -25,341 contract weekly increase represents an aggressive bearish commitment that is NOT consistent with the short-covering exhaustion pattern observed two weeks ago — this is fresh speculative conviction, not positioning fatigue, which significantly reduces the contrarian squeeze thesis. The BofA month-end EUR buying flow analysis provides a tactical counterbalance but insufficient to justify directional conviction given the penalty constraints. A September CPI print above 4.7% could break the 1.1364 support; a print below 4.2% while month-end flows support could trigger a sharp reversal back toward 1.1480. Remain NO CALL until the Sep 28-29 data cluster provides directional clarity — post-catalyst assessment will determine whether the 1.1364 support holds or breaks.
Volatility Backdrop
EURUSD volatility at the 48th percentile reflects a balanced environment where standard risk parameters apply. Volatility remains anchored at current levels, with no clear signal of an imminent regime shift in either direction.
Normal volatility regime suggests 50-75 pip daily ranges from current 1.1409 pivot. The Sep 28-29 catalyst cluster (4 Eurozone events + US JOLTs) provides sufficient range for event-driven positioning. Stop widths of 35-45 pips appropriate near the 52-week low. Support immediate: 1.1364 (52-week low). Resistance immediate: 1.1480 (prior support). A confirmed break below 1.1364 on high volume with catalyst follow-through targets 1.1280-1.1300; a rally above 1.1480 targets 1.1550 resistance which was support-turned-resistance from the Sep 10 ECB failure zone
The Week Ahead
Eurozone Inflation Rate YoY (Sep) and Retail Sales MoM (Aug) at 07:00 CET — inflation est 4.7% YoY vs prior 4.3%, retail sales est 0.3% MoM vs prior -0.9%; dual release creates binary catalyst for EUR direction as markets assess whether inflation acceleration forces ECB action on Tuesday 29 September is a high-impact catalyst with the potential to redefine the near-term outlook entirely.
How EUR/USD navigates the confluence of consolidating conditions and incoming data will determine whether the current directional thesis holds or breaks.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime