Crude Oil Forecast This Week — Outlook, Drivers & Key Levels
This week's Crude Oil outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

This Week's Starting Point
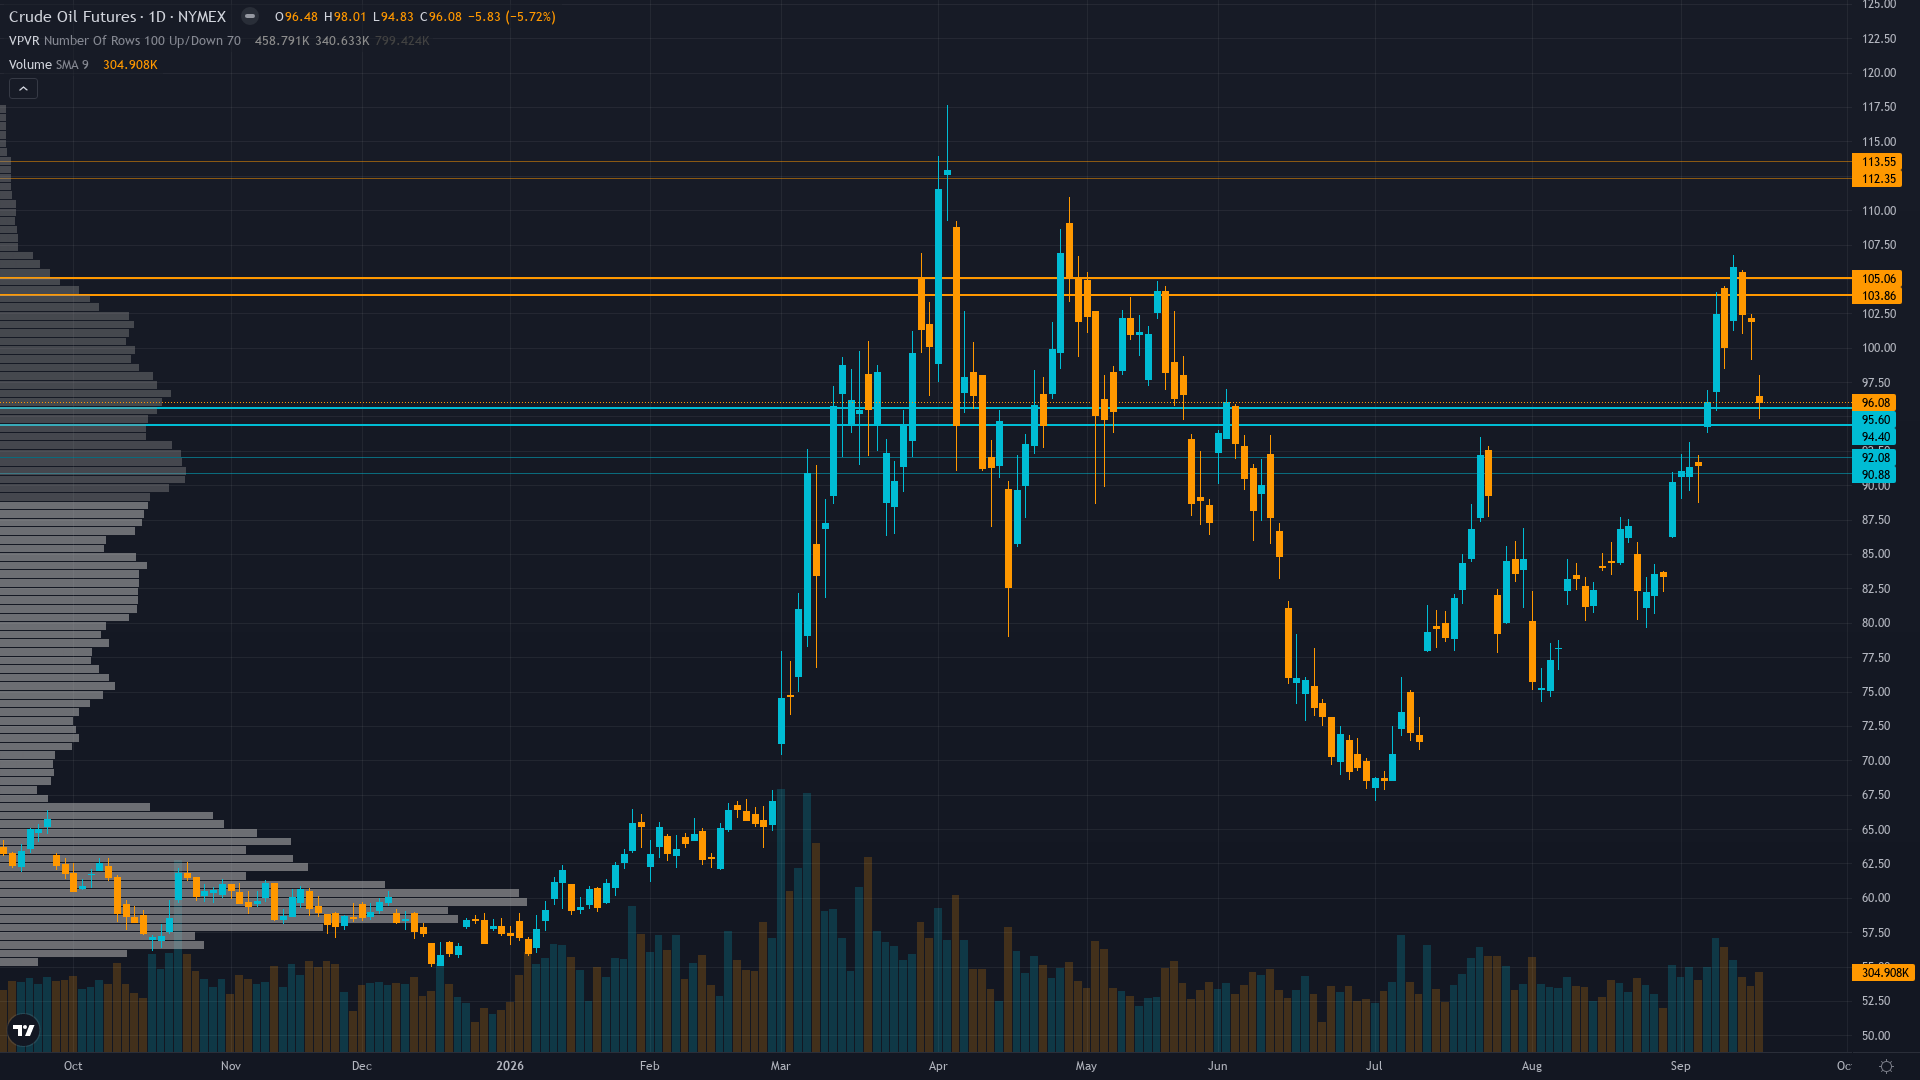
crude oil is trading at 95.41, down 2.34% as selling pressure weighs on price. Price action in crude oil futures has compressed into a consolidation pattern, typically a precursor to a directional breakout.
Market divided and uncertain — Polymarket shows 100% probability of WTI below $95 for September settlement, but the binary risk of Hormuz peace vs renewed escalation keeps conviction thin; the -4.64% weekly decline reflects market pricing in the first credible de-escalation signal since June
Forces in Play
Primary driver: Trump signals potential Iran war endgame (CNBC Sep 17) — 'hopefully we are towards the end of the war' triggers violent -4.64% weekly reversal from $100.05 to $95.41 as geopolitical risk premium begins unwinding
Secondary factor: Saudi Aramco ramping prompt crude sales outside Hormuz via ship-to-ship transfers at Sohar port (Bloomberg Sep 16, CNBC Sep 17), offering additional cargoes to Asian refiners and physically demonstrating supply bypass capacity
Additional influence: Seasonal headwinds from September refinery maintenance (IIR Sep 17 reporting PADD 2 biggest fall maintenance season starting) compounding demand-side pressure as US crude runs decline through Sept-Oct shoulder months
Economic backdrop: DIVERGENT — VIX at 14.81 signals complacent equity risk appetite while CL trades on its own geopolitical binary; Fed raised rates to 3.75-4.00% on Sep 16; China Aug PMI 49.3 still in contraction; 10Y yields at 5.01% continue climbing adding demand-side headwind pressure
Fundamental assessment: WTI at $95.41 still appears 12-20% overvalued vs EIA fair value estimates of $83-90/bbl, with the entire premium sustained by Hormuz disruption risk that Trump's Sep 17 peace signals may now be unwinding; structural oversupply thesis remains valid absent the geopolitical premium
Technical Landscape
WTI at $95.41 pulled back from $100+ after a -4.64% weekly decline, still above both 50 and 200-day MAs but testing $95.71 daily range low; RSI neutral at 45.7 with room in either direction; prior symmetrical triangle breakout to $100 now challenged
Trend strength sits at 4/10, reflecting moderate directional pressure without clear dominance.
Risk-Reward Assessment
Primary risk: Renewed Hormuz escalation if Iran hardliners reject peace overtures or Houthi-Saudi fighting draws in US forces, reversing the de-escalation repricing and driving WTI back above $100 toward $103.48 resistance (Probability: medium)
Primary opportunity: Continued de-escalation momentum with Trump-Iran negotiations producing a ceasefire framework, removing $15-20 geopolitical premium and driving WTI toward $85-91 fundamental floor as speculative length liquidates and structural oversupply thesis reasserts (Timeframe: 1-3 weeks pending Hormuz negotiation outcomes through late September)
This week's edge: Resetting after 9 consecutive misses — thesis under review. The market has begun repricing the Hormuz geopolitical premium following Trump's Sep 17 peace signals, but the desk sees asymmetry favoring further downside as Saudi bypass supply (ship-to-ship transfers at Sohar) and refinery maintenance season compound the de-escalation catalyst. However, the 9-miss streak and integrity protocol mandate NEUTRAL. The fundamental overvaluation (12-20% above EIA fair value), seasonal weakness (September weakest month), and diplomatic momentum create a coherent bearish case that the market is only beginning to price. Yet the same binary risk that has whipsawed the desk for 9 consecutive weeks demands restraint.
Risk Environment
With vol at the 82th percentile, oil price is trading in an elevated regime where daily ranges can surprise even experienced traders. Volatility is contracting, with realised vol declining across timeframes. Compressed volatility often precedes sharp directional moves as energy builds.
Contracting high vol regime with expected daily ranges of $2.50-4.00; the $91.48-$103.48 weekly range is consistent with current ATR; stop placement at 1.5-2x ATR ($4-6) appropriate; the transition from escalation to potential de-escalation creates episodic headline risk that can generate 2-3% gap moves in either direction; trend-following unreliable in this binary transition phase
Looking Forward
All eyes turn to API Crude Oil Stock Change (Sep 18) — first inventory data point during this de-escalation phase, with Saudi additional supply potentially showing in US imports on Tuesday 22 September, which carries enough weight to force a decisive directional move.
The week ahead for crude oil futures hinges on whether the prevailing consolidating regime can absorb the scheduled catalysts without a regime shift.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime