AUD/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's AUD/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

This Week's Starting Point
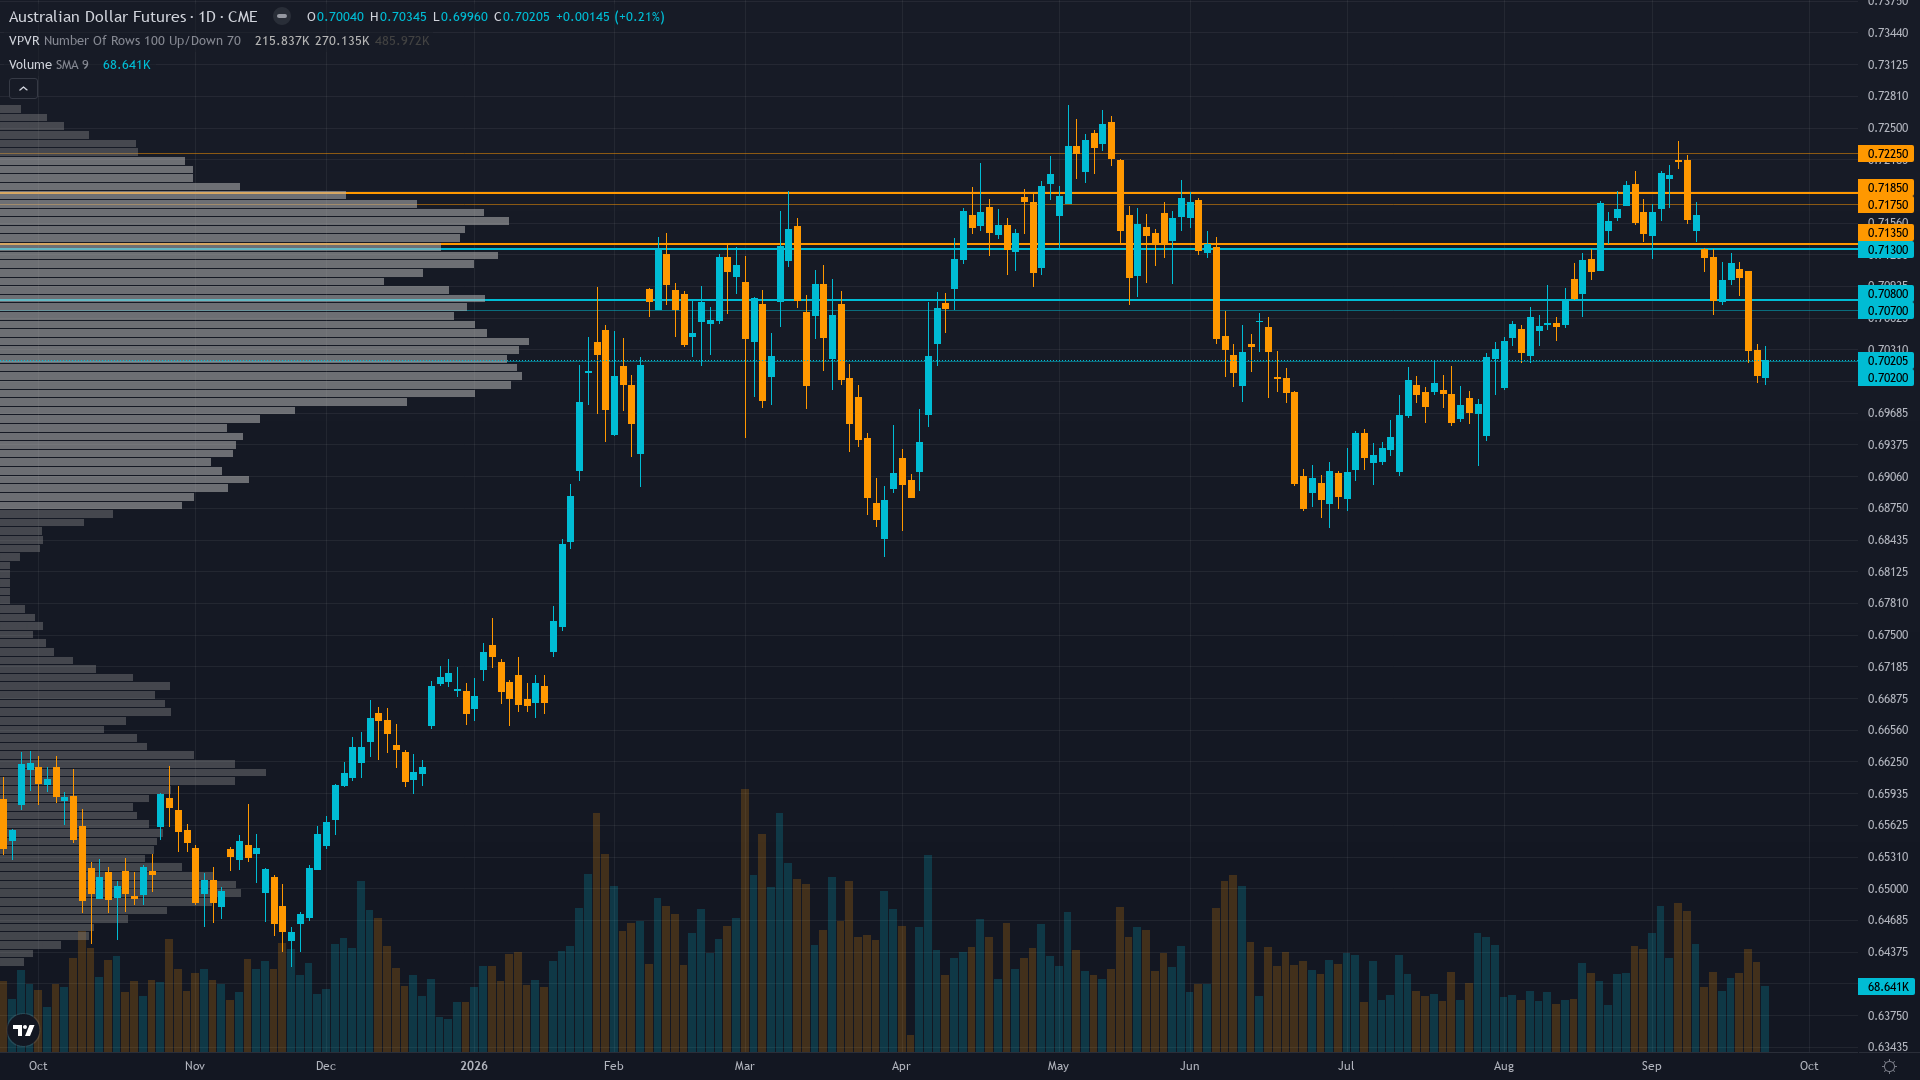
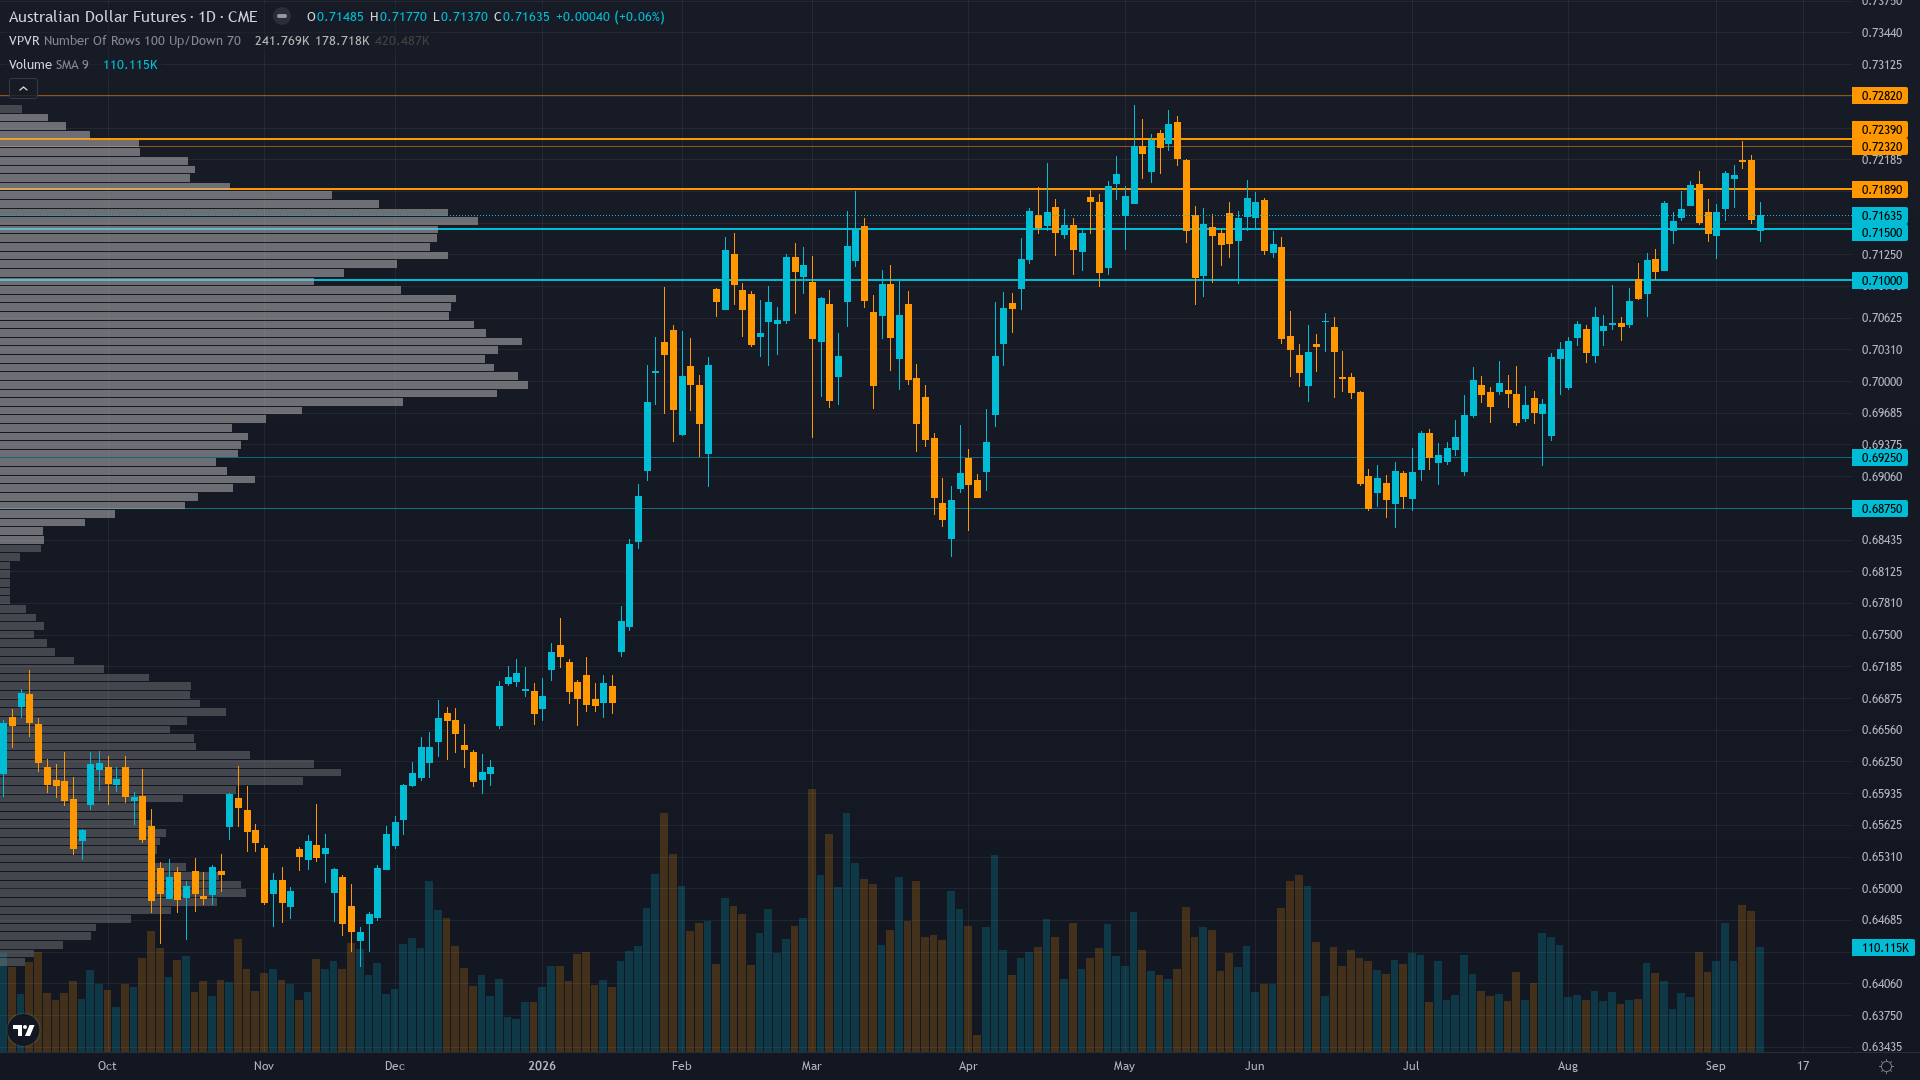
AUD/USD is trading at 0.7174, down 0.44% in a measured pullback. Price action in aussie dollar has compressed into a consolidation pattern, typically a precursor to a directional breakout.
Market consensus cautiously bullish on AUD supported by the RBA's ~80% September hike probability and 72bp policy advantage over the Fed, but price stalling near 0.7174 after the Sep 10 risk-off reversal from 0.7220 awaiting China data and FOMC for directional resolution
Forces in Play
Primary driver: RBA-Fed policy divergence remains the structural backbone with RBA at 4.35% vs Fed at 3.63% (72bp advantage), but the September 29 RBA meeting is the critical binary catalyst with market pricing ~80% probability of a 25bp hike to 4.60% per recent hawkish RBA commentary from Deputy Governor Hauser on Sep 8 and Governor Bullock's tightening bias maintained
Secondary factor: China's August economic data deluge on September 15 (Industrial Production est 4.8% vs 4.5% prior, Retail Sales est 0.8% vs 0.6%, House Price Index est -3.1% vs -3.2%) represents the near-term demand catalyst for Australia's largest export partner — iron ore at $99.57/T is at multi-month highs but China's July steel output fell 3.6% YoY signalling structural demand headwinds
Additional influence: FOMC Economic Projections on September 16 and US Retail Sales (est 0.9% vs -0.6% prior) are the US-side catalysts this week — a hawkish dot plot or strong retail print would boost USD and compress the 72bp RBA policy advantage, while weak data would reinforce the rate divergence theme and support AUD
Economic backdrop: TRANSITIONAL macro regime: VIX at 15.84 (below 20 fear threshold, neutral risk appetite), US Treasury 10Y at 4.96% (+18bp on the week as yields backed up), curve steepening (2s10s +33bp), US inflation at 2.36% near target, Fed on hold at 3.63%, RBA hawkish at 4.35% with ~80% September hike probability — supportive for AUD structurally but US yield backup is a headwind
Fundamental assessment: AUD modestly undervalued (5-7% below PPP fair value of ~0.75-0.76) with RBA 72bp policy advantage and elevated iron ore at $99.57/T, but Q1 current account deficit at AUD 27.1B (largest since 2016) and declining terms of trade (111.90 Q2 from 117 Q1) represent accumulating structural headwinds
Technical Landscape
Bullish trend intact above 50-day MA (0.7045) and 200-day MA with price at 0.7174, but RSI at 68.13 approaching overbought territory and price consolidating after reversing from 0.7220 highs on Sep 10 risk-off event — ascending channel with immediate support at 0.7150
Trend strength sits at 5/10, reflecting moderate directional pressure without clear dominance.
Volatility Backdrop
AUDUSD volatility at the 42th percentile reflects a balanced environment where standard risk parameters apply. Volatility remains anchored at current levels, with no clear signal of an imminent regime shift in either direction.
Normal volatility at 42nd percentile with 20-day realised vol at 6.7% annualised and ATR(14) at 0.0039 (MarketsFN Sep 10) suggesting 40-60bp daily ranges — stable but uninformative environment until this week's binary catalysts resolve; breakout above 0.7220 or breakdown below 0.7150 needs sustained follow-through from China or FOMC data
Risk & Opportunity
Primary risk: China August data on September 15 disappoints (Industrial Production below 4.8% est, Retail Sales below 0.8%) triggering risk-off flows that overwhelm the RBA policy divergence narrative and push AUD back toward 0.7150 support and potentially 0.7045 major support (Probability: medium)
Primary opportunity: China data surprises to the upside combined with FOMC Economic Projections showing unchanged rate path, validating the RBA hike narrative and triggering short squeeze on -34,870 net speculative shorts, pushing AUD through 0.7220 resistance toward the 52-week high at 0.7257 (Timeframe: 48-72 hours after China data (Sep 15) and FOMC (Sep 16) resolution, contingent on both catalysts providing positive confirmation)
This week's edge: Below Min Signal threshold — NO CALL. The weighted signal of +0.50 falls below the FX_MAJOR threshold of 1.1, mandating NO CALL per Rule 2. The key structural divergence the desk identifies is the tension between the near-certain RBA September hike narrative (80% market pricing) and accumulating domestic fundamental deterioration (record current account deficit, declining terms of trade, China steel output contraction) — the market appears to be pricing RBA policy divergence as a near-certainty without adequately discounting the downside from deteriorating terms of trade and potential Chinese demand weakness that would be exposed by disappointing data on Sep 15. The desk's last 4 graded calls are all NO CALL (most recent CORRECT at -0.57%), so no miss streak or bias streak integrity issues apply. With the asset at the 89.6th percentile of its 52-week range and approaching the September seasonal bearish inflection point (last half of September historically weak per Vantage Point Trading), the risk/reward for initiating a fresh bullish call above the Min Signal threshold is unfavourable without a specific catalyst resolution.
Looking Forward
On the calendar, RBA Hunter Speech — first RBA commentary this week, potentially providing forward guidance signals ahead of September 29 decision on Monday 14 September carries moderate market-moving potential and warrants attention in trade planning.
The week ahead for aussie dollar hinges on whether the prevailing consolidating regime can absorb the scheduled catalysts without a regime shift.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime