AUD/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's AUD/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
Current Market Picture
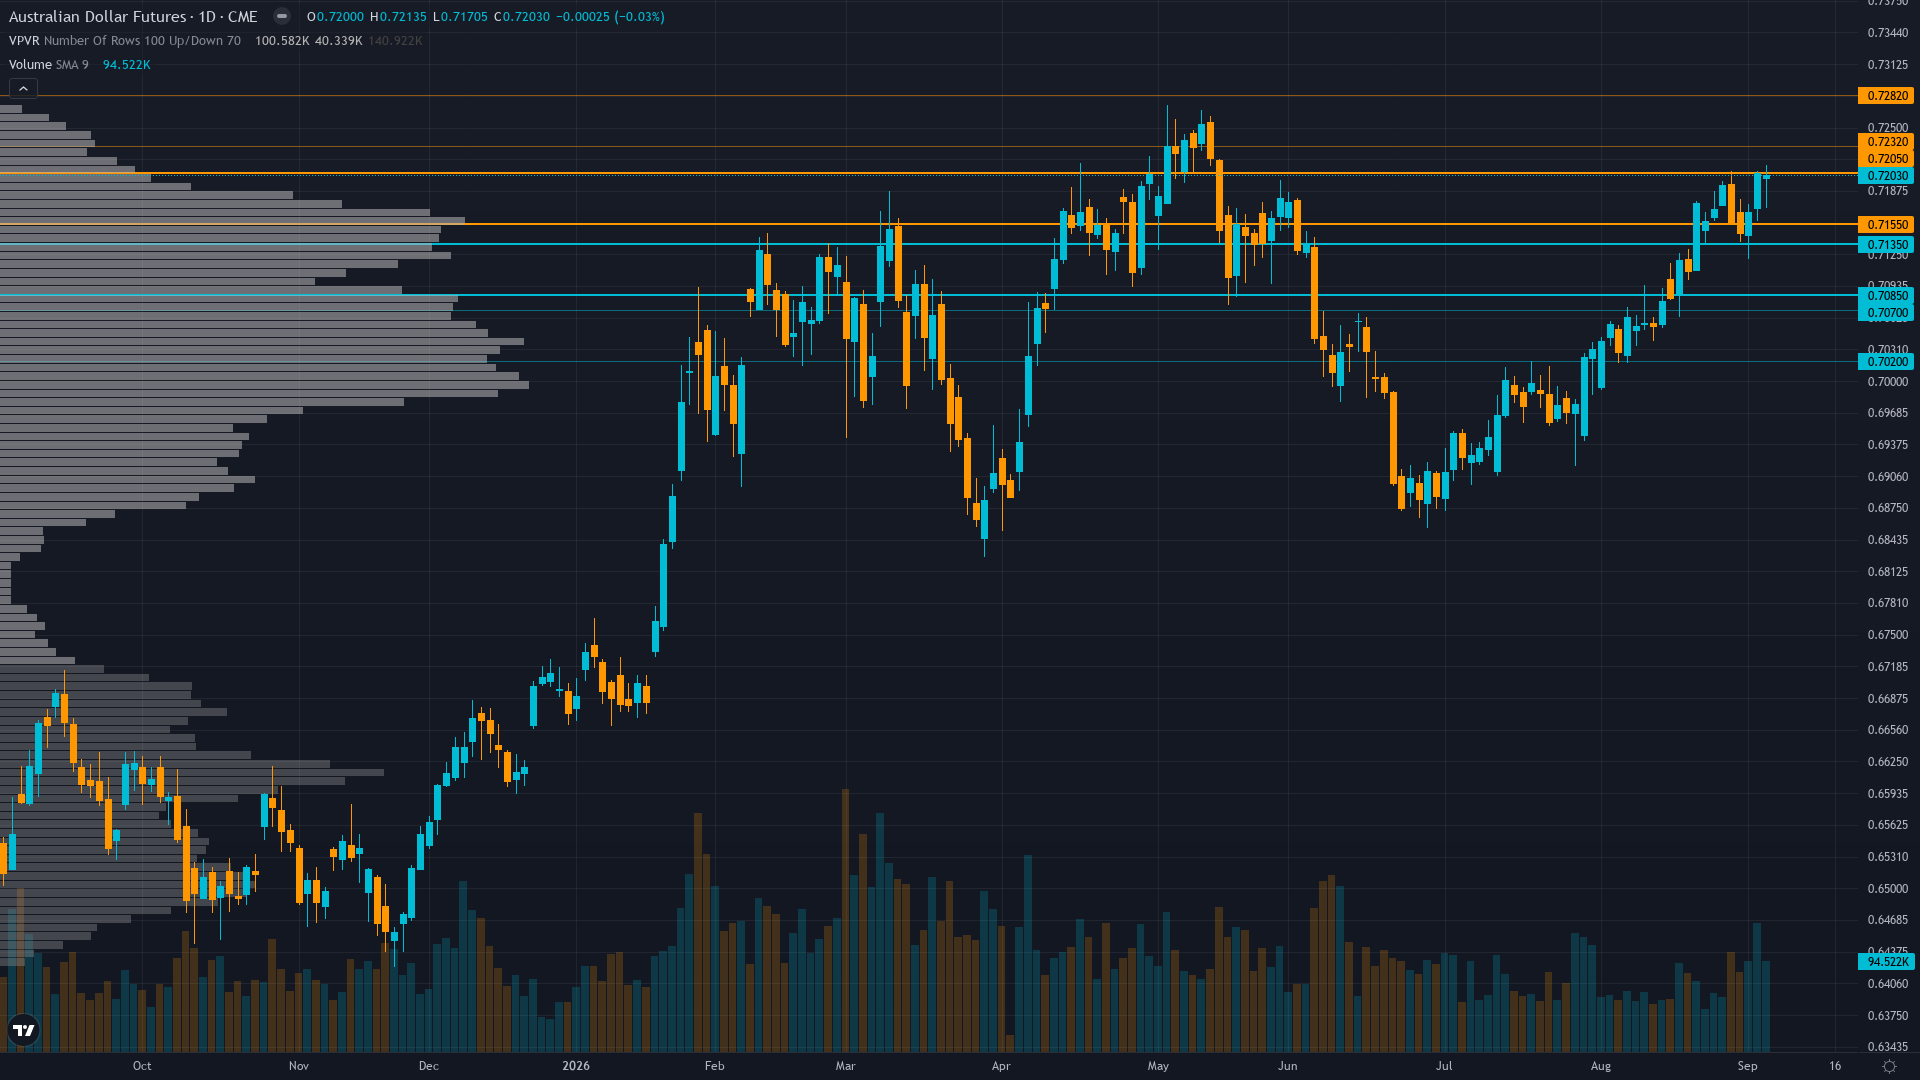
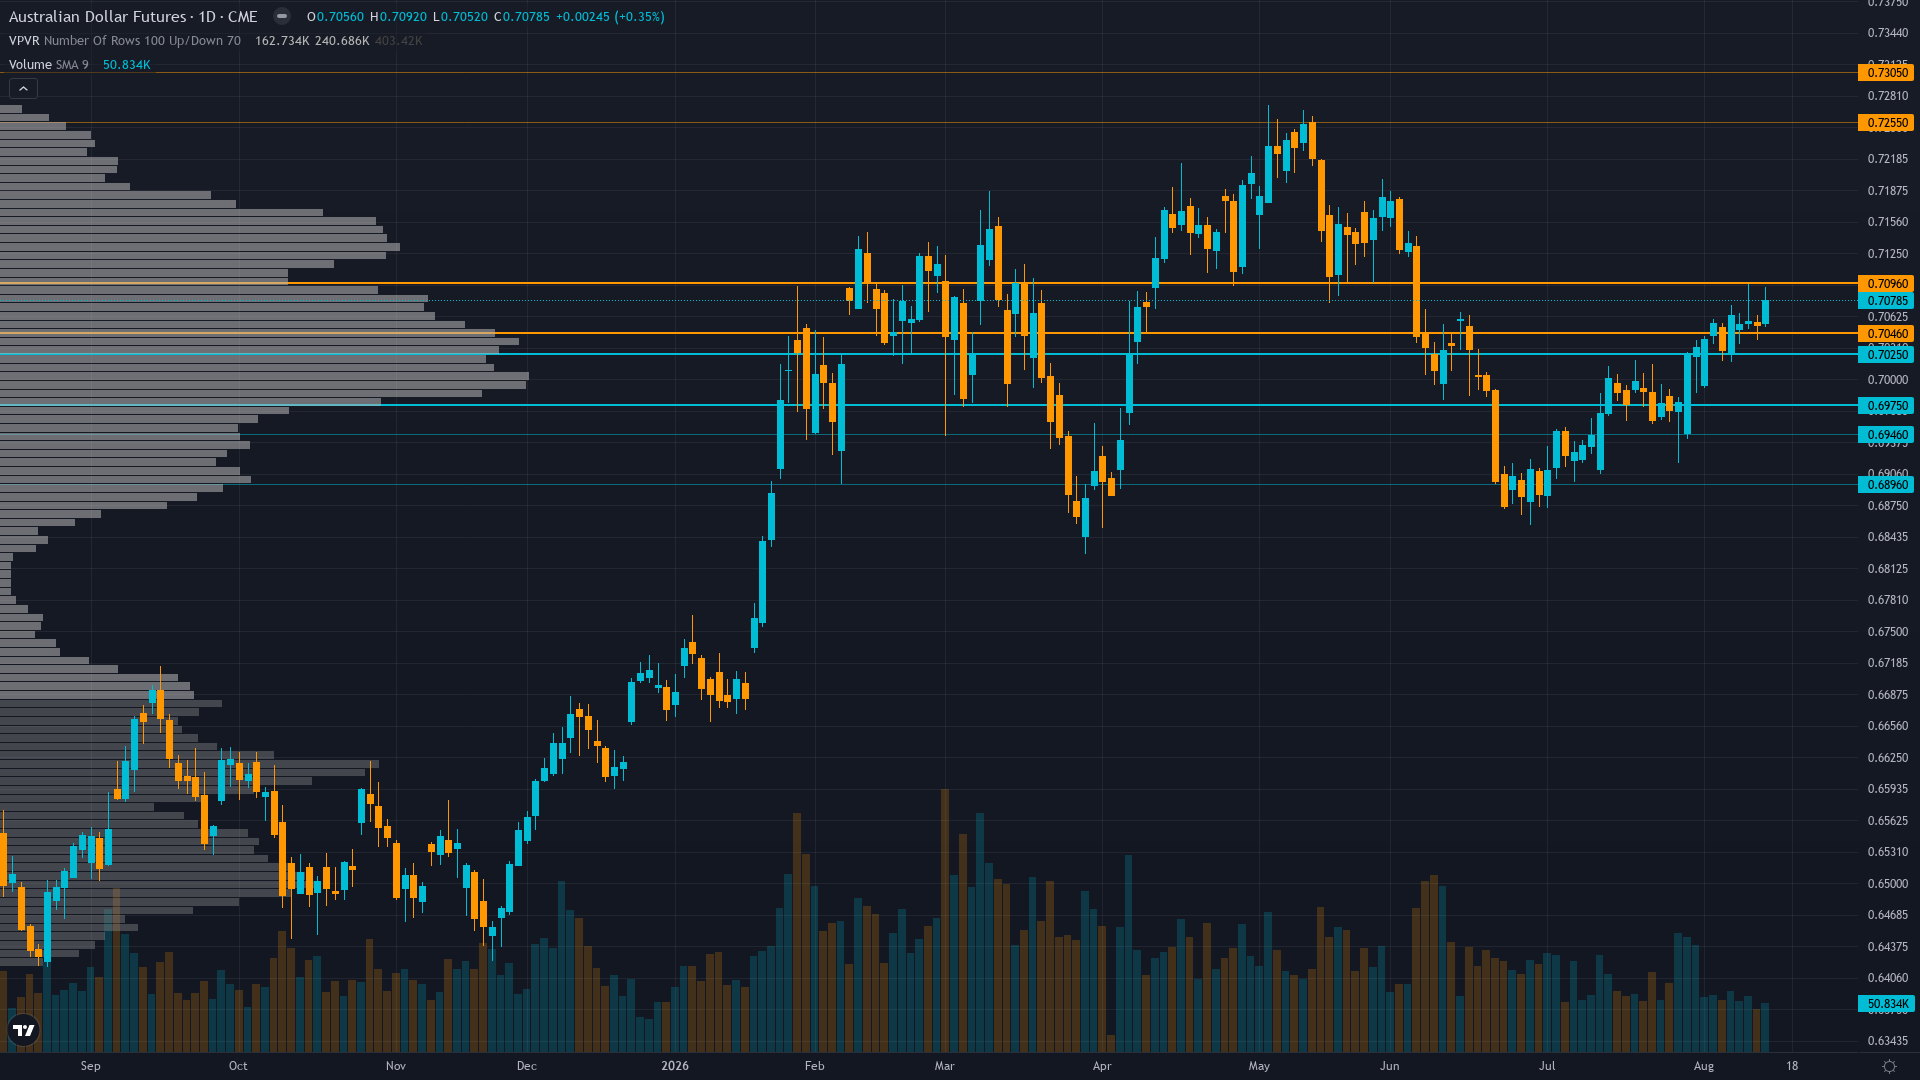
Trading at 0.7082 with a 0.33% uptick, AUD/USD is drifting higher without strong conviction. The market in aussie dollar is coiling, with narrowing price ranges suggesting stored energy that will eventually release.
Market consensus cautiously bullish on AUD expecting RBA to remain on hold at 4.35% with tightening bias, AUD consolidating in 0.7045-0.7100 range awaiting Chinese data for directional catalyst
Key Drivers This Week
Primary driver: Post-RBA positioning after August 11 hold at 4.35% (unanimous, with hike bias retained) — the RBA's statement confirming 'will hike further if required' maintains the policy divergence narrative versus Fed at 3.63%, but this is now a stale structural factor 5 days post-decision with no fresh catalyst to amplify conviction
Secondary factor: COT speculative net shorts deepened to -39,223 contracts as of Aug 11 (63.9th percentile 3-year, worsening by -6,033 contracts) — positioning is bearish and deteriorating further, approaching but not yet at contrarian extreme levels that would trigger reversal conviction, while the 0.21% weekly gain suggests shorts are modestly under water
Additional influence: Chinese data releases on August 17 (Industrial Production est 5.0% vs prev 5.3%, Retail Sales est 1.5% vs prev 1.0%) are the critical near-term catalyst for commodity-linked AUD — deteriorating Chinese economic momentum (iron ore at $95.17, down 3.75% monthly) threatens Australia's terms of trade and export revenue outlook
Economic backdrop: RISK-ON: VIX at 14.55 (below 20), 2s10s curve at +51bp normalising, US CPI trending down to 2.27%, Fed on hold at 3.63%, RBA at 4.35% — 72bp policy spread supports AUD but is fully priced
Fundamental assessment: AUD modestly overvalued (~1.6% above PPP fair value of 0.72), current account deficit persists (-A$3.02bn in May), terms of trade declining (111.90 from 117 in Q1), iron ore weakening to $95/ton — structural headwinds accumulating
Price Structure
Mildly bullish above 50-day MA (0.7045) and 200-day MA, RSI at 68 approaching overbought, momentum waning near 0.7100 resistance — wedge/consolidation pattern suggests breakout soon but direction uncertain
Trend strength at 4/10 paints a picture of a market with some direction but lacking strong conviction.
Upside & Downside
Primary risk: Weaker-than-expected Chinese data tomorrow (Industrial Production below 5.0% or further property price deterioration) would undermine the commodity demand narrative and iron ore outlook, triggering AUD breakdown below 0.7045 toward 0.6921 as speculative shorts add to positions (Probability: medium)
Primary opportunity: China data surprises to upside (Retail Sales above 2%, IP holds at 5.0%+) validating stabilising commodity demand from Australia's largest trading partner, forcing short covering from elevated -39,223 net shorts and pushing AUD through 0.7100 resistance toward 0.7190 (Timeframe: 24-48 hours post China data release August 17)
This week's edge: Below Min Signal threshold — no directional call. The weighted signal of -0.1 falls well below the FX_MAJOR threshold of 1.1, mandating NO CALL per Rule 2. The key blindspot the desk has identified that the market may be underweighting is the depth of institutional short positioning (-39,223 contracts, worsening by -6,033) against a price that continues to grind higher — this creates asymmetric squeeze risk if Chinese data surprises to the upside on August 17. However, this single insight is insufficient to overcome the signal deficit, especially with iron ore prices declining (3.75% monthly) and Australia's terms of trade deteriorating. The desk's analytical framework correctly recognizes that the multiple Chinese data releases tomorrow create genuine two-way uncertainty that prevents directional conviction today.
Volatility Context
At the 42th percentile, AUDUSD volatility sits in a normal range, neither compressed enough to signal a breakout nor elevated enough to demand caution. Realised vol is holding its current level, suggesting the market has found a temporary equilibrium in its risk pricing.
Normal volatility at 42nd percentile with 20-day realised vol at 5.1% annualised suggests 40-60bp daily ranges — stable but uninformative environment requiring fresh catalyst for directional resolution; breakout above 0.7100 or breakdown below 0.7045 needs sustained follow-through from Chinese data
Week Ahead Outlook
The next major catalyst is China July data deluge: House Prices (est -3.4% YoY), Industrial Production (est 5.0% vs 5.3% prev), Retail Sales (est 1.5% vs 1.0% prev), Fixed Asset Investment (est -6.2% vs -5.7% prev) — critical for AUD commodity demand thesis on Monday 17 August — a high-impact event that could materially shift the directional picture.
For aussie futures, the balance between existing momentum and scheduled risk events sets the stage for the week ahead.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime