Wheat Forecast This Week — Outlook, Drivers & Key Levels
This week's Wheat outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Market Overview
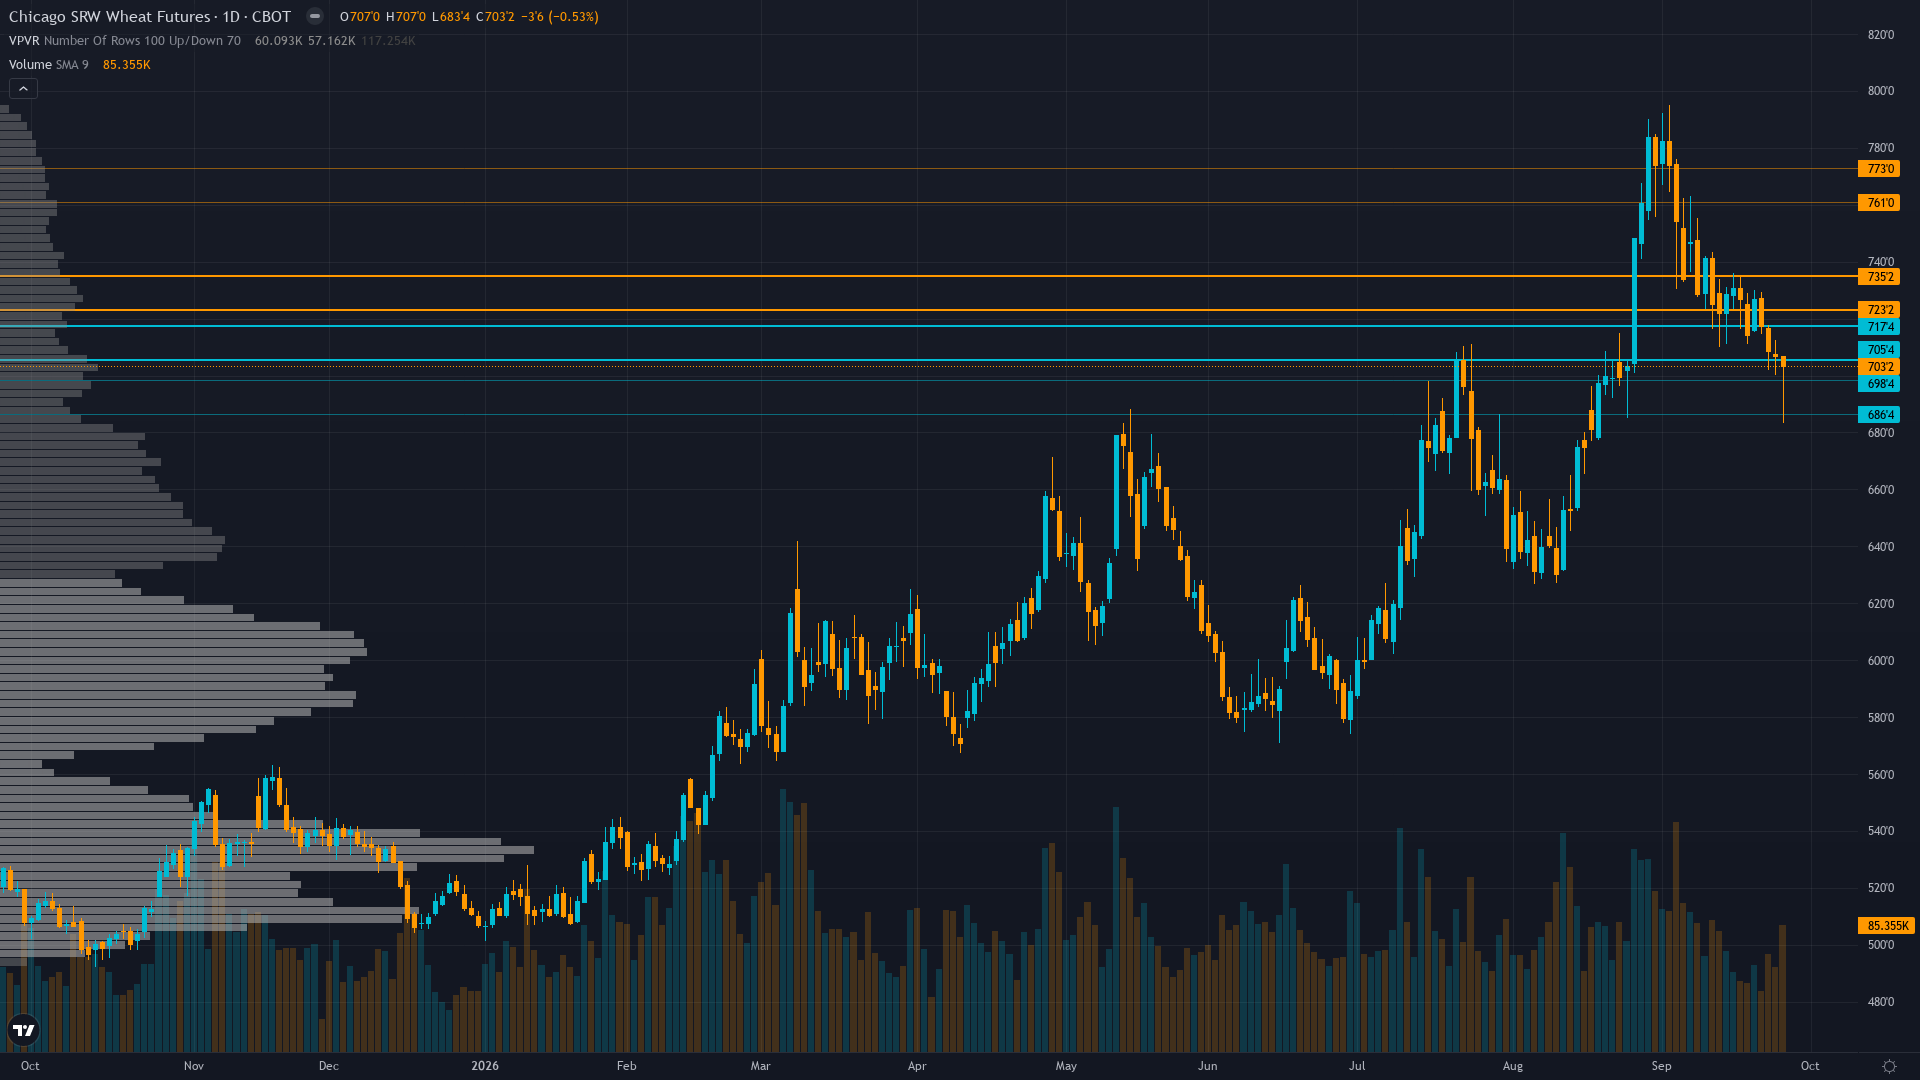
Trading at 703.25 with a 0.42% dip, wheat is giving back ground gradually. wheat futures is range-bound and tightening, with decreasing volatility signalling a directional resolution ahead.
Market consolidating in a 680-720 range after the Black Sea-driven rally and subsequent profit-taking, with structural supply disruption providing a floor but weakening export demand, managed money aggressive shorting, and approaching winter wheat planting data creating two-way uncertainty
This Week's Catalysts & Drivers
Primary driver: Structural Black Sea export disruption persists with >90% of Russian grain capacity offline (Moscow Times Aug 17), yet price has pulled back -3.73% over the past month from September highs as the bullish catalyst is increasingly priced and offset by diplomatic resolution speculation and weakening US export sales
Secondary factor: CFTC COT Sept 22 shows non-commercials flipped to net short -7,360 contracts at the 93rd percentile of the 3-year range, having added -8,588 short contracts week-over-week, creating extreme contrarian squeeze potential against ongoing Black Sea supply disruption but also reflecting genuine bearish conviction from managed money
Additional influence: USDA weekly export sales for Sept 11-17 reported declining wheat shipments (IndexBox Sept 26), suggesting that elevated US prices near 3-year highs are rationing demand and reducing the competitiveness of US wheat in global markets even as Black Sea supply remains impaired
Economic backdrop: TRANSITIONAL macro: VIX at 16.34 neutral, Treasury 10Y at 5.17% (+16bp wk) reflecting hawkish repricing, Fed on hold at 3.63%, USD structurally strong creating export competitiveness headwind, inflation stable at 2.34%, consumer sentiment weak at 51.7 indicating economic unease
Fundamental assessment: Structurally bullish supply backdrop with smallest US wheat crop since 1970/71 and Black Sea export disruption persisting, but USDA export sales declining (IndexBox Sept 26) and elevated prices near 3-year highs rationing demand; September WASDE maintained tight stocks but not incrementally bullish
Technical Picture
Price at 703.25 trading below key moving averages with daily RSI potentially oversold, reflecting -3.73% monthly decline from September highs; Strong Sell daily signal per Investing.com with immediate resistance at 707 and major resistance at 767; support at 689.50 and major support at 650
At 4/10, trend strength is middling — enough to suggest a lean, but not enough to trade with high confidence.
Risk Environment
With vol at the 75th percentile, wheat price is trading in an elevated regime where daily ranges can surprise even experienced traders. Volatility is stable, with realised vol holding steady across timeframes. This equilibrium can persist but eventually resolves into expansion or contraction.
Daily ranges of 15-20 cents typical with sustained break below 689.50 support potentially accelerating toward 650, while recovery above 707 resistance could reactivate uptrend toward 725-742 zone; elevated vol regime requires wider stops for directional positioning
Seasonal Context
Historical seasonal patterns for CBOT wheat offer no strong directional signal in September 2026 (48% win rate). New crop year begins, planting outlook matters.
Upside & Downside
Primary risk: Continued selloff below 689.50 support toward 650-680 zone as managed money adds to already extreme net short positioning (-7,360, 93rd percentile) and weakening export sales data confirms demand rationing at elevated prices, with September seasonal strength window closing and WASDE binary event risk approaching in early October (Probability: medium)
Primary opportunity: Extreme speculative net short positioning at 93rd percentile of 3-year range combined with ongoing structural Black Sea supply disruption (>90% Russian Azov-Black Sea capacity offline per Moscow Times Aug 17) creates asymmetric short-squeeze potential if October WASDE or winter wheat planting data reveals acreage reductions or if Black Sea tensions escalate further (Timeframe: Next 1-3 weeks through October 9 WASDE as winter wheat planting data and Black Sea geopolitical developments provide directional catalysts that could trigger forced short-covering from extreme net short positioning)
This week's edge: Below noise threshold — range-bound assessment. The extreme non-commercial short positioning at 93rd percentile of 3-year range (CFTC Sept 22) represents a rapid four-week flip from the 99.4th percentile long on Aug 25 to deeply short — creating asymmetric squeeze potential if Black Sea conditions escalate or winter wheat planting data disappoints, but the concurrent weakening of US export sales (IndexBox Sept 26) and declining technical structure suggest the shorts are being added with fundamental justification, creating a genuinely balanced risk-reward setup with no clear edge for directional conviction
The Week Ahead
The USDA Crop Progress Report (Sept 28, 4PM ET) — initial winter wheat planting progress for 2027 crop and final spring wheat harvest data; also Fed Bowman and Barkin speeches providing macro cross-currents on Monday 28 September represents a mid-tier catalyst that could accelerate or stall the current directional thesis.
How wheat futures navigates the confluence of consolidating conditions and incoming data will determine whether the current directional thesis holds or breaks.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime