Wheat Forecast This Week — Outlook, Drivers & Key Levels
This week's Wheat outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
This Week's Starting Point
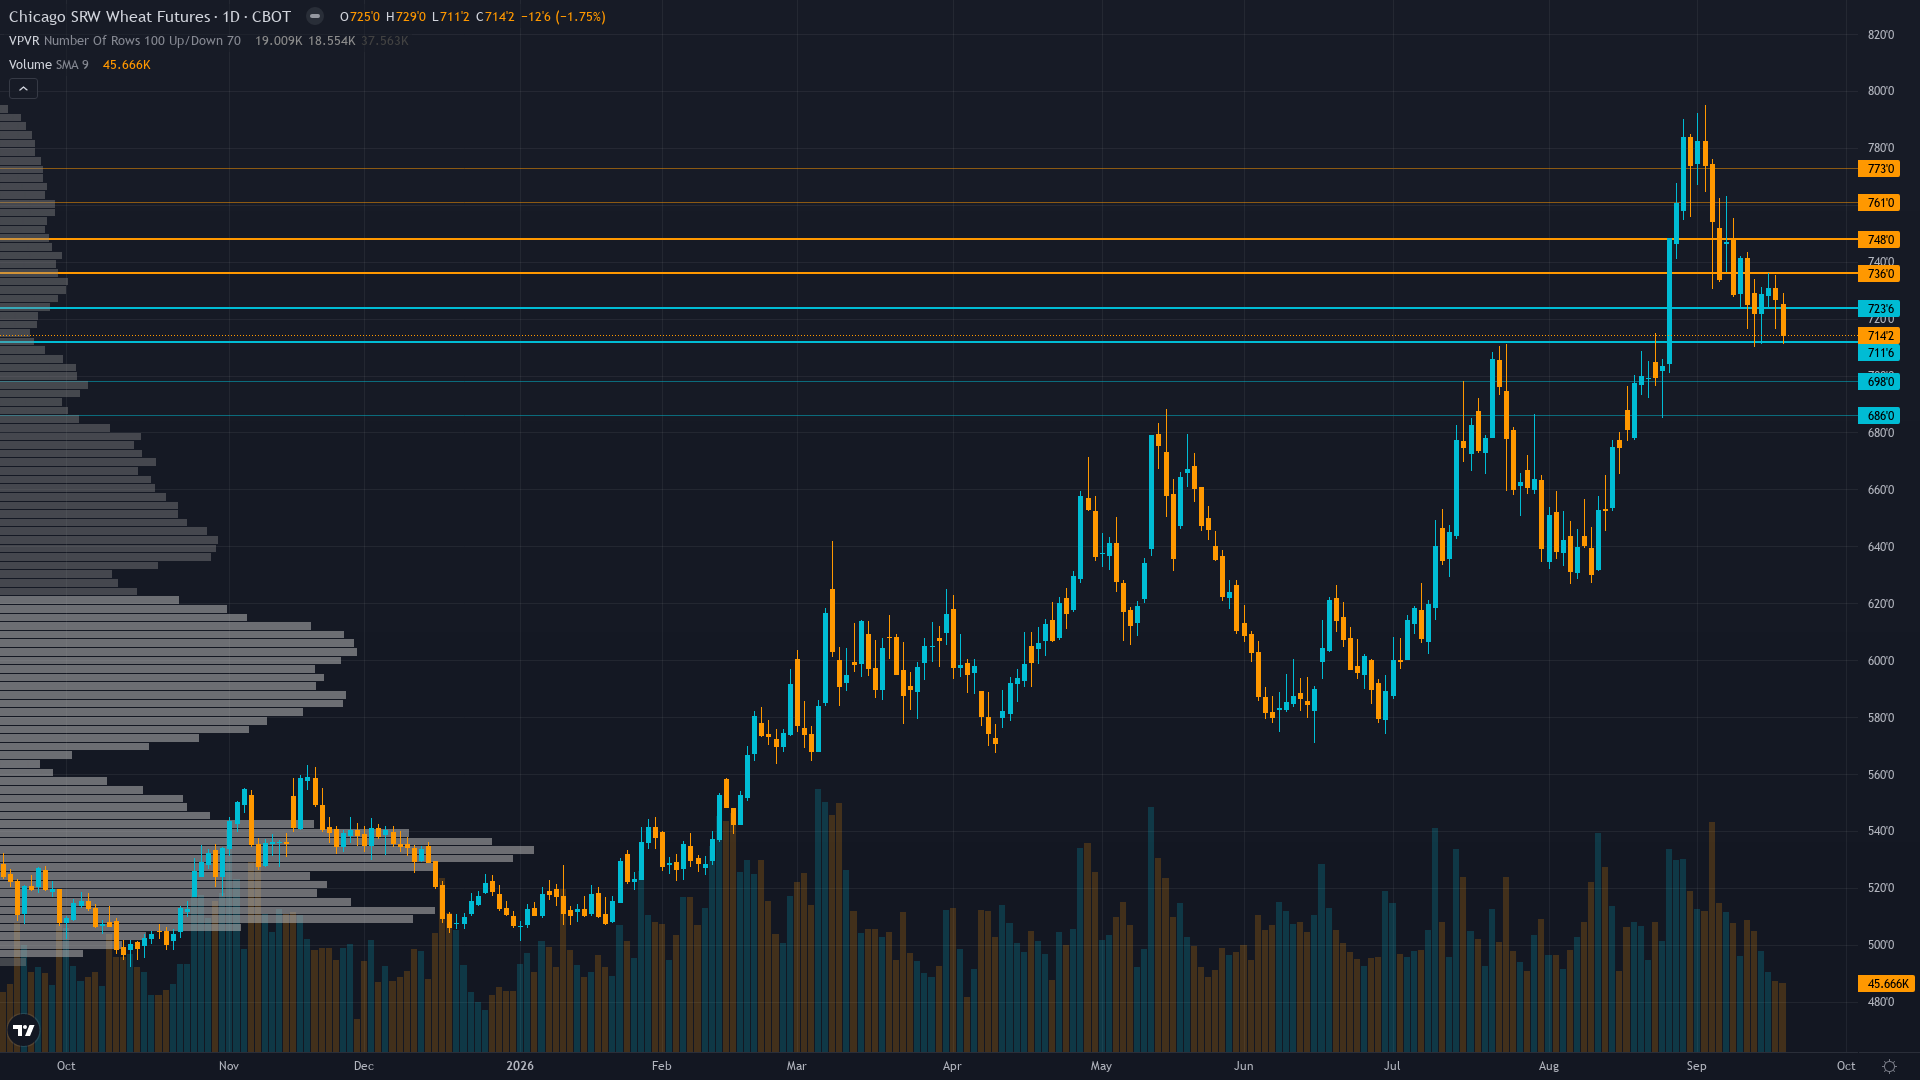
Trading at 714.25 after a 1.75% slide, wheat faces sustained selling interest. Price action in wheat futures has compressed into a consolidation pattern, typically a precursor to a directional breakout.
Market consolidating near yearly highs after the Black Sea-driven rally and subsequent profit-taking, with structural supply disruption providing a bullish floor but truce talk speculation, USD strength, and extreme long positioning unwind capping upside, creating a 692-729 consolidation range until the next directional catalyst emerges
Forces in Play
Primary driver: Structural Black Sea export disruption from Ukrainian strikes on Novorossiysk terminals persists with >90% of Russian grain export capacity offline (Moscow Times Aug 17), yet nascent truce talk speculation (TradingPedia Sep 15) introduces diplomatic resolution risk that could deflate the supply disruption premium, creating a genuine two-way binary outcome that constrains directional conviction
Secondary factor: CFTC COT data as of Sep 15 shows non-commercials slashed net long position by -9,242 contracts to +1,228 contracts (98.1st percentile of 3-year range still extreme), representing aggressive profit-taking from extreme long levels that has removed short-covering fuel and significantly reduced positioning asymmetry, leaving the market without a clear speculative tailwind in either direction
Additional influence: September seasonal tendency strongly favours long positioning with 80% win rate over 5 and 10 years (Forecaster.biz), and CME research confirms wheat typically rises from harvest lows into fall and winter, providing structural tailwind that partially offsets the positioning unwind and truce-talk headwinds, keeping the fundamental bullish case intact despite near-term consolidation
Economic backdrop: TRANSITIONAL macro regime with VIX at 16.34 indicating neutral risk appetite, Treasury 10Y at 5.01% (+5bp weekly) reflecting hawkish repricing, Fed funds at 3.63% with Fed speeches scheduled (Goolsbee Sep 21, Williams/Jefferson/Barkin Sep 22, Barr Sep 23), USD elevated creating mild export competitiveness headwind for US wheat, CPI at 2.33% stable, retail sales showing consumer resilience
Fundamental assessment: Structurally bullish with Black Sea export infrastructure damage persisting (Russia suspended export duties through end-2026 per Bloomberg Sep 2, >90% of Azov-Black Sea grain capacity offline), smallest US wheat crop since 1970/71 at 1.531 billion bushels, and global stocks-to-use tight at ~47%, but moderate overvaluation at 80.5% of 52-week range tempers upside conviction and truce talks introduce downside resolution risk
Technical Landscape
Price at 714.25 above key moving averages maintaining uptrend structure but consolidating near yearly highs with RSI likely in neutral 50-60 range, immediate resistance at 729.13 (daily high) and major resistance at 767 (52-week high), with support at 711.38 (daily low) and major support at 692.38 (August pivot), daily technical signal neutral per Investing.com
Trend strength sits at 5/10, reflecting moderate directional pressure without clear dominance.
Volatility Backdrop
wheat price is in a high-volatility environment (85th percentile over 90 days), where position sizing discipline becomes critical. Volatility remains anchored at current levels, with no clear signal of an imminent regime shift in either direction.
Daily ranges of 18-25 cents typical with Sep 18 session showing 711.38-729.13 range per Investing.com, requiring wider stops for directional positioning; sustained break below 711.38 support could trigger accelerated selling toward 692, while recovery above 729.13 resistance could reactivate uptrend toward 742-767 zone
Historical Seasonal Bias
Seasonal data for CBOT wheat in September 2026 is neutral (48% win rate). New crop year begins, planting outlook matters.
Bull & Bear Case
Primary risk: Diplomatic progress on Black Sea truce talks (TradingPedia Sep 15) restoring Russian/Ukrainian export capacity would remove the primary bullish catalyst underpinning the entire structural supply thesis, potentially triggering sharp profit-taking from current 714 level toward 680-692 as the multi-month supply disruption premium deflates and global stocks reassert as the dominant pricing force (Probability: medium)
Primary opportunity: Continued confirmation that Black Sea infrastructure damage is structural (not transient) combined with powerful September seasonal tailwind (80% win rate for long positions per Forecaster.biz) and price holding above key technical supports could drive a recovery toward 729-767 resistance as the market reprices the multi-month supply deficit against depleted US ending stocks, with the -9,242 contract speculative long reduction having cleansed the positioning deck for fresh upside (Timeframe: Next 1-3 weeks as Black Sea alternative route capacity constraints become apparent and crop progress data provides clarity on 2027 winter wheat planting conditions)
This week's edge: Resolving after a MISSED call last week (-1.76%) with Thesis Health Score of 4.0 below the 5-point threshold for directional calls — the desk sees genuine two-way uncertainty where the structural Black Sea supply disruption (multi-month infrastructure damage, confirmed by Russia's export duty suspension through end-2026) provides a bullish floor that the market may be taking for granted amid truce talk headlines, yet diplomatic progress could rapidly deflate this premium, and the 98.1st percentile extreme long positioning (even after aggressive reduction) still leaves speculators vulnerable to a positioning-driven selloff if the truce narrative gains traction
Week Ahead Outlook
USDA Crop Progress Report (Sep 21, 4PM ET) — weekly assessment of spring wheat harvest completion (currently 95%) and initial winter wheat planting progress for the 2027 crop, plus Chicago Fed National Activity Index and Fed Goolsbee speech providing macro cross-currents on Monday 21 September is the next scheduled catalyst, with moderate potential to influence near-term price action.
For wheat, the balance between existing momentum and scheduled risk events sets the stage for the week ahead.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime