Japanese Yen Forecast This Week — Outlook, Drivers & Key Levels
This week's Japanese Yen outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Market Overview
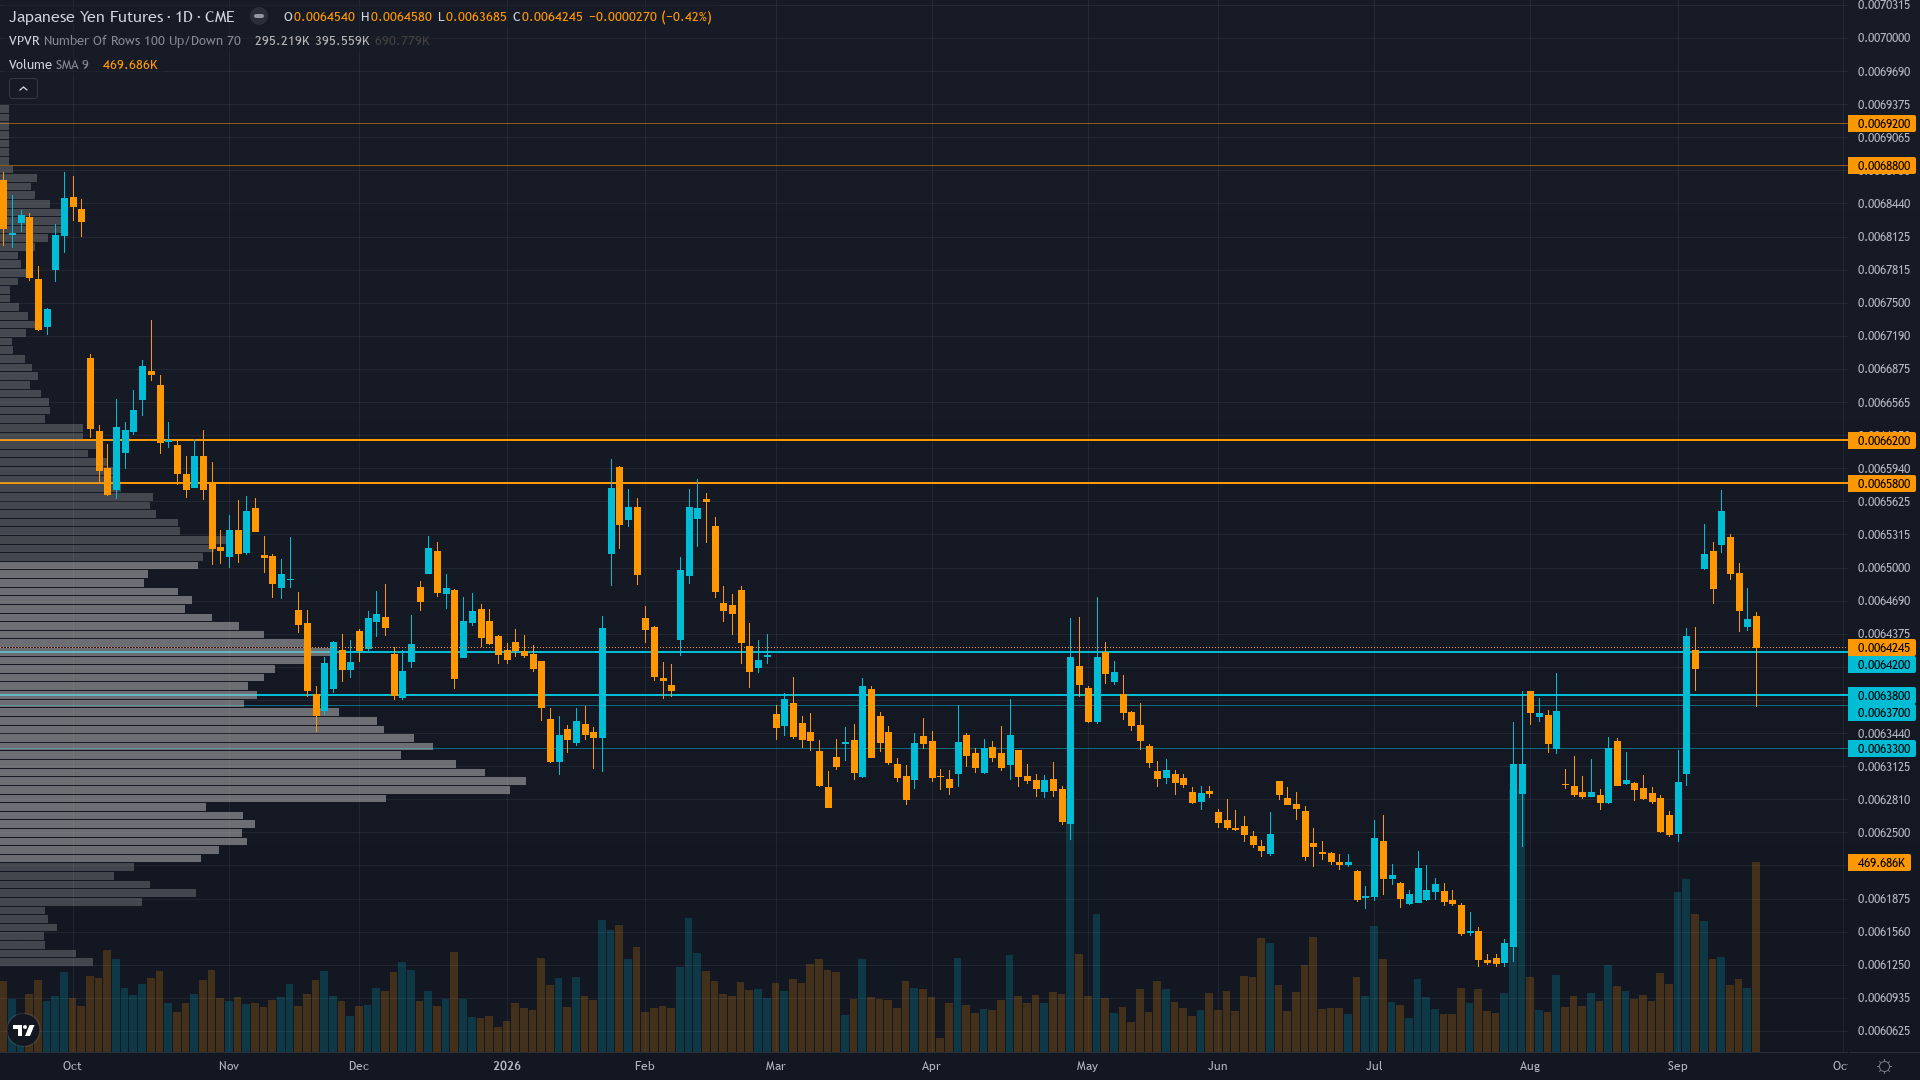
Trading at 0.006395 with a 0.52% dip, Japanese yen is giving back ground gradually. yen futures is range-bound and tightening, with decreasing volatility signalling a directional resolution ahead.
Market bearish JPY near-term after 'sell the fact' BOJ reversal with USD/JPY rising above 156.86; extreme speculative long positioning (+120K contracts, 88th percentile) vulnerable to further liquidation; consensus sees 155-158 range near-term with Japan PMI and US data as next catalysts
Upside & Downside
Primary risk: Extended long positioning unwind accelerates — CFTC net long at +120,359 contracts (88th percentile) represents extreme crowding; with the BOJ catalyst delivered and the market selling the fact, a violent positioning flush could drive 6J toward 0.0063 (USD/JPY 158.7) support or lower as overextended specs liquidate (Probability: high)
Primary opportunity: Yen stabilization after the 'sell the fact' flush finds support at 0.0063 (158.7 USD/JPY) with BOJ Masu's hawkish forward guidance providing a medium-term floor; the structural undervaluation thesis (40% PPP gap) and continued BOJ normalization trajectory argue that the bull case is merely delayed, not invalidated (Timeframe: 1-2 weeks for positioning normalization, then reassess)
This week's edge: Signal below Min Signal threshold (|signal| 0.28 < 1.1) — the weighted signal is too weak to support a directional bias. The extreme COT positioning (88th percentile, +109K weekly increase) is a genuine contrarian risk after the delivered catalyst, but the BULLISH structural thesis (PPP undervaluation, BOJ trajectory) provides a counterweight. The desk sees elevated two-way risk but no information edge for a clean directional call this week.
Key Drivers This Week
Primary driver: BOJ delivered 25bp rate hike to 1.25% (31-year high) on September 18 per CNBC, but the yen sold off -1.21% in a classic 'sell the fact' reversal as crowded speculative long positioning (CFTC +120K contracts, 88th percentile) triggered profit-taking
Secondary factor: CFTC COT September 15 records speculative net long surging to +120,359 contracts at the 88th percentile — the most extreme net long positioning in 3 years — with a single-week increase of +109,563 contracts, creating acute mean-reversion risk after the BOJ delivery
Additional influence: BOJ board member Masu confirmed hawkish forward guidance on September 18 stating the central bank will continue raising rates as inflation nears 2%, but the market focused on the 7-2 split vote and Ueda's tone to interpret the decision as dovish relative to hawkish expectations
Economic backdrop: TRANSITIONAL macro regime — VIX at 14.88 (below 20, NEUTRAL risk appetite), Fed on hold at 3.63% with no cuts in 2026, US 10Y at 5.01% (+5bp in the week), curve steepening (2s10s +25bp), BoJ Masu confirmed hawkish trajectory on Sept 18, Japan PMI data due Sept 24
Fundamental assessment: JPY structurally undervalued ~40% on PPP (fair value ~94 vs current ~156.4) with Japan's record H1 2026 current account surplus ¥17.43T (+22.5% YoY), but the BOJ rate hike catalyst has been delivered and structural carry dynamics still provide USD/JPY support
Price Structure
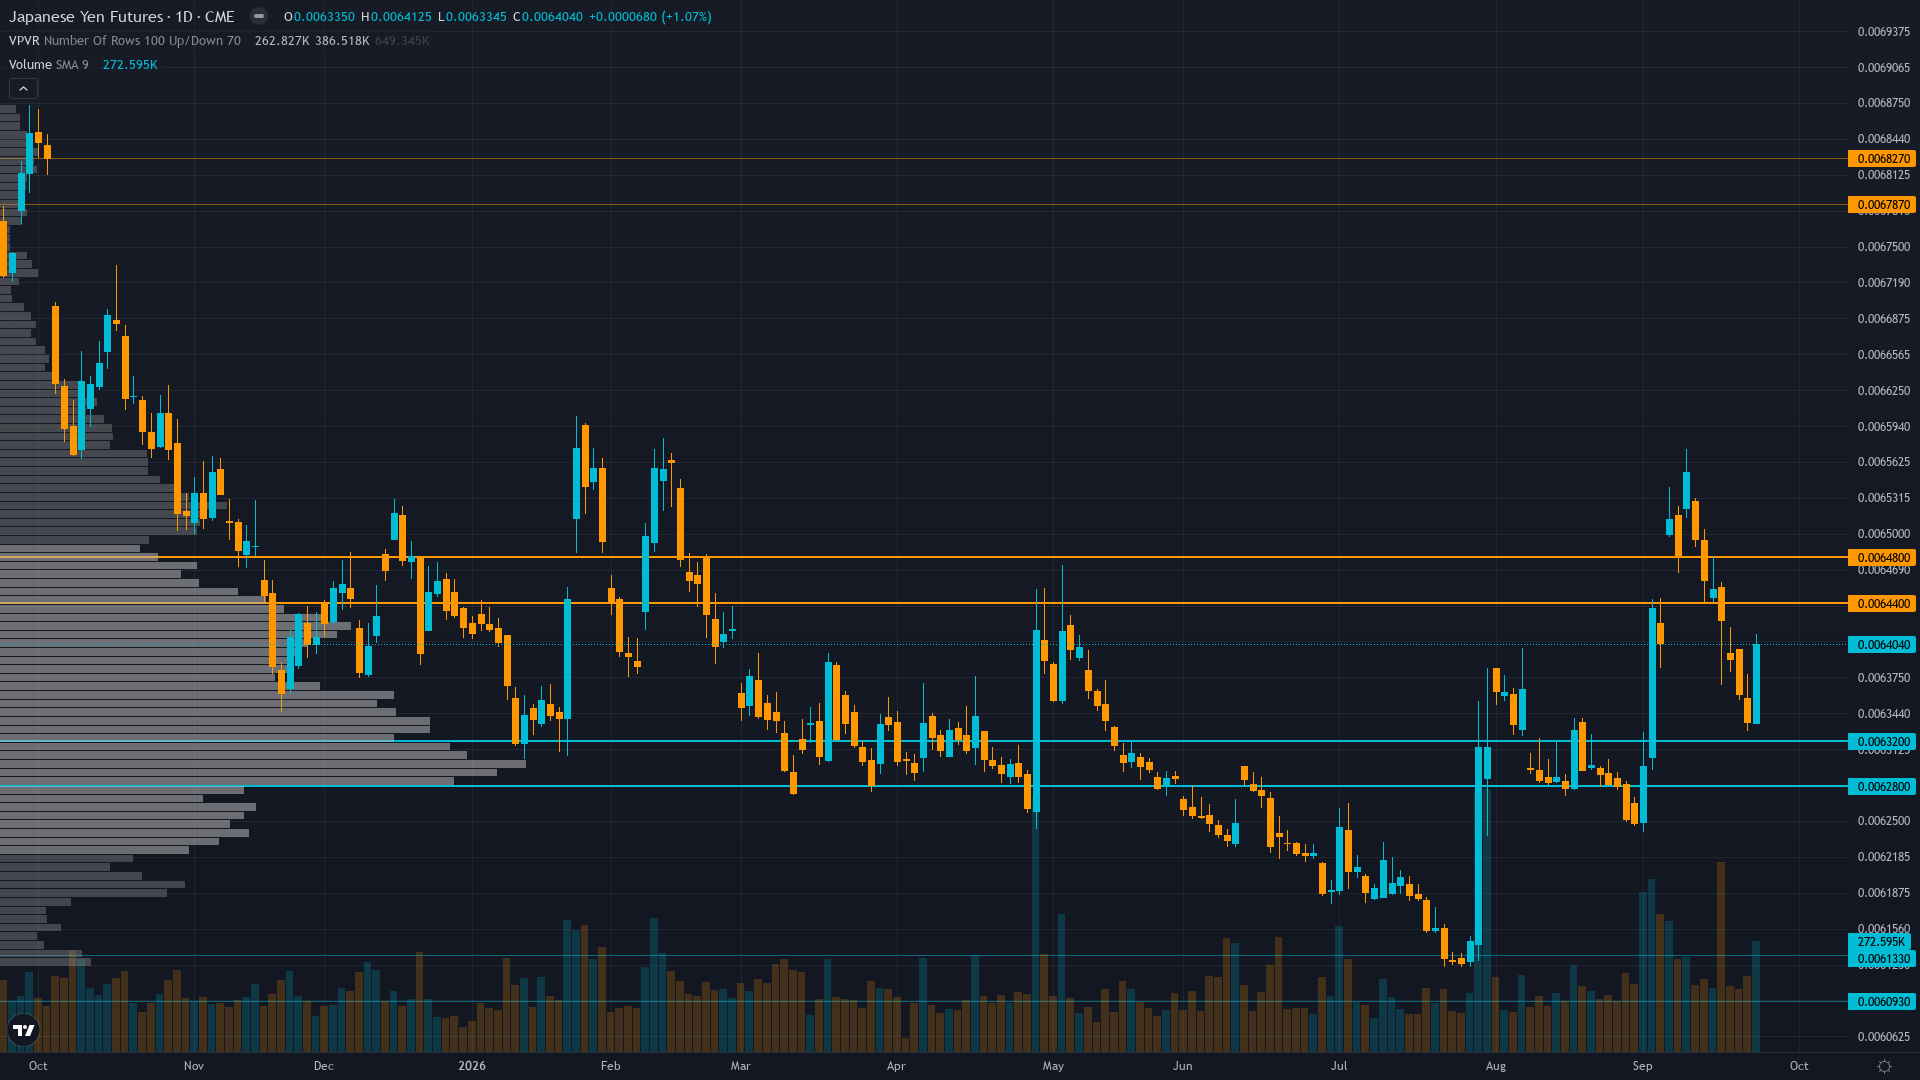
Price at 0.006395 (USD/JPY ~156.4) in the lower 40.6% of 52-week range, below the 50-day MA at 0.006460, RSI neutral at 51.7, no clear pattern — consolidating after the post-BOJ reversal from 0.0065 to 0.006395
Trend strength registers just 3/10, which typically corresponds to choppy, directionless price action.
Volatility Regime
Volatility for JPY is at the 52th percentile over 90 days — a normal regime that allows for standard position sizing and conventional trade management. The vol trend is flat, with no meaningful shift across timeframes. Stable vol environments often lull traders before a regime change arrives.
Normal vol regime suggests 50-65 pip daily ranges (0.00032-0.00042 in 6J terms); the post-catalyst environment reduces the probability of catalyst-driven spikes but extreme positioning (+120K net long) creates potential for positioning-driven 80-100 pip days if stop-losses cascade
What to Watch
Japan S&P Global Services & Manufacturing PMI (Sep) — services estimate 52.7 vs prior 52.5, manufacturing estimate 55 vs prior 54.9; strong prints would support BOJ normalization narrative while weak prints would validate 'sell the fact' yen weakness (Thursday 24 September) sits in the medium-impact category — unlikely to single-handedly shift the picture, but capable of adding directional fuel.
The interplay between consolidating market conditions and upcoming catalysts will define this week's trading landscape for 6J futures.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime