Crude Oil Forecast This Week — Outlook, Drivers & Key Levels
This week's Crude Oil outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

Market Overview
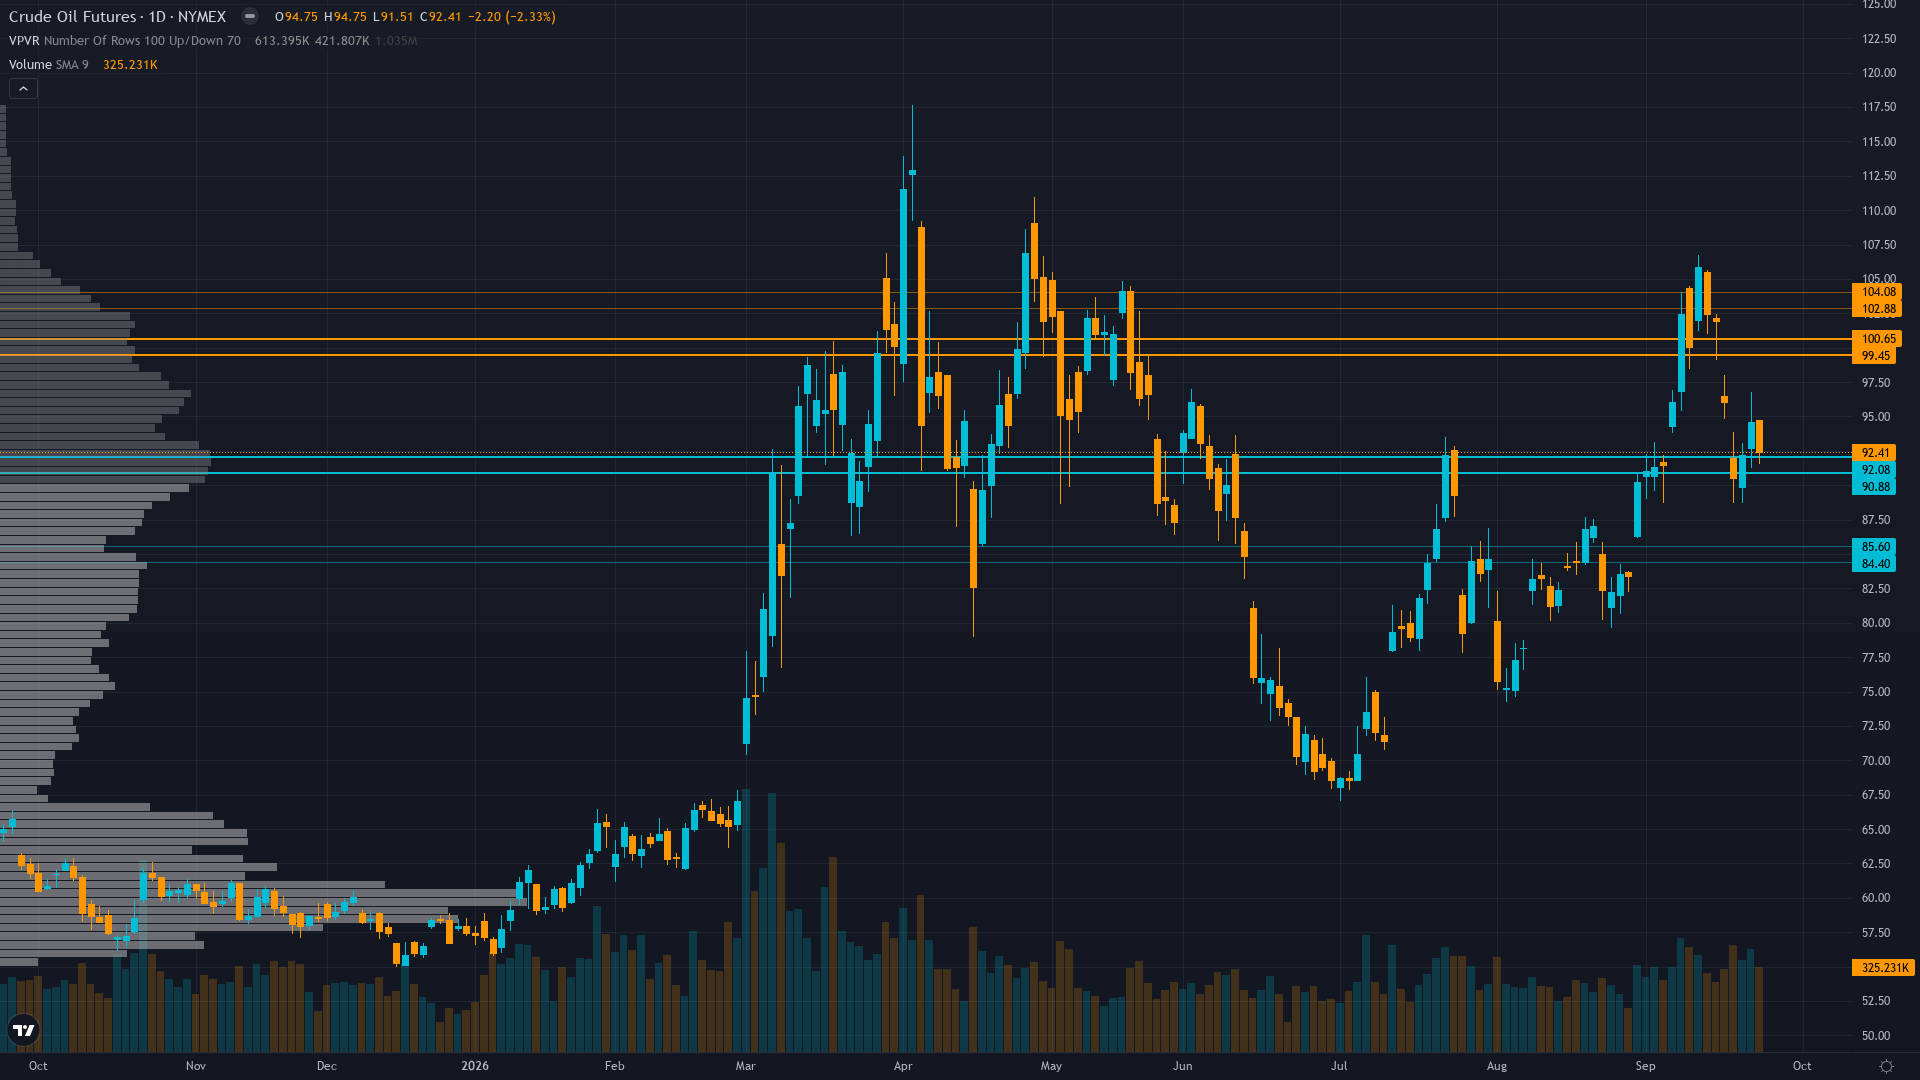
crude oil pushed to 92.41 on a 1.86% advance, reflecting sustained demand across the session. crude oil futures is range-bound and tightening, with decreasing volatility signalling a directional resolution ahead.
Market pricing accelerating Hormuz de-escalation with WTI down -7.87% for the week reflecting the first credible diplomatic breakthrough since June; Polymarket shows 100% probability of WTI hitting $95 in September, but the recent collapse suggests this binary market may be slow to reprice the full de-escalation scenario with $85-90 now the downside target if Iran's 7-day reopening offer is accepted
This Week's Catalysts & Drivers
Primary driver: Strait of Hormuz de-escalation accelerates — Iran offered to open the strait in 7 days at UN talks (CNBC Sep 25) with US-Iranian negotiators meeting in New York (Fox News Sep 26), triggering a -7.87% weekly collapse as the geopolitical premium that sustained $100+ pricing begins rapid unwinding
Secondary factor: Fundamental overvaluation reasserts — WTI at $92.41 remains 15-20% above marginal production costs of $75-80/bbl (Fundamental Analyst Sep 27), with the IEA September Oil Market Report revising global demand forecasts down by 940k bpd, China demand declining 600k bpd (8.9% annually per Sinopec), and OPEC+ completing its voluntary cut rollback adding 188k bpd of supply in September
Additional influence: Seasonal headwinds from US fall refinery maintenance — IIR Energy reports PADD 2 has the biggest fall maintenance season starting in September (Industrial Info Sep 17), reducing crude runs and compounding demand-side pressure through the Sept-Oct shoulder months when September is historically crude's weakest month (Seasonality360)
Economic backdrop: DIVERGENT macro regime — VIX at 16.34 signals neutral-to-complacent equity risk appetite while the energy complex trades on its own geopolitical binary; 10Y yields at 5.17% continue climbing (+16bp in 1 week) creating demand-side headwind; Fed maintaining 3.63% with 75.8% probability of 25bps hike at October 28 meeting per CME FedWatch; US consumer sentiment at 51.7 remains deeply pessimistic (lowest since 2022), reinforcing economic slowdown concerns
Fundamental assessment: WTI at $92.41 appears moderately overvalued at 15-20% above marginal production costs of $75-80/bbl (Fundamental Analyst Sep 27), with the entire premium sustained by geopolitical disruption risk that is now rapidly unwinding via US-Iran UN talks; structural oversupply thesis — IEA demand downgrade of 940k bpd, China demand -8.9% y/y, US production at record 13.8M bpd — will reassert once the Hormuz risk premium fully dissipates
Technical Picture
WTI at $92.41 after a -7.87% weekly decline from $100+, price still above both 50 and 200-day MAs but the momentum has decisively broken from the September uptrend; RSI around 57 showing neutral room in either direction; the prior breakout above $100 has been fully retraced with key support at $90 being tested intraweek before a bounce to $93.02 on Sep 25
At 4/10, trend strength is middling — enough to suggest a lean, but not enough to trade with high confidence.
Bull & Bear Case
Primary risk: Renewed Hormuz escalation if US-Iran UN talks collapse over conditions (Iran demands restoration of June MOU terms) or if Houthi attacks on Saudi infrastructure escalate, reversing the de-escalation repricing and driving WTI back above $95 toward $100 resistance (Probability: medium)
Primary opportunity: Continued de-escalation with Iran's 7-day reopening offer accepted by the US, removing the $10-15 geopolitical risk premium and driving WTI toward $85 fundamental support as speculative length liquidates and structural oversupply fundamentals reassert, with seasonal refinery maintenance and China demand weakness compounding the downside (Timeframe: 1-2 weeks pending US-Iran UN talks outcome this weekend through early October)
This week's edge: Resetting after 7 consecutive misses — thesis under review. The market has begun repricing the Hormuz geopolitical premium via the -7.87% weekly decline following Iran's 7-day reopening offer (CNBC Sep 25) and UN side talks (Fox News Sep 26), but the desk sees evidence that the de-escalation process may have further to run. The fundamental overvaluation (15-20% above marginal costs), seasonal weakness (September is crude's weakest month), and rapidly evolving diplomatic track (US-Iran direct talks at UN) create a coherent bearish thesis that the market is only partially pricing at $92.41. However, the 7-miss streak under Rule 5 mandates NEUTRAL — the desk cannot issue a directional bias until a CORRECT graded call breaks the streak. The $90 support held intraweek, suggesting the market is still pricing a residual risk premium for deal failure, but any further diplomatic progress this weekend could trigger a breakdown below $90 toward $85-88.
Volatility Regime
Volatility for oil price sits at the 85th percentile over 90 days — an elevated regime that demands wider risk parameters and faster decision-making. The volatility trend is up, with expansion across timeframes pointing to growing uncertainty in near-term price action.
Expanding volatility regime on binary geopolitical catalyst; expect 2.5-4% daily swings driven by UN diplomatic headline flow; the $90-95 range is the current trading band with $85 major support and $100 major resistance defining the outer boundaries for the next 1-2 weeks; stop placement at 1.5-2x ATR ($4-6) appropriate; trend-following is unreliable in this binary transition phase as the market oscillates between de-escalation and renewed escalation pricing
What to Watch
The API Crude Oil Stock Change (week ending Sep 25) — first inventory data point during the accelerated de-escalation phase, measuring whether Saudi additional supply via Sohar ship-to-ship transfers is appearing in US imports and whether refinery maintenance is reducing crude demand as expected on Tuesday 29 September stands as the week's primary risk event — high-impact and capable of overriding the existing technical and sentiment setup.
The interplay between consolidating market conditions and upcoming catalysts will define this week's trading landscape for WTI crude.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime