AUD/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's AUD/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.
Current Market Picture
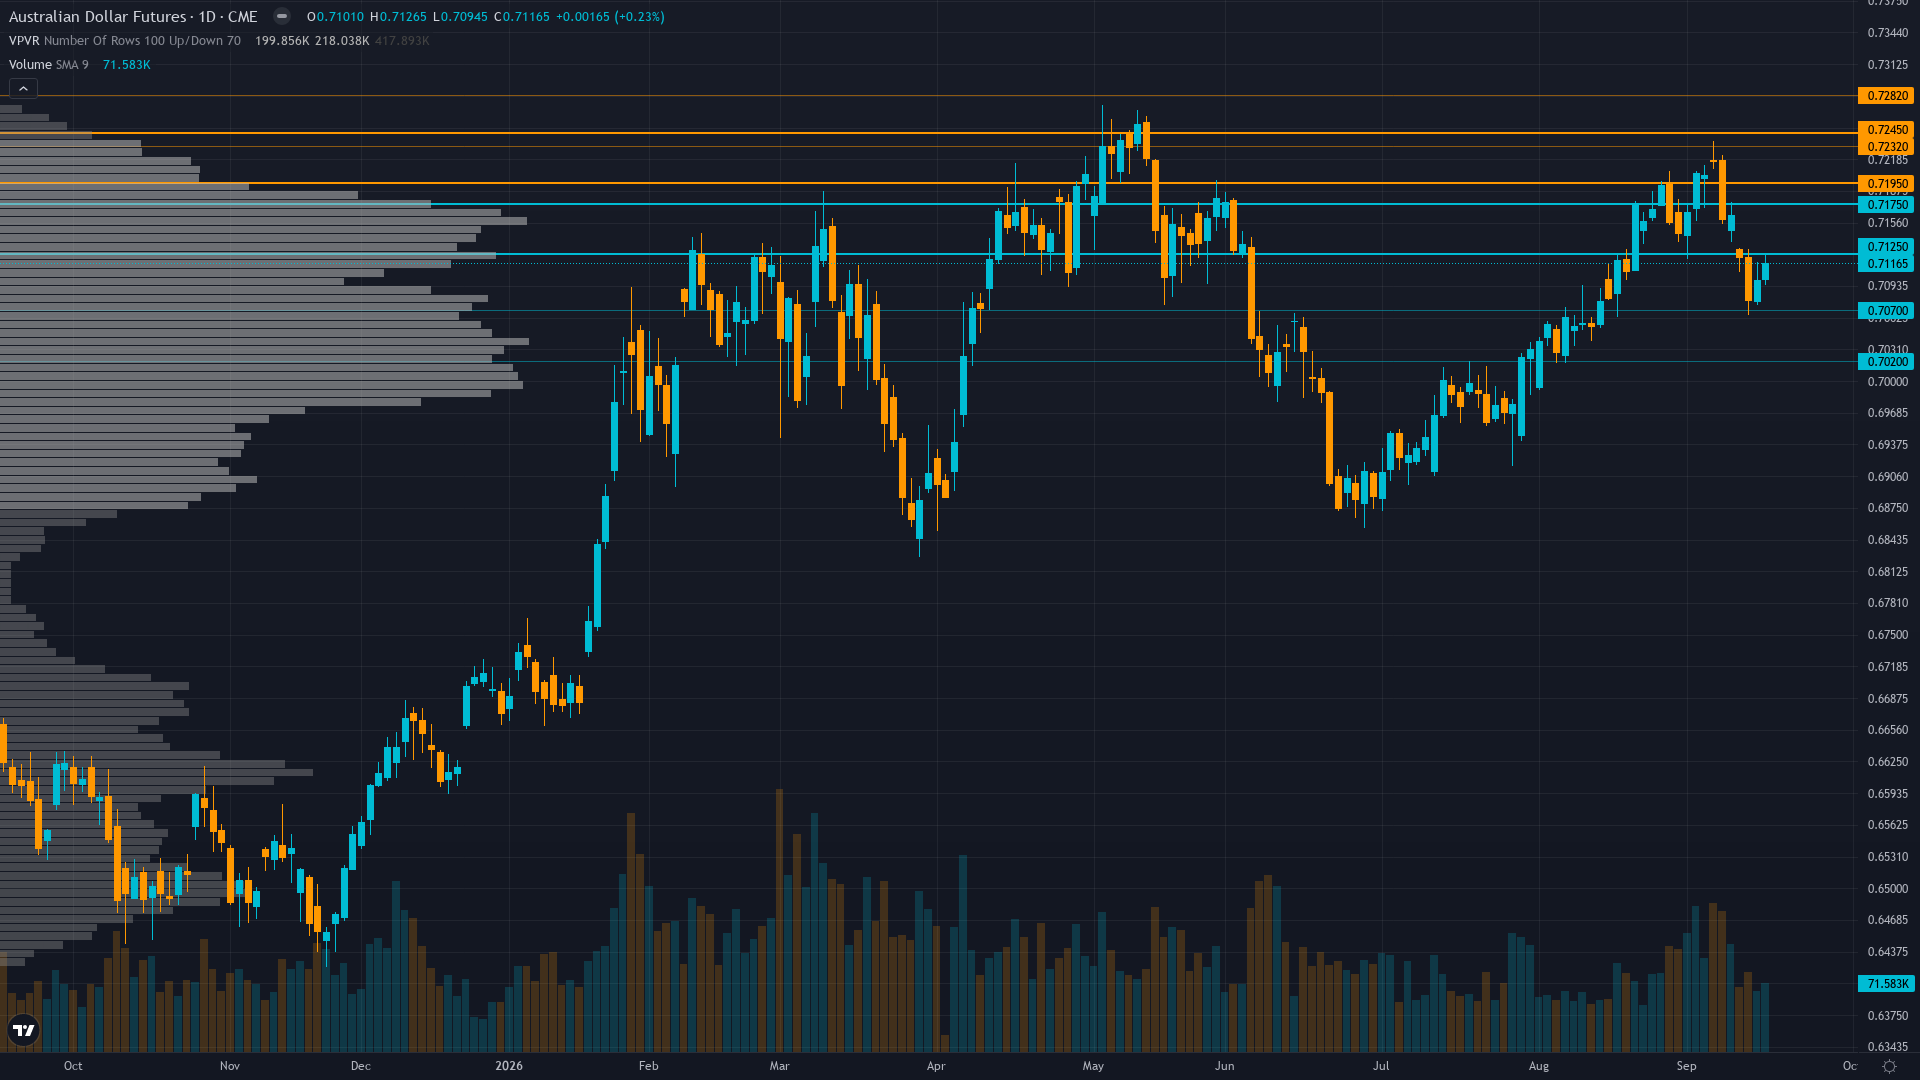
AUD/USD is trading at 0.71225, up a modest 0.15% as the market edges higher. The market in aussie dollar is coiling, with narrowing price ranges suggesting stored energy that will eventually release.
Market consensus is cautiously positioned for a September 29 RBA hike with 78-85% probability, AUD consolidating in a 0.7100-0.7200 range as the heavily-priced hike limits upside while employment data on Sep 24 provides the final pre-decision catalyst
Key Drivers This Week
Primary driver: RBA September 29 rate decision dominates positioning with markets pricing 78-85% probability of a 25bp hike to 4.60%, but Governor Bullock's Sep 18 parliamentary testimony confirming inflation risks have materialized is the freshest catalyst — the market is now pricing a near-certain hike that limits further AUD upside from a 'confirm' move while creating asymmetric downside risk if the RBA holds
Secondary factor: COT speculative shorts increased by -4,036 contracts to -38,906 as of Sep 15 (63.3rd percentile 3-year), reflecting bearish momentum that has been validated by the -0.71% weekly decline — shorts are now positioned with the trend rather than against it, reducing squeeze risk from the level seen in prior weeks
Additional influence: Australian employment data on Sep 24 (est +20K vs prior -15.8K) is the primary near-term domestic catalyst — a strong print above +25K would reinforce RBA hike expectations while a miss below +10K would raise doubts about the sustainability of the tightening narrative ahead of the Sep 29 decision
Economic backdrop: RISK-ON macro regime with VIX at 14.81 well below the 20 fear threshold, DXY at 100.21 trending slightly lower, US 10Y at 5.01% (+5bp weekly), Fed at 3.63% on hold, US inflation at 2.33% near target, RBA at 4.35% with 78-85% September hike probability — rate differential supports AUD structurally but RBI is mostly priced in
Fundamental assessment: AUD modestly overvalued (~1% above PPP fair value of 0.72), with structural headwinds from declining terms of trade (111.9 Q2 2026 vs 117 Q1) and widening current account deficit (-$27.2B June 2026), partially offset by RBA's hawkish stance versus Fed at 3.63%
Price Structure
Price at 0.71225 sitting at the 50-day MA (0.7115) after breaking below it intra-week, with RSI at 47.5 neutral and no clear pattern — consolidation in a 0.7100-0.7200 range that has held since early September with diminishing momentum
Trend strength at 4/10 paints a picture of a market with some direction but lacking strong conviction.
Upside & Downside
Primary risk: RBA delivers a hold at the September 29 meeting despite elevated market expectations (78-85% pricing for a hike), triggering a sharp AUD sell-off as the 72bp policy divergence premium deflates, especially if employment data on Sep 24 underwhelms and weakens the case for tightening (Probability: medium)
Primary opportunity: Australian employment on Sep 24 surprises above +30K combined with hawkish RBA Hunter speech on Sep 21, confirming strong labor market conditions that justify the September hike, triggering a short-covering rally from -38,906 net shorts toward 0.7200 resistance — though the 78-85% hike pricing limits the upside from a 'confirm' scenario (Timeframe: 24-48 hours after Australian employment data on Sep 24, contingent on a strong print above +25K that reinforces the RBA hiking narrative ahead of the Sep 29 decision)
This week's edge: Below Min Signal threshold — NO CALL. The weighted signal of -0.70 falls below the FX_MAJOR threshold of 1.1, mandating NO CALL per Rule 2. The key structural divergence the desk identifies is between the market's near-certain RBA September hike pricing (78-85%) and accumulating domestic fundamental deterioration (declining terms of trade from 117 to 111.9 QoQ, current account deficit at -$27.2B). The market appears to be pricing the RBA policy divergence as a near-certainty without adequately discounting the asymmetric downside risk if the employment data on Sep 24 underwhelms or if the RBA holds on Sep 29 — but this recognition alone does not produce a signal strong enough to cross the Min Signal threshold and establish a directional call. The desk acknowledges the bearish structural lean from institutional positioning (shorts increasing with the trend) and deteriorating fundamentals, but lacks the catalyst proximity and signal strength to convert this into a directional call above the threshold.
Volatility Context
At the 42th percentile, AUDUSD volatility sits in a normal range, neither compressed enough to signal a breakout nor elevated enough to demand caution. Realised vol is holding its current level, suggesting the market has found a temporary equilibrium in its risk pricing.
Normal volatility at 42nd percentile with 20-day realised vol at 6.9% annualised suggesting 45-65bp daily ranges — stable but uninformative environment until next week's binary catalysts resolve; breakout above 0.7200 or breakdown below 0.7100 needs sustained follow-through from employment data or the RBA decision
Week Ahead Outlook
The next major catalyst is Australian Employment Change (Aug) — consensus +20K vs prior -15.8K, unemployment rate steady at 4.5% — a high-impact catalyst that will either reinforce or undermine the RBA September hike narrative on Thursday 24 September — a high-impact event that could materially shift the directional picture.
For aussie futures, the balance between existing momentum and scheduled risk events sets the stage for the week ahead.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime