AUD/USD Forecast This Week — Outlook, Drivers & Key Levels
This week's AUD/USD outlook: key drivers, volatility context, risk-opportunity assessment and the week ahead.

This Week's Starting Point
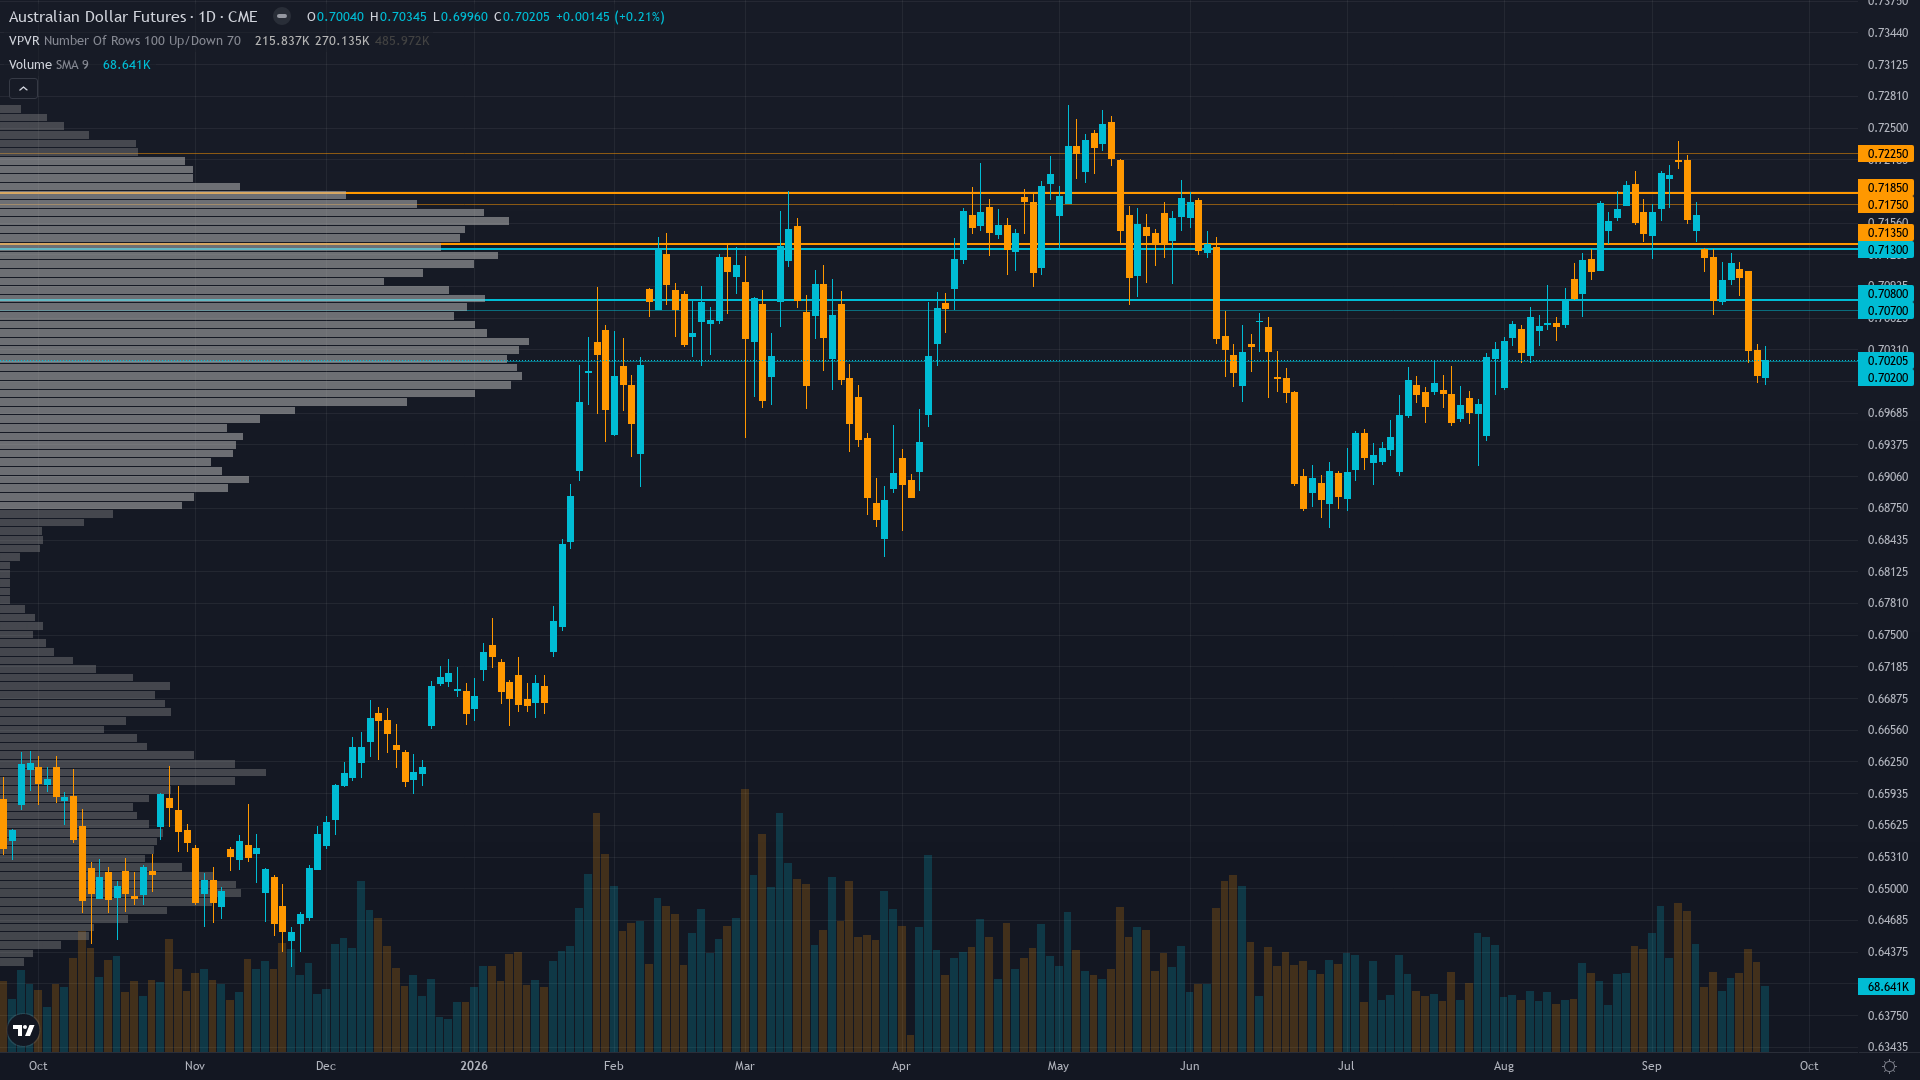
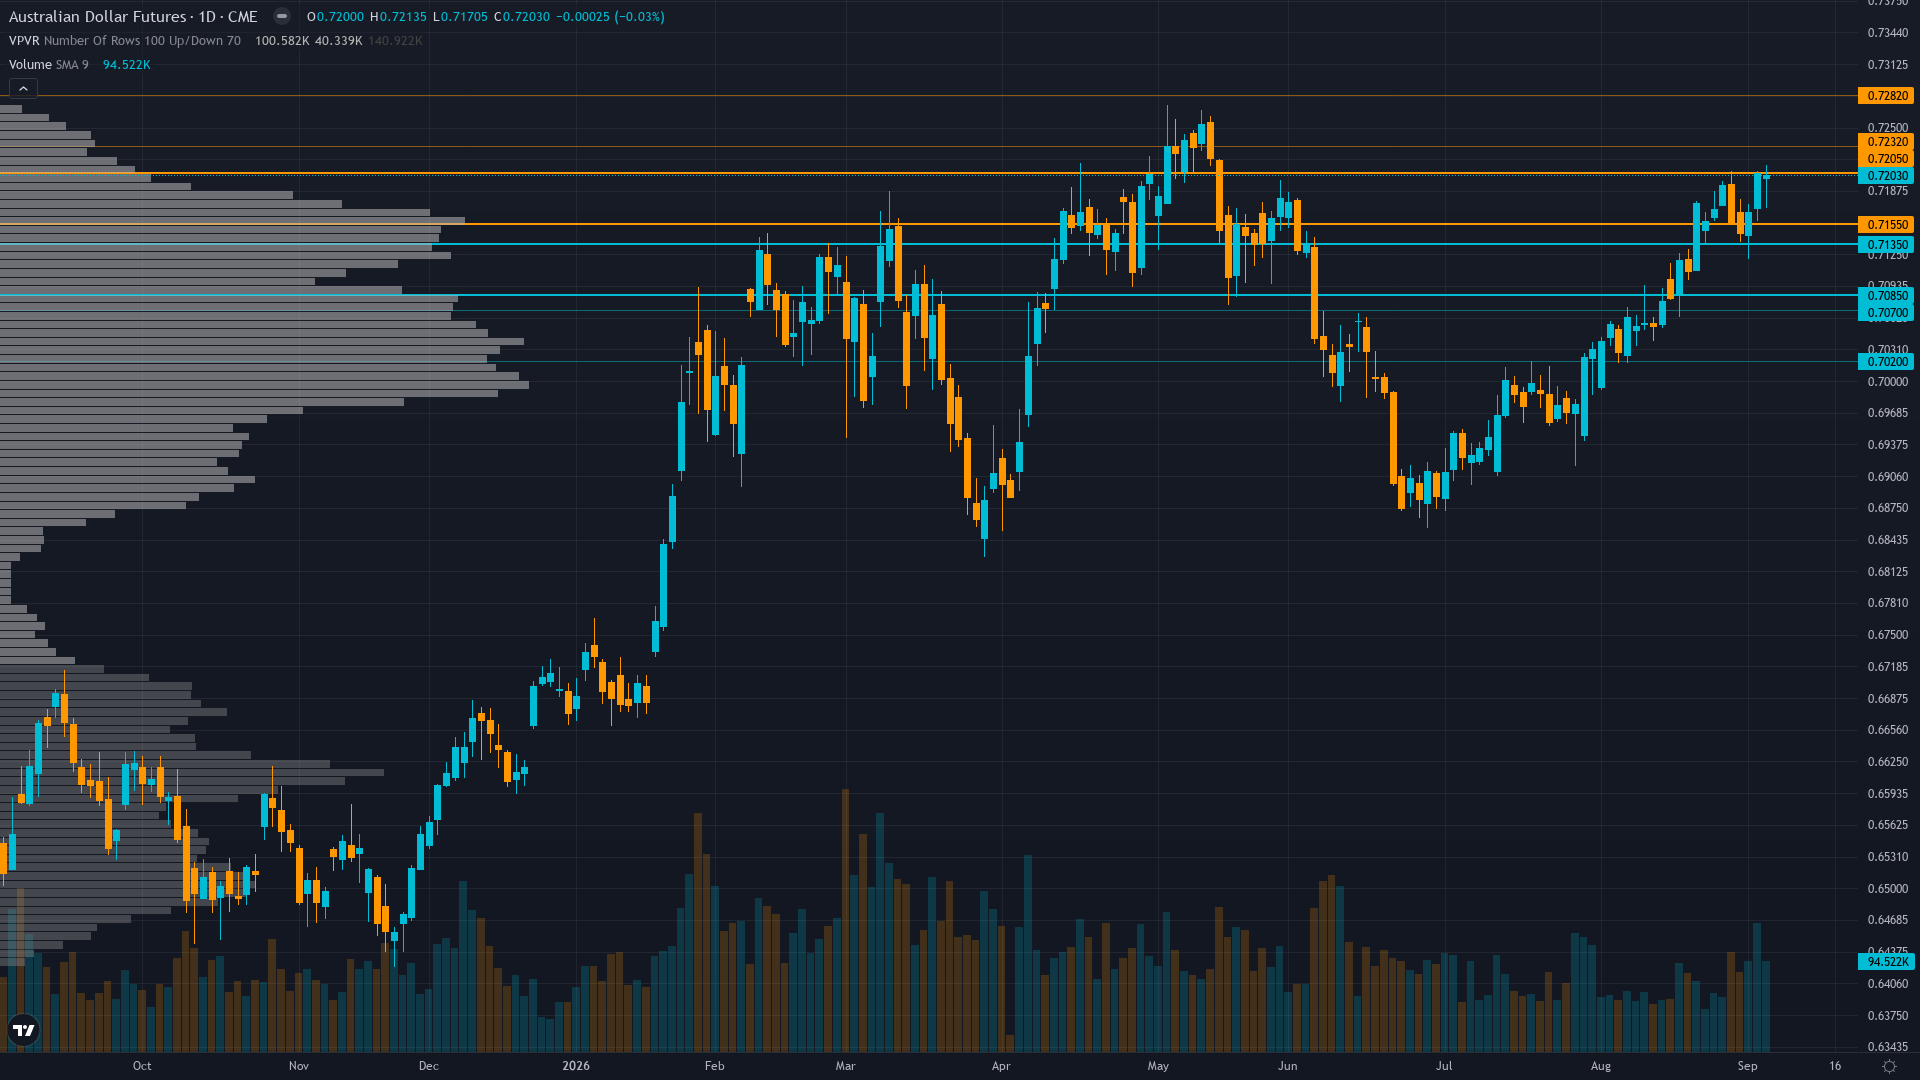
AUD/USD sits at 0.7203 after a 0.01% gain — a quiet move higher without aggressive momentum. Price action in aussie dollar has compressed into a consolidation pattern, typically a precursor to a directional breakout.
Market consensus cautiously bullish on AUD supported by the RBA policy advantage (4.35% vs Fed 3.63%) and elevated commodity prices, but the rally has stalled near 0.7200-0.7214 awaiting China trade data and RBA September 29 decision for directional resolution
Forces in Play
Primary driver: AUD grinding higher near 52-week highs at 0.7203 (+0.64% weekly, +2.42% monthly) driven by the RBA's 72bp policy advantage (4.35% vs Fed 3.63%) and broad USD weakness, but the rally has reached the upper bounds of the 52-week range (93.3rd percentile) where profit-taking risk intensifies
Secondary factor: RBA rate decision on September 29 is the critical binary catalyst with market pricing now showing 55.4% probability of a 25bp hike to 4.60% per RBA Rate Watch (Sep 2), driven by NAB's explicit September hike call and persistent trimmed mean inflation at 3.6% — a hike would extend the policy advantage to ~97bp and act as a powerful AUD catalyst
Additional influence: China trade data (Sep 8, est surplus $120.1B vs $112.5B) and China inflation data (Sep 9) are the immediate catalysts this week — strong Chinese demand data would reinforce commodity demand narrative for Australia's largest export partner, while any disappointment could trigger short-term profit-taking from current elevated levels
Economic backdrop: RISK-ON: VIX at 16.34 (below 20 threshold), US Treasury 10Y at 4.78% (+5bp weekly), curve steepening (2s10s +41bp), US inflation at 2.35%, Fed on hold at 3.63%, RBA maintaining hawkish stance at 4.35% with 55% market-implied September hike probability — macro backdrop supportive for commodity currencies broadly
Fundamental assessment: AUD modestly undervalued (~3-5% below PPP fair value), supported by RBA's 72bp policy advantage (4.35% vs Fed 3.63%) and elevated commodity prices, but Q1 current account deficit at AUD 27.1B (largest since 2016) and declining terms of trade represent accumulating structural headwinds
Technical Landscape
Bullish trend intact above 50-day MA (0.7045) and 200-day MA, price at 0.7203 near 52-week highs (0.7257), RSI at 68.13 approaching overbought territory, consolidating in a narrow range with resistance at 0.7214 recent high
Trend strength registers at 6/10, suggesting meaningful but not extreme directional bias.
Risk-Reward Assessment
Primary risk: China trade data on Sep 8 disappoints expectations ($120.1B est vs $112.5B prior), triggering profit-taking from near 52-week highs as commodity demand concerns resurface, pulling AUD back toward 0.7125 support as speculative shorts maintain their -39K net position (Probability: medium)
Primary opportunity: China trade surplus surprises to upside above $120B combined with a Westpac Consumer Confidence beat, validating the commodity demand and domestic growth narrative, triggering a squeeze on -39K net speculative shorts and pushing AUD through 0.7214 resistance toward the 52-week high at 0.7257 (Timeframe: 48-72 hours after China trade data (Sep 8) and China inflation data (Sep 9) resolution, contingent on both catalysts providing positive confirmation)
This week's edge: Below Min Signal threshold — no directional call. The weighted signal of +0.30 falls below the FX_MAJOR threshold of 1.1, mandating NO CALL per Rule 2. The key structural divergence the desk identifies is the persistent COT speculative net short position (-39,406 contracts at 63.3rd percentile) coexisting with price at the 93.3rd percentile of its 52-week range — this is an unusual configuration where shorts have not capitulated despite a sustained rally, creating asymmetric squeeze risk if the RBA delivers a September hike, but equally creating vulnerability if China data disappoints and the shorts are validated. The desk acknowledges the bullish structural lean based on RBA policy divergence (72bp, potentially expanding to 97bp) and AUD undervaluation (3-5% below PPP fair value), but the sub-threshold signal, dense catalyst week, and extreme 52-week range position (93.3%) prevent directional conviction above the Min Signal threshold.
Risk Environment
With vol at the 42th percentile over 90 days, AUDUSD is in a measured regime that doesn't require unusual adjustments. Volatility is stable, with realised vol holding steady across timeframes. This equilibrium can persist but eventually resolves into expansion or contraction.
Normal volatility at 42nd percentile with 20-day realised vol at 5.9% annualised suggests 45-65bp daily ranges — stable but uninformative environment until this week's binary catalysts resolve; breakout above 0.7214 or breakdown below 0.7125 needs sustained follow-through from China trade or US PPI data
Looking Forward
All eyes turn to Westpac Consumer Confidence (Sep) and China Balance of Trade (Aug) — dual catalysts testing the AUD's commodity demand thesis and domestic growth narrative simultaneously on Tuesday 8 September, which carries enough weight to force a decisive directional move.
The week ahead for aussie dollar hinges on whether the prevailing consolidating regime can absorb the scheduled catalysts without a regime shift.
This analysis covers one dimension. Our full weekly report combines six specialist agents into a single actionable briefing with directional bias, key levels, and risk-opportunity matrix.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime