30-Year Treasury Key Levels This Week — Support, Resistance & Confluence Zones
30-Year Treasury key levels breakdown: support zones, resistance zones, confluence and price structure.

Price Architecture
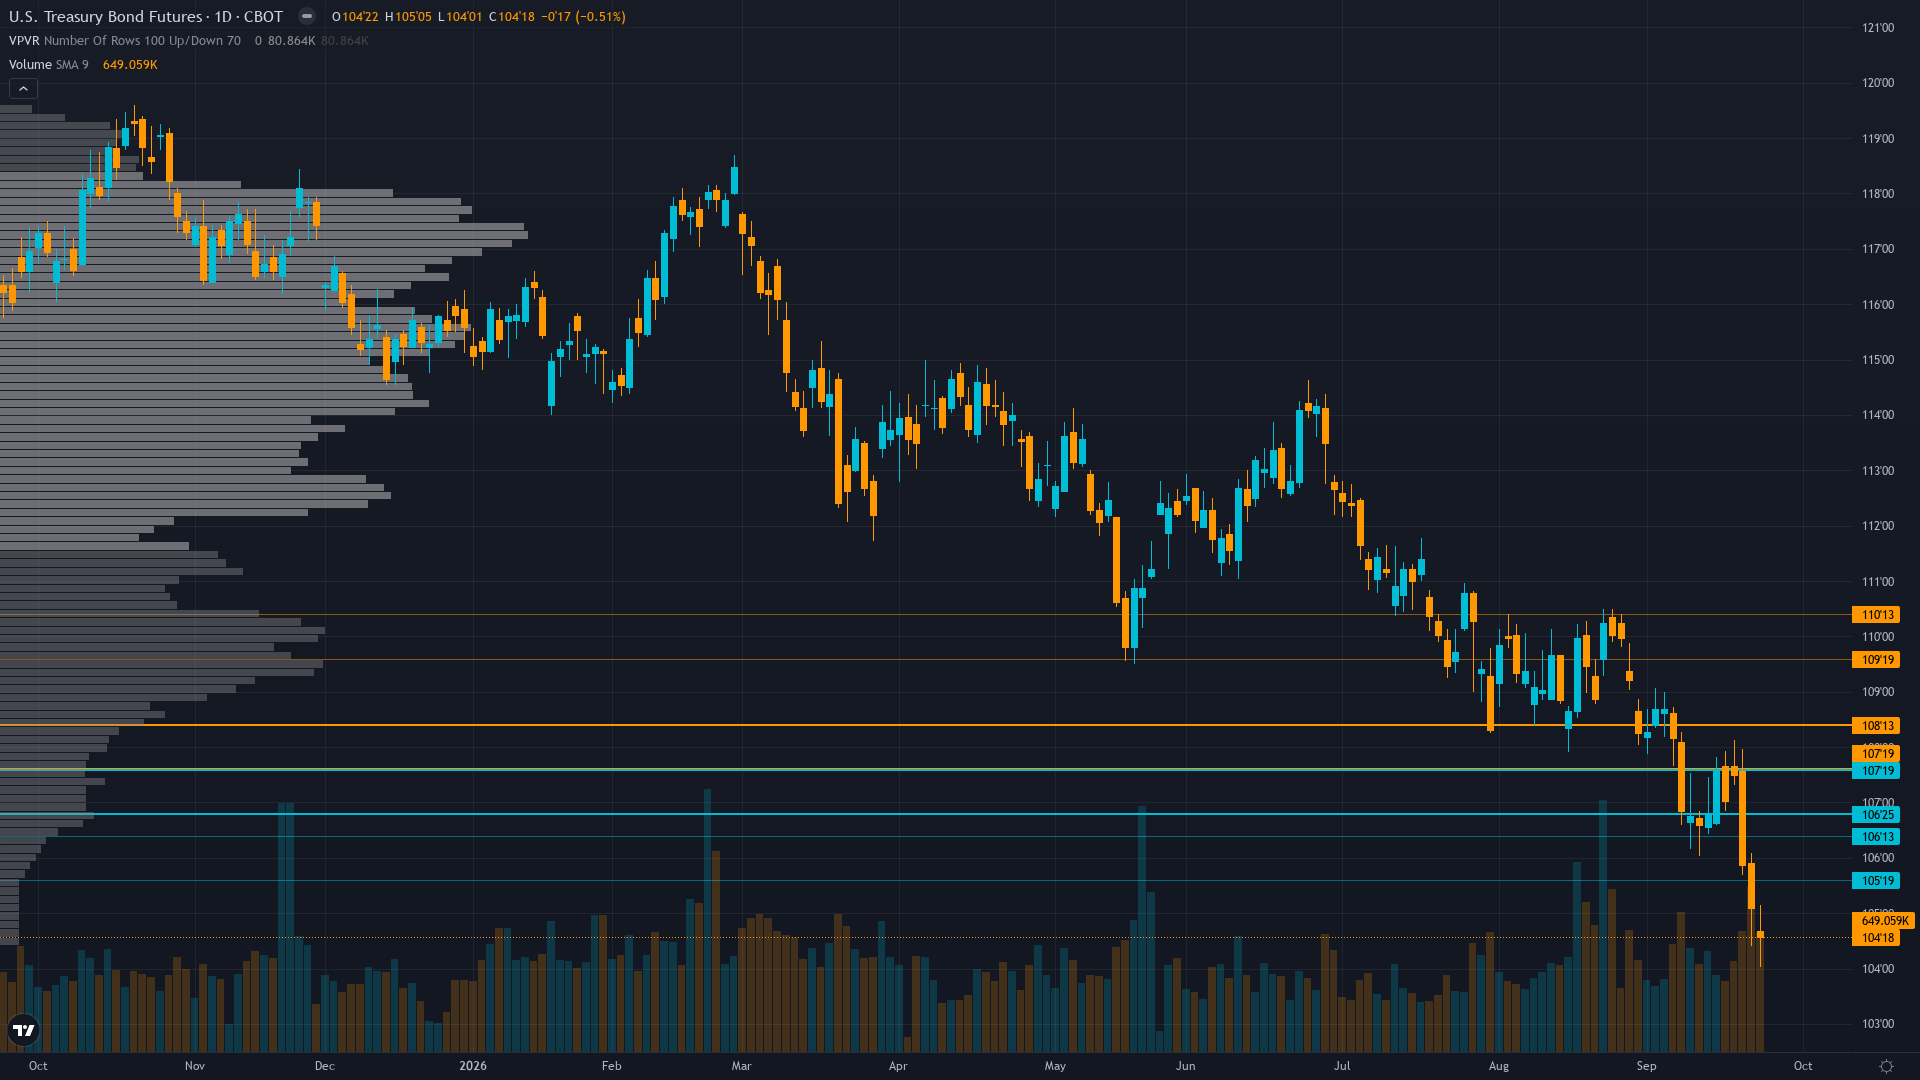
30-year Treasury sits at 104.6875 after slipping 0.51% — a shallow pullback rather than a decisive move. Treasury bond futures is in a breaking down market state, requiring careful assessment of current conditions.
Daily downtrend accelerating into capitulation: price at 104.6875 at the absolute 0th percentile of 52-week range (104.5625-119.2813) after breaking below 106.00 psychological support; price massively below 50-day and 200-day moving averages; RSI deeply oversold; 20-day realised vol at 8.4% elevated relative to ZB's 0.59% avg weekly move; declining open interest at 1.89M in the selloff suggests liquidation not fresh accumulation
Trend strength is elevated at 9/10, indicating strong directional conviction in current price action.
Downside Protection
The downside architecture for long bond features support zones rooted in prior buying activity. These are not arbitrary lines but areas where real capital has previously been committed.
The reliability of support under breakdown conditions is shaped by the interplay between volatility regime and historical volume at each level.
Resistance Zone Context
The upside path for T-bond futures is marked by resistance zones where prior selling activity created structural barriers. Clearing these zones requires either strong momentum or a shift in the fundamental picture.
In the current market state, resistance zones remain key decision points.
Analytical Convergence
The most actionable levels for 30-year Treasury are those where multiple analytical disciplines converge. When technical structure, institutional positioning, and options flow all point to the same zone, the probability of price reacting there increases meaningfully.
Volatility is in a high and rapidly expanding regime creating conditions for violent breakout moves in either direction; daily ranges have expanded from 0.5-0.7 handles during consolidation to 1.0-1.5 handles in the current breakdown; stop-loss placement is extremely challenging — standard ZB stop widths of 0.5-0.8 handles risk being triggered by noise within the expanded daily ranges; the divergence between MOVE (~104) and VIX (~16.34) highlights that this is a bond-specific volatility event, not a broad macro risk-off move, which creates the potential for a non-correlated squeeze if the catalyst shifts
Our Multi-Agent Approach to Key Levels
The levels in our paid reports are generated by six specialist agents working in parallel. Technical analysis provides the structural framework, institutional data shows where capital is committed, options flow reveals hedging behaviour, fundamentals anchor levels to value, sentiment gauges crowd positioning, and economic analysis times the catalysts.
The output is a curated set of levels with institutional-grade validation — the kind of multi-dimensional analysis that hedge fund research desks produce, delivered at a fraction of the cost.
Our paid reports include specific support and resistance levels identified by six specialist agents — technical structure, institutional positioning, options flow, fundamentals, sentiment, and economic analysis. Not just lines on a chart, but zones validated by multi-discipline confluence.
Start Free — Get the Market of the WeekFree weekly report · No credit card · Upgrade anytime