
Full Desk
AUD/USD (6A) — consolidating in normal regime
Market consensus prices range-bound consolidation in low-information environment with no fresh catalysts, AUD at 0.6982 mid-range reflects balanced two-way risk
Full Desk
Market consensus prices range-bound consolidation in low-information environment with no fresh catalysts, AUD at 0.6982 mid-range reflects balanced two-way risk

Full Desk
Mixed with fundamental bulls citing July 10 WASDE tightening stocks-to-use ratio and China demand resumption offset by technical analysts noting consolidation fatigue and export analysts highlighting Brazilian pricing advantages creating range-bound expectations between 1175-1200 ahead of August 12

Full Desk
Market pricing Fed on hold at July 28-29 FOMC with 95% probability maintaining 3.50-3.75% range per Polymarket; bonds consolidating 110-112 awaiting FOMC clarity on whether June 14 CPI -0.4% dovish surprise shifts forward guidance from June 17 hawkish dot plot with 9 members projecting 2026 hikes

Full Desk
Market violently rejecting WPIC structural deficit thesis with -6.4% monthly decline despite July 15 reconfirmation of 297 koz fourth consecutive deficit year, prioritizing investment demand collapse (225 koz Q1 ETF outflows) and elevated real yield headwinds above 2.30% over physical deficit fundam

Full Desk
Cautiously bullish on July 10 WASDE production shock confirming most severe U.S. wheat shortfall since 1972 with crop conditions at 26% good-to-excellent driving prices to May 2024 highs, yet increasingly concerned about sustainability above 700 given managed money record bearish positioning shift,
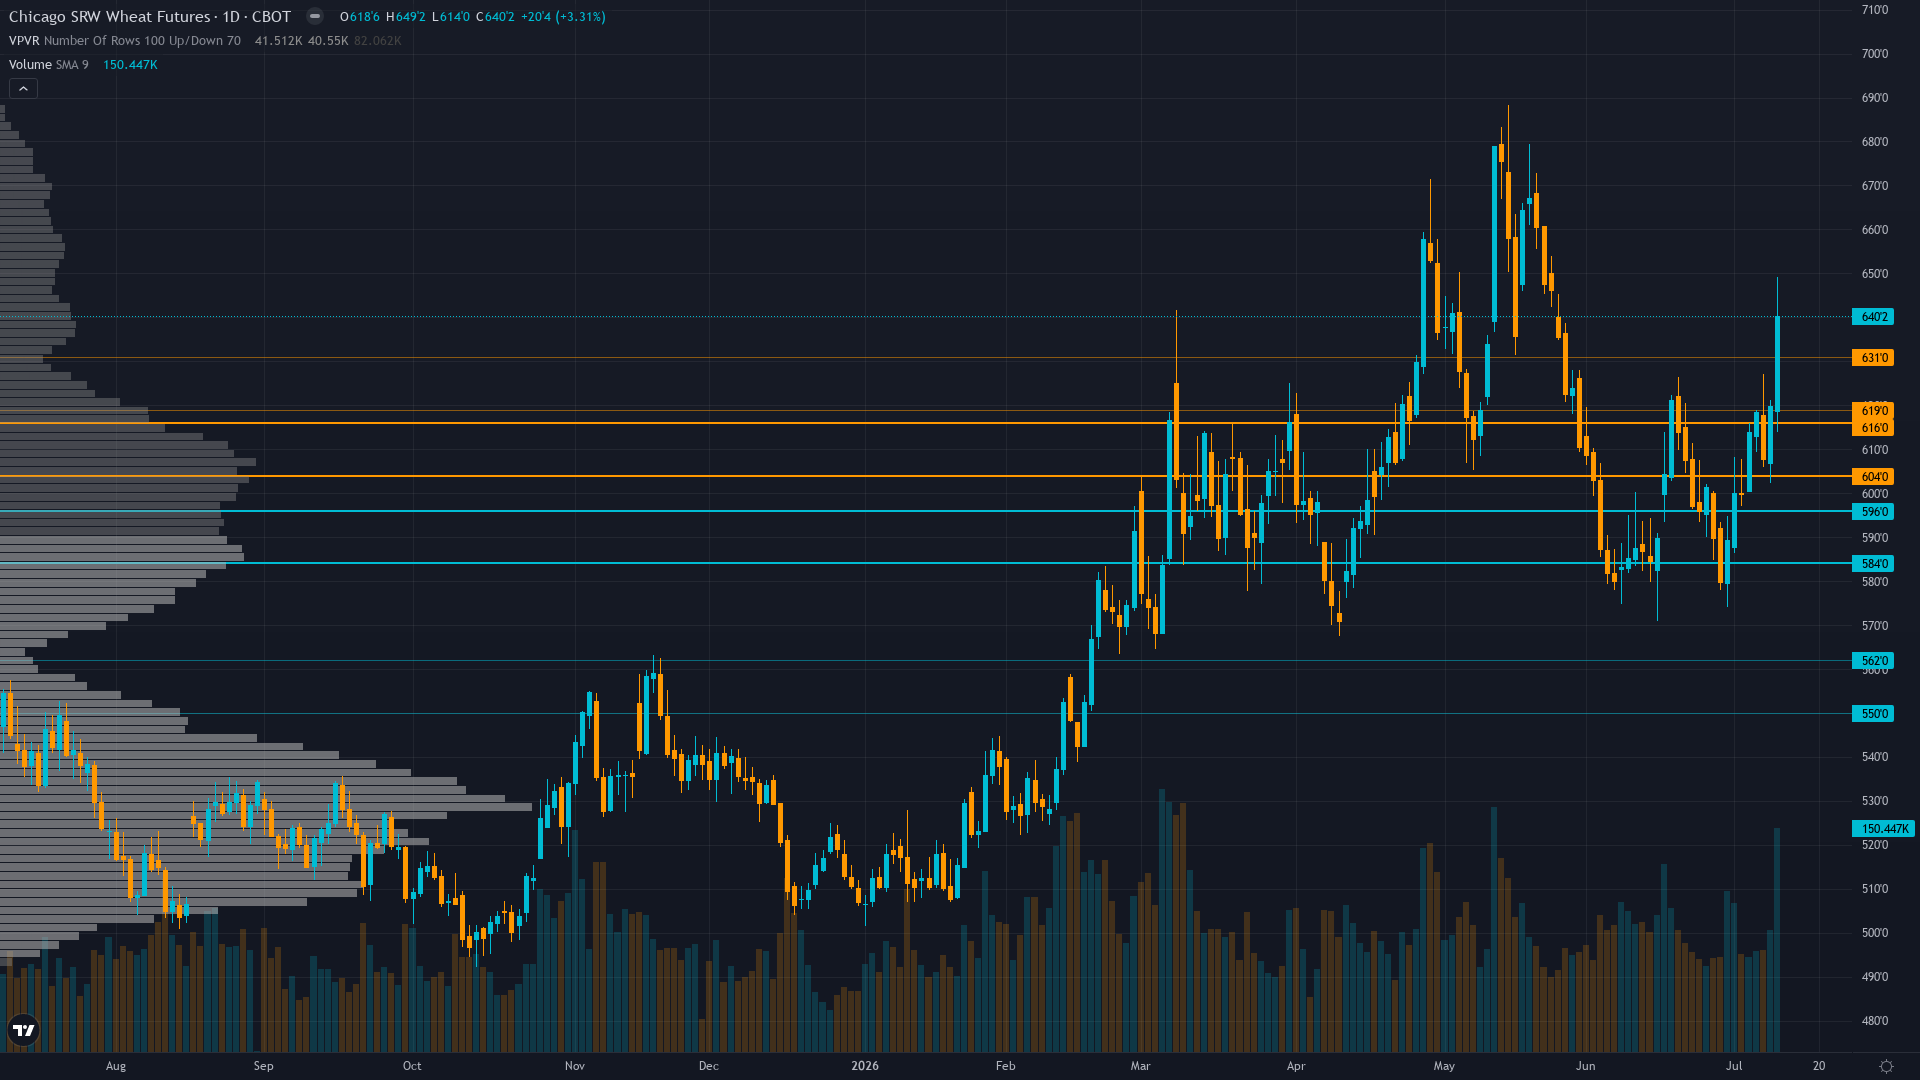
Wheat (ZW):
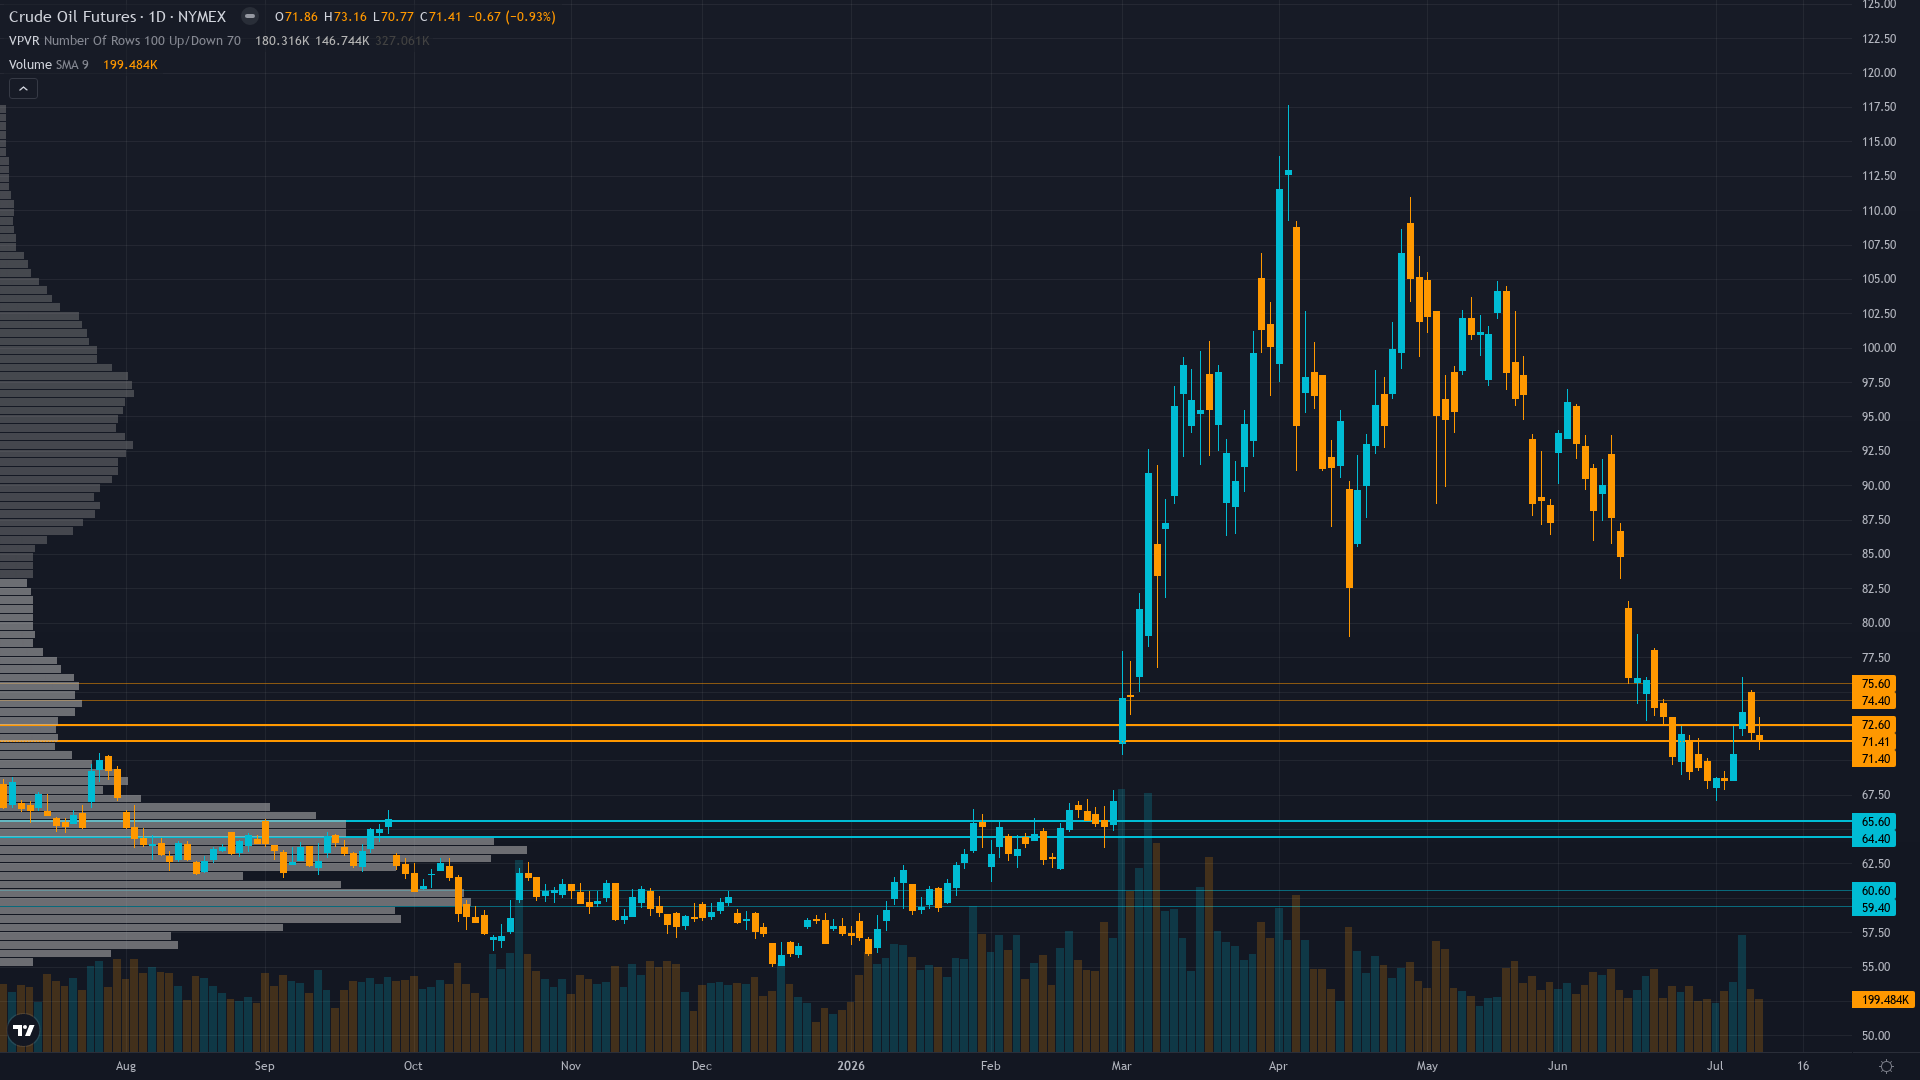
Core
Tactically uncertain with market having completed mean reversion as current $71.41 WTI at pre-war February levels MINUS $2 per IEA July 10 report; structural oversupply consensus (IEA 4.7 mb/d surplus, EIA -1.2 mb/d demand decline) validates bearish fundamental picture yet current pricing suggests f
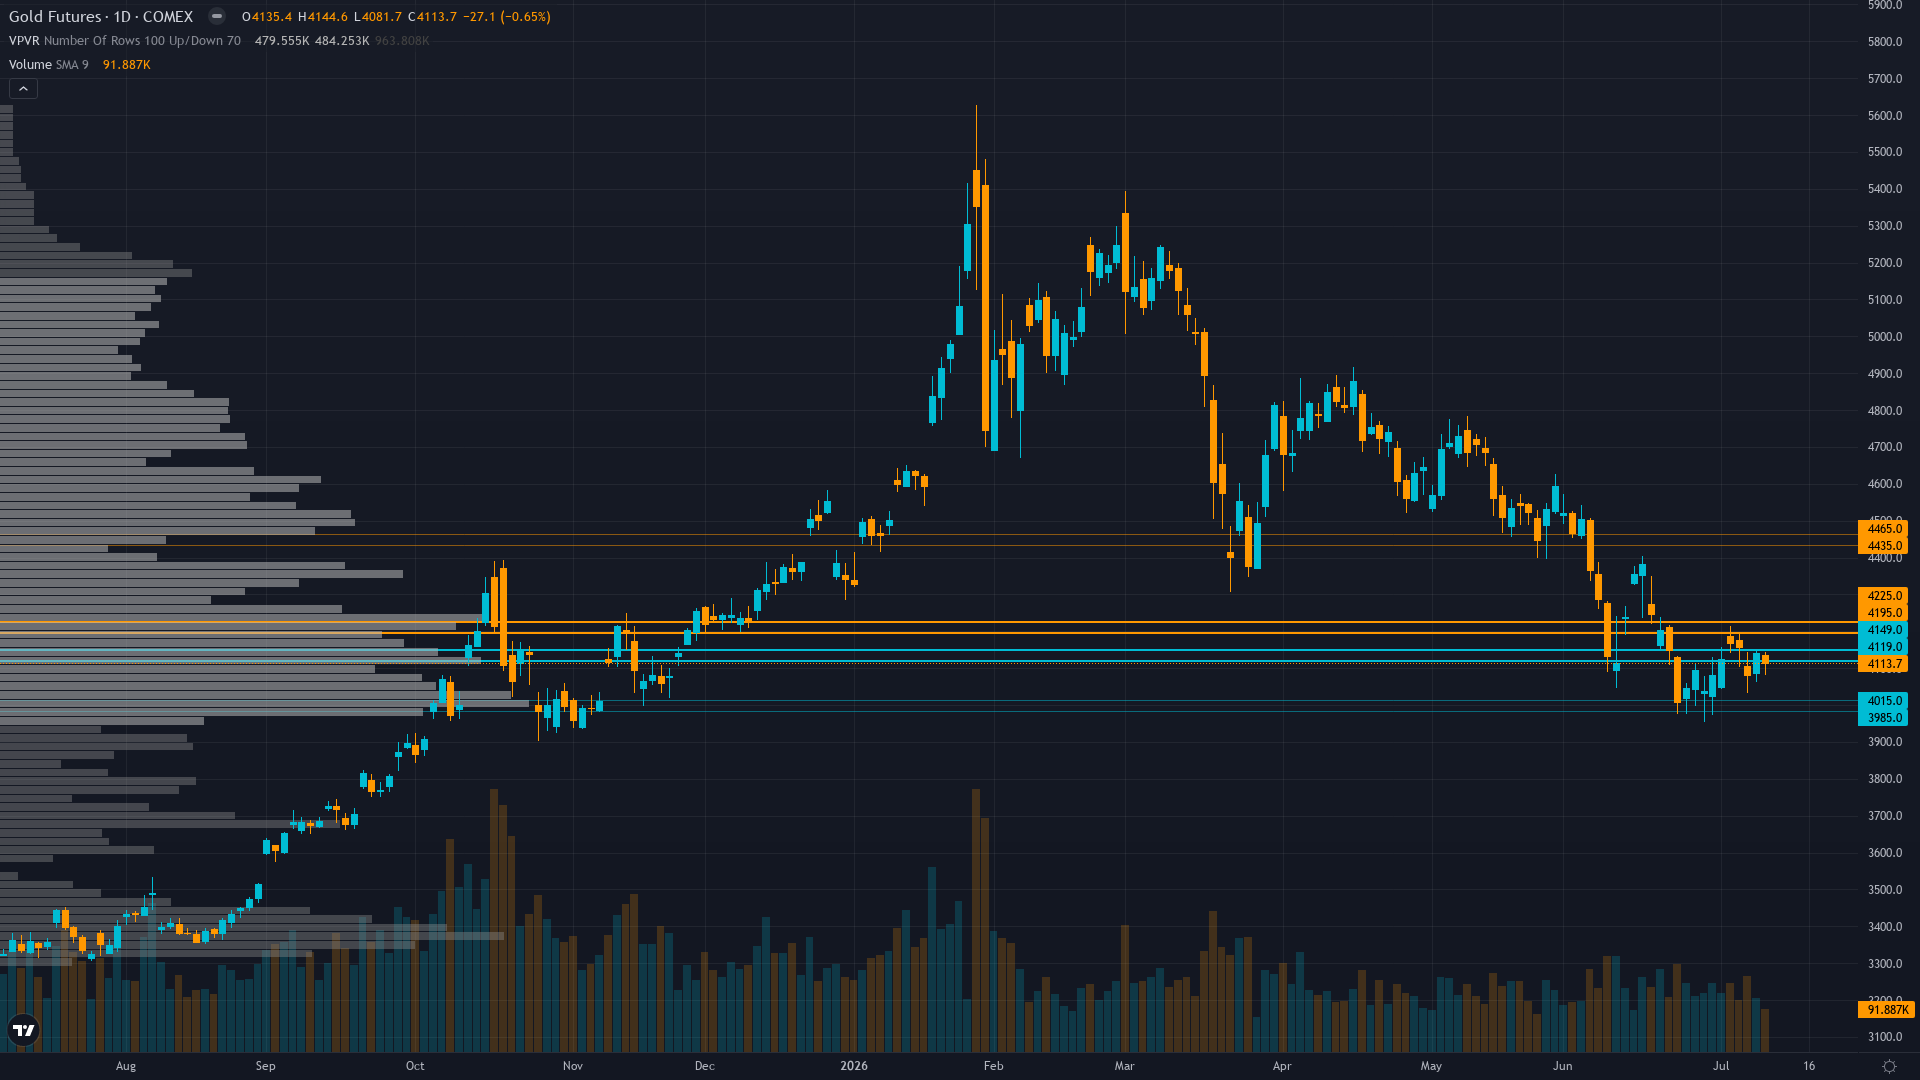
Core
Deeply divided with institutional year-end targets ranging from $4,900 (Goldman Sachs revised lower) to $6,300 (JPMorgan) maintaining structural bull case but near-term positioning increasingly bearish following July 1 Treasury yield shock, June ETF outflows $5.3B, and 27% correction from January pe

Core
EUR consolidation in 1.13-1.16 range through July 23 ECB meeting with neutral bias—markets efficiently pricing 70% July hike probability but 11-day catalyst vacuum creates range-bound conditions, year-end consensus targets 1.20-1.25 dependent on rate differential repricing

Core
Cautiously positioned ahead of late-July mega-cap tech earnings acknowledging technical consolidation and normalized VIX, but defensive given July 8 FOMC minutes hawkish tilt shifting July 28-29 meeting expectations and elevated valuations requiring execution

Core
Cautiously bullish on Q2 earnings strength and technical momentum above key moving averages, expecting Monday July 13 financial sector reports to validate 23.3% growth trajectory enabling grind toward 7,650-7,700 resistance, yet increasingly aware breadth deterioration and put/call 0.55 complacency

Extended
Market expects USD/JPY consolidation 160-162 range with mild bearish JPY bias on persistent rate differentials; BofA July 11 survey showing 4-year yen bearish extreme acknowledged but not priced as imminent reversal catalyst with next meaningful event July 30-31 BoJ meeting